Financial Literacy Education Could Help Many Americans

Financial Literacy Education Could Help Many Americans

Even as our region carries on to move earlier the worst results of the COVID-19 pandemic, source chain issues persist, there is developing inflation, labor and wage force, and increasing fascination fees. Though Us citizens perform to make sense of all this—and plan all around it—lack of economic literacy would make it complicated for several. About the extended run, this lack of information puts the American Desire at hazard for tens of millions. We consider the personal sector has an possibility and a obligation to enable address this by providing staff, people, customers and communities with greater obtain to economical education.

There is a big require for this form of exertion. These days, only about one particular-3rd of People have a performing knowing of desire rates, property finance loan fees and economical danger, in accordance to the Economic Marketplace Regulatory Authority. And this evaluate of financial literacy has fallen 19 per cent more than the earlier 10 years. This gap is estimated to have cost Americans more than $415 billion in 2020 by itself.

Lack of money capability is impacting Us residents both at dwelling, and in the place of work. Stress around revenue has been connected to sizeable overall health conditions including heart illness, diabetes, sleep issues and depression. These everyday living-threatening conditions can guide to pricey medical therapies, which in-transform produces extra financial anxiety and worry. Economical difficulties are now the second major bring about of divorce. In the office, 97{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of workforce concede they put in time doing work on or stressing about funds throughout the workday. Anxiety associated health problems expense companies nearly $300 billion each year in misplaced productivity, and 4 of 5 workers acknowledge to being monetarily pressured.

Black The usa proceeds to be particularly impacted by these issues. Extra than half (54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}) of Black Us residents have a credit rating score below 640, basically not able to absolutely take part in no cost enterprise The us. 50 percent (54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}) of Black Us citizens also report residing paycheck-to-paycheck, as in contrast to 44{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Americans over-all. Only 43{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Blacks possess their house, when compared to 72{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Whites. Blacks comprise 14{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the population, but individual only 3.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of small companies.

These are additional than just figures. Behind the quantities are actual folks: tens of thousands and thousands of dad and mom, seniors and young people enduring financial strain, private hardships and strained associations as they battle to help you save, borrow and devote in techniques that deliver larger fiscal steadiness, adaptability and stability.

To help handle these concerns, we’re joining jointly to co-chair Economical Literacy for All, an inclusive, small business-led motion aimed at helping a lot more Us citizens enjoy the benefits that come from earning much more informed fiscal selections. We system to empower reduced- and middle-revenue people and people of each and every history, every stroll of lifestyle and every single community—from city to rural and all details in between. We will use the artistic brilliance of our partners to make exhilaration and consciousness all around economical literacy by our associates, increase office wellbeing for working grownups and assistance initiatives to supply essential financial instruction to each and every college district in the nation. And, offered the prosperity hole faced by Black and Hispanic homes, we will guarantee our attempts are appropriate and quickly offered throughout those communities.

Because launching in May well of previous yr, the Economical Literacy for All movement has been joined by just about thirty other CEOs and board chairs, which includes the leaders of The Walt Disney Organization, the Countrywide Football League, the Countrywide Basketball Affiliation, Delta Air Strains, and quite a few other leading monetary establishments.

We think financial literacy can be inclusive, inventive, flexible and concentrated on benefits, and we think our coalition’s variety will help us make meaningful progress to that target. Disney, soon after all, specializes in participating and entertaining men and women via the power of storytelling. The NFL and NBA know how to attract and encourage enthusiastic audiences. Procedure HOPE is focused on equipping people today with the economical applications to create a much more secure future. And Walmart is deeply related to communities, with 1.6 million associates, extra than 4,700 merchants, serving additional than 137 million buyers a week across the US. Every member group will also do far more for its personnel and communities.

Our shared enthusiasm for improving upon financial schooling is rooted in our functions and values. Pretty much 60 years back, Walmart was started on the strategy of encouraging people today conserve money so they could dwell improved. Considering that 1992, Procedure HOPE has been striving to grow economic possibility and make absolutely free business perform for every person. Each individual of us sights this new endeavor as a pure extension of what our organizations have been executing for many years.

We know initiatives like these can make a big difference. As just a single case in point, Procedure HOPE has been giving no-charge, personalised economical coaching and instruction, serving to some elevate credit history scores 54 factors in six months, and more than 100 points more than 24 months, decreasing concentrations of personal debt, and aiding purchasers produce and maximize their price savings for emergencies and the potential. And, in some conditions, supporting strivers go from staying renters to homeowners, or from modest organization dreamers to smaller small business owners.

We comprehend that the economic difficulties struggling with millions of American homes are not able to be conquer entirely as a result of fiscal coaching. Other aspects are also keeping folks back, including obstacles to training, vocational coaching, economical products and services and job options as perfectly as discrimination of all types. These hurdles will have to also be addressed—and numerous in the personal sector are making meaningful development.

Even so, we imagine far better, much more available financial schooling and bigger stages of economic literacy could assistance hundreds of thousands of families. This and very similar varieties of get the job done, lifts ‘all boats’ across communities and across our nation. Increasing GDP as a result of increased monetary intelligence, benefits the entire of society, and generates extra sustainable chance for the nation. And the additional benefit—less stressed-out citizens and workers—translates into a lot more societal well being, for all. These are large targets, but we think they can be achieved—and that’s the problem we’ve set for ourselves. We urge other enterprise leaders to join this movement.

Extra Have to-Go through Stories From TIME

Call us at letters@time.com.

6 Tips To Avoid Personal Debt When Building A New Business

6 Tips To Avoid Personal Debt When Building A New Business

When starting up up a new organization, it requires hard cash to order the necessities. You require a web-site, business office space and devices, and several other charges, based on the firm you are setting up. But in which do those people funds appear from?

In accordance to a research led by Enterprise.org, 89{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of small businesses have utilised their private debt to fund their small business. “These money owed assortment from $5,000 to above $100,000, and 38 per cent of business people report that their personal credit rating has absent down because starting a business,” states Organization.org.

These high credit card debt ranges are attributed to the lack of ability to safe startup funding, and women of all ages have a additional complicated time securing new organization financing. According to nerdwallet.com, “businesses run by women are considerably less likely to be authorized for a small-business mortgage than those people run by adult males, according to the Federal Reserve.”

Nerdwallet.com has also outlined smaller company financial loan selections for you to discover. The substitute to in search of outside the house funding for your organization is to bootstrap your way.

Here are six techniques you can bootstrap your organization:

1. Concentrate on getting spending shoppers in the doorway initial

The major mistake startup enterprises make is by focusing on activities that are not revenue creating. You require to create profits from the starting to get money in the door, so target on profits and finding having to pay prospects right from the start off.

2. Demonstrate your offer you

Serving a number of paying out purchasers and owning shoppers satisfied with your supply is a way of proving or validating your supply. This is an necessary step that you really do not want to miss due to the fact you will bankrupt your company if you are trying to sell an offer you that persons never want.

3. Commit your gains into building the enterprise

You’re completely ready to make investments in sites and other factors that will assistance your organization when you have a tested give and having to pay consumers. You use the revenue you are earning each month to reinvest into the corporation to expand on internet marketing, marketing, and other providers that will maximize the business’s visibility and get extra shelling out clients in the door.

4. Seek the services of a team when you have 3-6 months of their income in income reserves

Don’t rush to retain the services of a team on payroll. You can get the job done with lots of consultants till you are all set to have a workforce on payroll. Often business enterprise entrepreneurs really feel they have to have their crew correct away, but you you should not want to hurry that determination.

5. Never try to do all the things at the moment

You don’t need to have to have your marketing great, sophisticated sales funnels established up or fancy web sites. You have to have a confirmed give that sells, and then you can mature and scale your company on a sound money basis.

6. Do not chase shiny objects

The online is loaded with business coaches and consultants who want your funds and will offer you you unrealistic promises of right away achievements to get it. Resist the temptation and develop your organization 1 phase at a time. Your wallet will thank you.

The base line is that there are benefits and negatives to financing your business, whether as a result of outdoors resources or bootstrapping. Irrespective of your alternative, it would aid if you were comfortable with your picked out strategy. On the other hand, bootstrapping a business enterprise and not taking exterior funding lets you to be in monetary management of your business and not give up any operational command.

Mortgage rates see largest decline since 2008

Mortgage rates see largest decline since 2008

The 30-calendar year fixed-amount mortgage loan averaged 5.30{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in the week ending July 7, down from 5.70{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} the week right before, according to Freddie Mac. That is nonetheless considerably greater than this time very last year when it was 2.90{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Charges rose sharply at the start out of the calendar year, hitting a substantial of 5.81{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in mid-June. But because then, economic fears have pushed them reduce. The 40 basis issue tumble offset some of the substantial fee boosts of May and June.

“Around the final two weeks, the 30-year fixed-level house loan dropped by 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} a per cent, as problems about a opportunity economic downturn keep on to rise,” explained Sam Khater, Freddie Mac’s main economist.

But affording a property still stays a problem. Home finance loan charges are at their greatest concentrations because the late 2000’s and listing prices have developed by much more than 8.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} calendar year-above-calendar year for 24 consecutive months, claimed Joel Berner, Real estate agent.com’s senior financial analysis analyst.

If there’s any silver lining for homebuyers, it is really that additional homes are hitting the marketplace, he stated. In June, lively listings improved by the greatest annual growth in the historical past of Real estate agent.com’s knowledge.

“With far more houses on the market place, sellers are getting compelled to contend on price ranges,” he reported. “Though the price tag of financing a residence continues to be high relative to recent several years, potential buyers will have far more chances to come across households in their price range as the undersupplied and overheated housing market place commences to interesting.”

Higher rates are also tamping down demand among possible potential buyers. House loan purposes dropped 5.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in the 7 days ending July 1 from the 7 days before, according to the Home loan Bankers Association.

“Fees are nonetheless appreciably increased than they ended up a calendar year back, which is why purposes for house purchases and refinances remain depressed,” said Joel Kan, MBA’s affiliate vice president of economic and market forecasting. “Obtain action is hamstrung by ongoing affordability difficulties and low stock, and house owners even now have lessened incentive to apply for a refinance.”

How much house can I afford?

Prospective buyers are obtaining it more challenging to acquire properties as inflation usually takes a more substantial chunk of their profits and the price of borrowing has decreased their paying for power.

A 12 months ago, a purchaser who put 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} down on a median priced $390,000 residence and financed the rest with a 30-year, preset-rate mortgage loan at an common price of 2.90{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} experienced a regular monthly home finance loan payment of $1,299, according to calculations from Freddie Mac.

These days, a home-owner purchasing the very same priced property with an typical rate of 5.30{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} would spend $1,733 a month in principal and desire. That’s $434 more every month.

The drop in mortgage costs this week follows recent volatility in the 10-yr Treasury yield, which dropped down below 2.8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in the 1st 7 days of July after paying most of June previously mentioned 3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

When the Federal Reserve does not established the curiosity rates borrowers pay out on home loans right, its steps impact them. Mortgage loan rates tend to observe 10-calendar year US Treasury bonds. As buyers see or anticipate level hikes, they typically provide federal government bonds, which sends yields higher and with it, home loan rates.

In addition, ongoing fears that we are heading into a bear current market have driven traders into safer, longer-time period bonds, claimed Berner.

“This inversion could possibly sound ominous, specially in the midst of sustained inflation that the two markets and the Fed agree will likely need far more fed money price hikes to tame, but it continues to be to be found whether these sector situations will lead to raises in the unemployment price or decreases in creation that characterize a recession,” he mentioned.

Business Services Gains Amid Job Market Growth

Business Services Gains Amid Job Market Growth

The skilled and small business products and services sector posted the largest gains very last month, introducing 74,000 work to the all round 372,000 in new openings, while the unemployment fee of 3.6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} remained the exact same for the fourth month in a row, the U.S. Bureau of Labor Stats described on Friday (July 8).

There were being 5.9 million individuals unemployed in June, about the exact as the preceding thirty day period.

Inside the professional and company providers sector, administration positions amplified by 12,000, laptop devices design and related companies went up by 10,000, administrative positions extra 8,000 work, and scientific investigate and development services greater by 6,000. The sector has 880,000 far more employment than it did in February 2020.

See also: Leisure, Hospitality Post Job Gains as Unemployment Retains Regular

Notable gains were being also witnessed in leisure and hospitality, introducing 67,000 jobs, with foods assistance and consuming establishment positions up 41,000. The sector is still down by 1.3 million since February 2020.

Health care work included 57,000 positions in June, with ambulatory expert services publishing 28,000 new positions, hospitals, 21,000, and nursing and household treatment facilities, 8,000. Careers in the healthcare sector are down by 176,000 given that February 2020.

“There’s even now a good deal of pent-up desire for staff,” Julian Richers, the vice president of international economics analysis at Morgan Stanley, informed The Wall Street Journal. “It does make sense that as the economic climate slows, work must slow as well, when we have labored by means of the backlog of labor need.”

Examine much more: Labor Dept: Professional Banking Work opportunities Decline Following COVID

In June, transportation and warehousing added 36,000 positions, with the sector getting 759,000 a lot more jobs than in February 2020. Manufacturing positions went up 29,000, returning the industry to its February 2020 level.

Info extra 25,000, which is 105,000 increased than in February 2020. New positions include things like 9,000 all publishing areas apart from for the online.

Normal hourly earnings amplified by 10 cents, or .3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, to $32.08. More than the earlier 12 months, common hourly earnings have improved by 5.1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

——————————

NEW PYMNTS Details: HOW UTILITIES AND Shopper FINANCE Corporations CAN Increase THE Bill PAYMENTS Experience

About: A lot more than fifty percent of utilities and consumer finance organizations have the capacity to course of action all month-to-month bill payments digitally. The kicker? Just 12{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of them do. The Digital Payments Edge, a PYMNTS and ACI Around the world collaboration, surveyed 207 billing and collections experts at these firms to learn why heading absolutely electronic continues to be elusive.

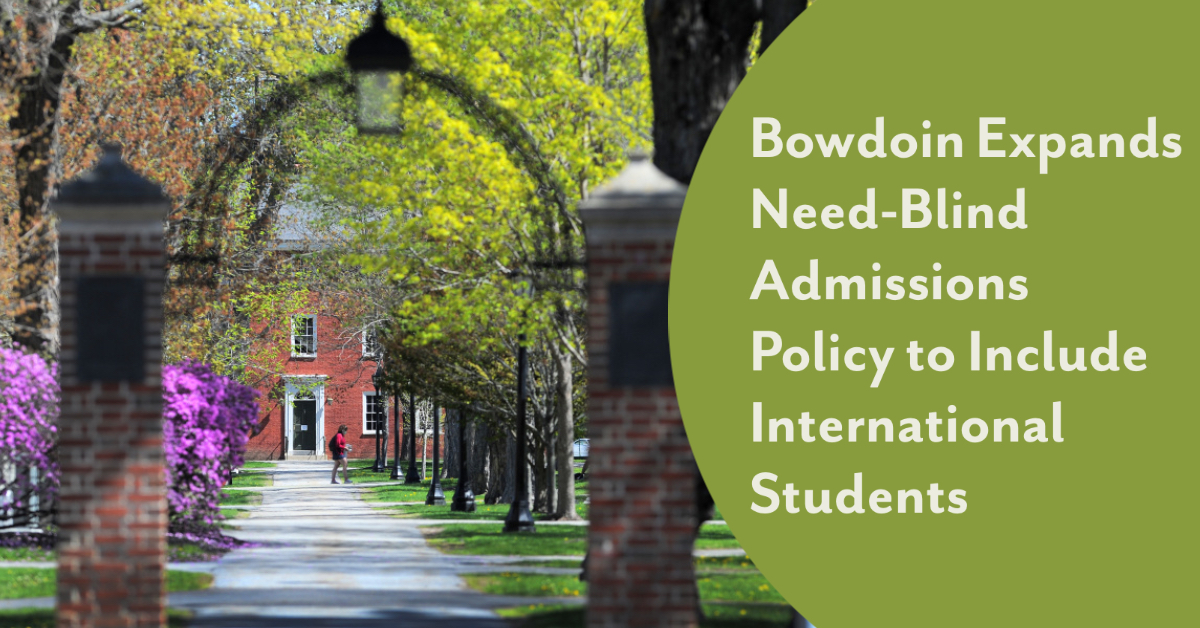
Bowdoin College Expands Need-Blind Admissions Policy to Include International Students

Bowdoin College Expands Need-Blind Admissions Policy to Include International Students

This stage is one of lots of that the College has taken in excess of the earlier 10 years to remove barriers for students, and it will make Bowdoin a person of just seven institutions nationally with detailed need to have-blind assist policies for all students, regardless of citizenship.

“Ensuring entry to a Bowdoin education and learning is central to our mission. This motivation to will need-blind admission for our international applicants is yet another critical component of a impressive plan of entry and affordability that only a number of other colleges and universities are ready to offer,” mentioned Bowdoin College President Clayton Rose.

Bowdoin has prolonged been a chief in eliminating barriers for college students, including adopting the country’s initial exam-optional admissions plan in 1969.

As it seeks to be available to all students, regardless of their monetary instances, the University at present gives pupils with monetary help awards that meet their entire calculated want and has performed so with no loans due to the fact 2008.

Now Bowdoin joins Harvard College, Princeton College, Massachusetts Institute of Technologies, Yale University, Dartmouth College, and Amherst Faculty in which include all pupils, regardless of citizenship, below its need to have-blind admissions coverage.

“It is vital that a good liberal arts instruction like Bowdoin’s be obtainable to college students from all economic backgrounds and all citizenships,” stated Claudia Marroquin, senior vice president and dean of admissions and college student support.

“This latest coverage helps make Bowdoin’s message clear—we welcome the world’s most proficient learners, no matter of qualifications, and we are doing all we can to aid college students from admission to graduation,” Marroquin claimed.

need-blind-twitter.jpg

Our optimum priority is generating a Bowdoin instruction inexpensive for everyone.

  • The software price is routinely waived if you are implementing for assist, or if you are the first in your household to go to college or university.
  • Roughly 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of all Bowdoin learners obtain support.
  • Bowdoin’s pupil support is want-based. This means our scholarship and grant assist is identified based mostly on your individual spouse and children scenario.
  • Bowdoin is want-blind, which signifies that your means to fork out is hardly ever a factor or barrier to admission.
  • Bowdoin meets your entire calculated want employing scholarships, not loans, which under no circumstances have to be paid back again.
  • 22 per cent of all Bowdoin pupils acquire comprehensive aid ($ pupil and $ father or mother contribution).
  • The typical scholarship awarded to all-aided Bowdoin students is $56,397.

Groups back youth financial education

Groups back youth financial education

A few West Michigan corporations are seeking to grow youth economical education and learning possibilities as Michigan turns into the 14th condition in the U.S. to mandate personalized finance at the high school level.

With the mid-June passage of the bipartisan bill HB 5190 — which will insert a 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}-credit score particular finance study course as a high college graduation requirement, starting off with ninth graders in 2024 — corporations like Customers Credit Union and the nonprofits Younger Dollars Finances and Junior Accomplishment of the Michigan Great Lakes are growing their attempts to generate financial training alternatives for youth.

Kalamazoo-based People CU, which has areas across West Michigan, and Grand Rapids-dependent nonprofit Youthful Dollars Funds (YMF) not long ago formed a a few-yr partnership to support YMF’s present youth economical training plans and grow Individuals CU’s involvement in supporting economical literacy for young children.

YMF teaches real-lifestyle cash management to children ages 11-17 across the four pillars of “spend, preserve, share and spend.”

Dondreá Brown, government director of YMF, and Scott Dobson, supervisor of the credit history union’s 15-12 months-aged People @Perform system that gives economical training and wellness principles to people in the workforce, lately spoke to the Company Journal about their partnership.

“Myself and my crew spend all of our time out talking to the workforce, especially youthful adults that are new to the workforce, and we obtain the lack of standard comprehension of how to manage a paycheck is (existing among) about 90{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of individuals young folks,” Dobson reported. “We consider it’s excellent for our point out to start pondering about private finances a lot more youthful, and to get individuals all set for the workforce and fully grasp how to make their paycheck do the job for them, and the before we can begin, the greater off we are.”

Brown mentioned Buyers CU is supporting YMF with sponsorship pounds for a few many years, and the partnership will entail co-branding YMF digital and in-individual curriculum methods and elements bringing YMF pupils to take a look at Buyers CU and Buyers staff members helping to co-aid displays on preserving, investing and budgeting, “to definitely assistance youngsters realize and know that there’s this synergy in between fiscal institutions (and) community businesses as it pertains to serving our youth (and) households relating to monetary education and learning.”

This summer months, YMF is managing a trio of 3-7 days camps in Grand Rapids priced at $25 per pupil — Young Income Administrators and Youthful Business owners ran in the early morning and evening four occasions a week from June 20-July 8, and the Younger Money Investors camp will meet up with 4 moments a 7 days from July 18-Aug. 4.

The resources for the camps had been established to be co-branded with Consumers CU as of press time, and People was on faucet to host just one working day through every of the camps. Basic details about the YMF summer camps is at ymfgr.org/camps.

As part of their partnership, Buyers and YMF claimed they are arranging to present a lot more prospects to instruct teens about dollars in the coming months. 

People also mentioned this tumble it will share access to a range of new economic education content material, like interactive on the net classes, displays, blogs and extra on its web page.

“Our goal would be able to offer that articles to academics so that they can very easily present it to their students,” Dobson claimed.

Consumers’ latest COO and incoming President and CEO Scott Sylvester claimed when youthful men and women understand the basic principles of dollars administration, it generates a foundation for foreseeable future optimistic money determination-creating.

“We are keen to get these worthwhile methods in front of our associates and communities, mainly because we know that when our youth comprehend the principles of money wellness, they are far better prepared for a successful potential,” Sylvester mentioned.

Brown explained he presently is in talks with universities and college systems about what economic schooling YMF can add by leveraging its proprietary, culturally responsive economical instruction curriculum. Up to this place, YMF has partnered with exterior organizations to offer you right after-faculty programming, and this is the 1st time it is engaging universities directly.

He claimed he believes the statewide mandate to train monetary literacy in general public schools will enrich the work YMF has been undertaking for 3 several years.

Dobson explained People has on situation presented faculties and lecturers with one-off monetary literacy articles on an questioned-for basis, but he thinks the partnership with YMF will give the credit score union and schools access to a far more in depth solution.

“We’re psyched to be capable to get this complete suite of items … to the faculties and say, ‘Here, we have good possibilities to make it easy for you to supply genuinely impactful content to your students that they’ll like and, most importantly, will get the job done for them,’” Dobson mentioned. “For us, offering education, we want to do it in a way that performs for the college students so that they can get it and set it into action in their serious life.”

The new monthly bill Whitmer signed into law on June 16 does not incorporate an supplemental half-credit rating requirement, but alternatively will allow college students to substitute just one semester of math, visible arts or foreign language with own finance.

Brown stated he thinks educating personal finance is “similar to instructing a international language,” and he thinks the more youthful you commence, the much easier it is to discover the principles, which is why YMF presents programming for individuals as younger as age 11.

He reported YMF normally attempts to discover ways to reduce the price tag obstacles in financial education and learning, and he thinks this bill will support with that by embedding economical literacy within just community instruction.

“I consider that this is a single of all those payments that would help us just reimagine and start to be real looking about the unique kinds of funds and financial education and learning we could current to our group,” he said. “One factor that we recognize in any money education is there’s not a one particular-sizing-fits-all product. I imagine this allows us to have interaction in some procedures that will enable for conversations about lifestyle, about neighborhood (and) about variety as it pertains to fiscal instruction.

“We are just delighted to be capable to be a element of increasing culturally responsive money education and learning in our community, but additional importantly, with the partnership with Individuals, really getting equipped to leverage our ordeals, our means and our enthusiasm to effect our youth and enable them turn out to be much more empowered by money education and learning.”

Gov. Gretchen Whitmer signing HB 5190, which adds a 50 percent-credit score personalized finance class as a superior university graduation necessity starting in 2024.
Courtesy state of Michigan

Junior Achievement of the Michigan Excellent Lakes (JAMGL) mentioned it was 1 of several advocates for the invoice updating Michigan’s superior university curriculum to contain economical literacy, and the corporation is wanting forward to collaborating in the schooling course of action.

“Junior Accomplishment is energized to husband or wife with spot colleges to convey its confirmed economic literacy curriculum to higher college classrooms throughout the region as portion of this need,” said Monthly bill Coderre, president and CEO. “Sixty {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of learners who were elevated in lessen-cash flow properties but have Junior Accomplishment programming in faculty report that they are in center- to higher-income brackets as grownups because of to the monetary literacy understanding they gained. We are pleased have the assistance of our legislators in bringing this kind of impactful understanding to even additional learners from throughout our condition.”

Just one new prospect JAMGL mentioned it will bring to significant college pupils is the prospect to expend the day in its new facility in the Karl and Susan Hascall JA Finance Park.

The finance park teaches financial independence to eighth- to 12th-quality students. College students shell out 12 classroom sessions getting ready for the encounter, and their day at JA Finance Park entails a randomly assigned career and loved ones circumstance, in which participants will generate a month-to-month funds based on their profits and family predicament.

The new experience will be built available before long to learners and schools from across West Michigan. More info is accessible at michigangreatlakes.ja.org or by contacting (616) 575-9080.