FTC Shuts Down Credit Repair Pyramid Scheme Financial Education Services, Which Bilked More Than $213 Million from Consumers

FTC Shuts Down Credit Repair Pyramid Scheme Financial Education Services, Which Bilked More Than 3 Million from Consumers

The Federal Trade Commission has taken action against Economic Education Providers and its entrepreneurs, Parimal Naik, Michael Toloff, Christopher Toloff and Gerald Thompson, as well as a amount of associated businesses, for scamming individuals out of far more than $213 million.

In response to a complaint submitted by the FTC, a federal court has temporarily shut down the sprawling bogus credit history mend plan. The FTC’s complaint alleges that the corporation preys on customers with lower credit score scores by luring them in with the phony assure of an straightforward take care of and then recruiting them to be part of a pyramid scheme selling the similar worthless credit history repair service expert services to other individuals. 

“These defendants gathered hundreds of thousands in junk charges as element of a pyramid plan that peddled phony credit rating maintenance products and solutions,” reported Samuel Levine, Director of the FTC’s Bureau of Buyer Safety. “We are delighted that the courtroom shut down this procedure and froze its property, and we will go on to pursue companies that prey on families’ economic agony.”

In accordance to the FTC’s criticism, Michigan-dependent Economic Education and learning Expert services, also performing organization as United Wealth Products and services, has operated its scheme since at least 2015. The corporation statements to provide buyers the potential to clear away destructive data from credit rating experiences and improve credit rating scores by hundreds of points, charging as a great deal as $89 for each month for their expert services. Their tactics, in accordance to the grievance, are seldom successful and in numerous occasions damage consumer’s credit rating scores.

The FTC’s investigation identified that the company’s plan combines charging individuals for these worthless credit fix providers with a challenging promote to be part of a pyramid scheme that consists of offering the worthless companies to additional shoppers. The grievance alleges that the company’s techniques violate the FTC Act, the Credit Repair service Organizations Act, and the Telemarketing Income Rule. Especially, the company alleges that the defendants:

  • Deceived shoppers about credit rating repair service: Economical Instruction Services takes advantage of social media, telemarketing, bogus “testimonials, and a network of product sales brokers throughout the place to deceive people, falsely promising in English and Spanish that they can remove damaging information from credit history studies and raise credit scores. The criticism alleges that the enterprise has often basically sent consumers sort letters to mail to credit score bureaus that did not final result in the promised adjustments.
  • Sold ineffective hire payment solutions: The company also sells an extra solution that supposedly sends rent payment facts to credit bureaus, but the complaint notes that this data is not normally part of consumers’ credit score scores and numerous credit bureaus really do not acknowledge this kind of facts straight from shoppers
  • Billed individuals upfront for credit rating fix: The firm expenses individuals upfront for credit score maintenance products and services, which is unlawful. The grievance alleges that consumers are charged $99 upfront, and then spend a recurring every month payment as significant as $89 for the ineffective providers. The corporation also consistently fails to provide shoppers crucial facts expected by legislation, including refund and cancellation guidelines.
  • Operated a pyramid scheme: The business also encourages customers to come to be Financial Schooling Providers “agents” on their own, marketing the company’s companies to other consumers. Agents make outlandish money statements that individuals can make more than $1,000 weekly in the scheme and earn bonuses of tens of thousands of pounds. The complaint also alleges that customers should pay back hundreds of pounds to be part of the plan and pay out for the company’s bogus credit history repair companies every thirty day period, even if they really don’t require them. The compensation composition for the scheme has hallmarks of a pyramid scheme, with escalating degrees of compensation and titles primarily based on the amount of associates recruited, and an emphasis on the worth of recruiting new associates. Few, if any, people make the income promised, and many customers drop revenue as brokers.

The grievance alleges that the organization also illegally applied false data in the method of offering their credit rating maintenance and expenditure prospects to get consumers’ banking and other economic facts.

The Fee vote authorizing the workers to file the grievance and request for temporary restraining get was 4-. The criticism was filed in the U.S. District Court docket for the Japanese District of Michigan.

The FTC appreciates the support of the Georgia Business office of the Legal professional General Purchaser Protection Division in bringing this case.

Notice: The Commission information a complaint when it has “reason to believe” that the named defendants are violating or are about to violate the law and it seems to the Commission that a proceeding is in the public interest. The situation will be made a decision by the court.
Biden can and should target student-loan debt forgiveness

Biden can and should target student-loan debt forgiveness

When it comes to the catastrophe that is our scholar mortgage procedure, some credit card debt forgiveness will certainly be section of the resolution. Millions are in default on their financial loans. Many just cannot afford to pay for to pay. Other borrowers struggle with debts for degrees they did not entire or unsuccessful to direct to a superior job. In a lot of conditions, trying to accumulate on terrible financial loans is not really worth the price to taxpayers or hardship imposed on borrowers. Pupil financial loans should really be a automobile for economic opportunity, not a economic existence sentence.

So the plan challenge is not whether to forgive some credit card debt, but how and for whom. Debt forgiveness could be an possibility to redress failures of the existing program, make higher education financing additional reasonable and equitable, and deliver hope not just for existing borrowers, but also to foreseeable future college students who will borrow to pay back for college or university and graduate university. Tomorrow’s college students require self esteem the federal government has a strategy to help them, much too.

But popular, fast, and one-off debt forgiveness—$10,000 for everybody, no matter of situation, ignoring that college students are heading to borrow yet another $100 billion upcoming year—doesn’t carry out any of those objectives. But a focused, gradual method to personal debt forgiveness could.

1-off, across-the-board forgiveness is capricious and unfair

Widespread personal debt forgiveness is not equitable simply because pupil credit card debt is largely owed by greater-profits, far better-educated debtors, from affluent, typically white backgrounds. Eligibility for federal financial loans is not based mostly on money—virtually all American pupils are eligible—and financial loans can be a effortless and low-cost way to finance tuition or dwelling expenditures even for family members who can “afford to fork out.” As a end result, who owes college student personal debt and how a lot they owe generally reflects who goes to higher education, regardless of whether they complete faculty and go to graduate faculty, and no matter if they show up at an expensive college.

Superior-cash flow families are 6 times a lot more very likely to mail their small children to university as reduced-income households. If you satisfy anyone with a modern graduate degree, far more than 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} grew up in a higher-cash flow family. Black and Hispanic People continue to be woefully underrepresented at each individual level of postsecondary educational attainment and are considerably less possible to complete levels. A lot of student bank loan debtors do very well after college—the wages of younger college or university and expert-degree graduates are at all-time highs. Forgiving debt of affluent, superior-income, properly-educated, mostly white People makes society additional unequal, not significantly less.

1-off, throughout-the-board forgiveness is capricious and unfair in other methods. Why does an Ivy-league experienced-degree graduate deserve the same aid as a student who pursued a low-value group higher education diploma? Why ought to the course of 2022 get a windfall, but not pupils who enroll future year? Why really should a borrower who used years having to pay down a harmony get the similar or a lot less than somebody who graduated yesterday?

Pupils borrow shut to $100 billion just about every calendar year but are eligible to borrow about three situations as considerably, so the precedent issues for how much future students borrow and repay, not to mention how significantly colleges demand. As flawed as the current program is, it can get worse.

In his campaign, President Biden explained an enduring reform that incorporated increased grant aid for low- and middle-money students, funding to minimize tuition at community faculties, and a far more forgiving revenue-pushed compensation (IDR) system. That eyesight expands on our broadly-supported process of Pell grants and guidance for community faculties, but it also reflects some tough truths: There is no situation for taxpayers subsidizing sky-high personal college tuition, small children from significant-earnings family members, or graduate and professional degrees.

Completed very well, financial debt forgiveness could progress that eyesight.

So the coverage problem is not whether to forgive some credit card debt, but how and for whom.

Biden proposed doubling the utmost Pell grant from its recent $6,500 level. He could forgive a equivalent volume of financial debt for present small-income and middle-money borrowers and promise to do so every single year for future minimal-revenue borrowers in scenario Congress does not act on his proposal. Concentrating on support centered on data the Section of Education now maintains from economic aid sorts (like household earnings and Pell eligibility) and no matter if the scholar was an undergraduate is extra expedient than seeking to cap forgiveness based on present earnings. Making use of these measures to concentrate on reduction would be progressive and cost-powerful. Pell grant recipients, following all, characterize 90 per cent of borrowers who default on a college student mortgage. And proposing to offer the similar assist spending for school for equally earlier and foreseeable future students would be coherent and reasonable.

No free faculty approach contemplates cost-free graduate university or backed tuition at high priced faculties or for superior-profits households. Individuals students—past and future—should anticipate to commence repaying their financial loans. Biden’s administration is at present utilizing new IDR options and a clean commence for defaulted debtors, which will ease the load on debtors and speed up personal loan forgiveness Congress enacted. All those procedures will support long run and present borrowers alike. Mortgage repayment need not begin instantly Biden’s new regulatory policies really should be in put very first.

The most effective way to focus on aid to having difficulties borrowers is through IDR plans, which calibrate personal loan repayment to borrowers’ incomes and forgive remaining money owed immediately after 20 or 25 many years. Gaps in university student personal loan debt widen after graduation by race, financial position, and parental education and learning, as well off debtors shell out down their financial loans though other individuals can’t. That will make IDR’s eventual forgiveness hugely targeted to deprived teams and extra progressive than across-the-board reduction.

IDR programs had been enacted too recently and executed so poorly, on the other hand, that pretty much no debtors have nonetheless to obtain forgiveness. Millions a lot more borrowers accumulated desire and charges or defaulted on financial loans in the absence of IDR’s protections. Biden could use personal debt aid to fix that, also, and in carrying out so instill new confidence that these courses will operate for foreseeable future college students. For example, Biden could present relief primarily based on a long time in reimbursement (e.g., forgiving some amount for just about every yr in repayment beyond 10 yrs, so debtors who graduated very long back received the most aid) or forgiving balances in excessive of the unique principal equilibrium (and disposing of gathered desire and expenses) or forgiving remaining money owed of borrowers whose cumulative payments exceeded the quantities they need to have compensated beneath a regular approach. These solutions would be remarkably focused to debtors who have struggled with their loans in excess of quite a few several years, would dispose of financial loans that were unlikely to be compensated in any other case, and could mirror the support that long term debtors could assume from revamped IDR designs. Some borrowers would get significantly less than $10,000 and some would get much more, commensurate with their circumstance. Potential borrowers would have more self confidence the authorities intends to make the IDR method perform for them, as well.

A normal criticism of qualified insurance policies is that they are far too intricate or that the government just can’t be trustworthy to apply them. Individuals criticisms are way too real when it will come to the record of college student lending. By implementing a focused policy quickly and successfully with data the Department of Training currently collects for this objective, Biden can restore belief that the government can get nuanced guidelines proper. People need a pupil lending method to work in the upcoming, to command broad, bipartisan guidance, and be economically sustainable. A specific, coherent, and purposeful mortgage aid coverage could be stage toward that aim.


The Brookings Institution is financed by means of the assist of a numerous array of foundations, organizations, governments, people today, as very well as an endowment. A list of donors can be observed in our yearly reports released online here. The conclusions, interpretations, and conclusions in this report are exclusively all those of its author(s) and are not influenced by any donation.

NJ college graduate pays off $70K in student loans by starting used book business

NJ college graduate pays off K in student loans by starting used book business

NEWYou can now hear to Fox News articles!

When President Biden has floated the plan of canceling “some” pupil bank loan personal debt — an idea both equally GOP and Democrat lawmakers alike are alarmed by, declaring it would price tag the authorities as well a lot cash and incorporate to inflation — some college graduates with hefty debt financial loans aren’t waiting around for a person or a thing to bail them out. 

They are pushing ahead, carrying out what is actually appropriate — and figuring out a way to pay back off their have debt. 

And for 1 Rutgers University graduate, that concerned a novel concept. 

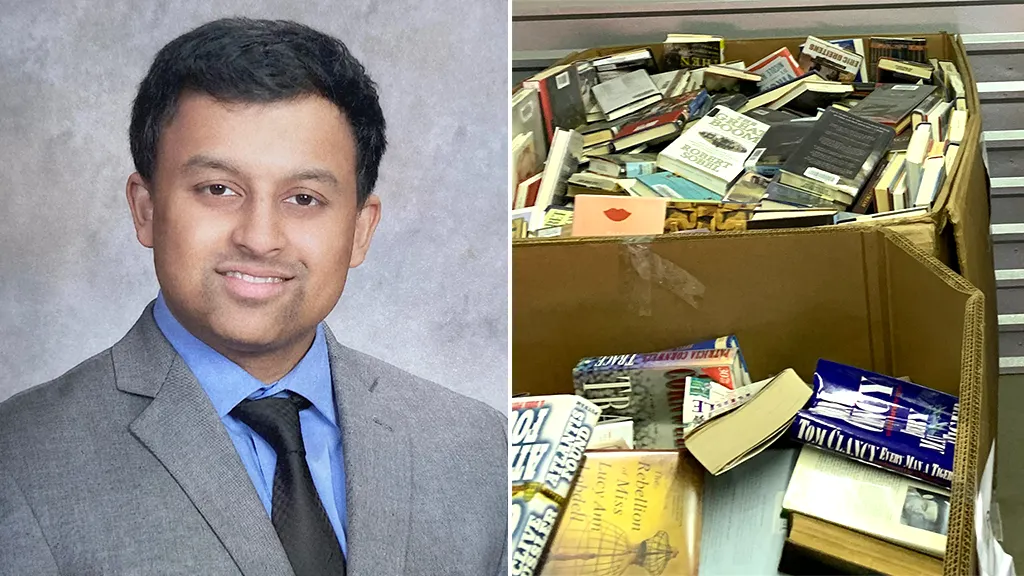
New Jersey native Pathik Oza graduated in 2018 with a B.A. from Rutgers College — he analyzed psychology and biology — with $70,000 in pupil financial loans, he told Fox Information Digital in an job interview.

OHIO Few, Moms and dads OF TWO, GET Large Scholar Mortgage Credit card debt Guiding THEM

And even though Oza began pursuing one more diploma ahead of his approach to go to health care school, he also identified a passion for rehoming made use of and discarded guides.

“I was strolling around one working day throughout the summer months, and I observed textbooks lying there, and I assumed there would be an option,” he said. 

O3 Books founder Pathik Oza of North Brunswick, N.J., during a recent Zoom interview with Fox News Digital about paying down his student debt. "I just started this volunteer work where I would collect unwanted books," he said. 

O3 Textbooks founder Pathik Oza of North Brunswick, N.J., in the course of a new Zoom interview with Fox Information Electronic about having to pay down his scholar credit card debt. “I just started off this volunteer do the job where by I would acquire undesired guides,” he claimed. 
(Fox Information Electronic)

“Why would textbooks be thrown absent? They could be redistributed to someone who may well want them. So I just started off this volunteer perform exactly where I would gather undesired publications,” he told Fox Information Digital.

What commenced as a variety gesture and a prospect to give back to area libraries, schools, shelters and children’s hospitals turned into a sparkling new enterprise possibility. 

An expanding range of requests for publications and a significant need for his providers grew to become a little something significantly too substantial for just Oza and his Toyota RAV4 to deal with. 

Pathik Oza designed the selection to flip reselling books into a successful business enterprise.

So Oza built the decision to change reselling publications into a enterprise. He commenced off by opening an Amazon account. 

He termed his enterprise O3 Guides.

FLORIDA-Primarily based Mom PAYS OFF $40K IN Student Debt Immediately after Dwelling ‘PAYCHECK TO PAYCHECK’

“The gain would maintain coming in, and it stored rising,” he said. “[In about] a month or so, I experienced all around 1,000 to 2,000 textbooks in Amazon warehouses. So it was rather awesome to see the expansion in the organization.”

Oza ongoing to develop by launching a web page and opening an Etsy shop, which “blew up” when the planet was locked down for the duration of the coronavirus pandemic. 

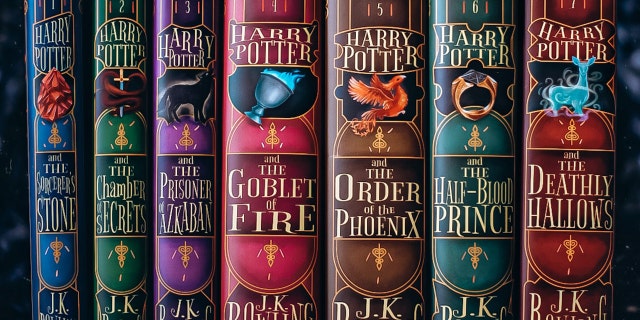
O3 Books' original dust jacket designs for J.K. Rowling's "Harry Potter" book series are shown here. (Pathik Oza/O3 Books)

O3 Books’ unique dust jacket models for J.K. Rowling’s “Harry Potter” book series are proven here. (Pathik Oza/O3 Guides)

He also identified that there was especially superior demand for his décor e-book sets and redesigned dust jackets he moved in that course to assistance spruce up the backgrounds of function-from-dwelling Zoom meetings.

By the end of 2020, Oza had created $115,000 from his facet enterprise — which lined his scholar financial loans in complete, and then some.

Oza figured out “a ton about finances,” he reported, by paying out off his loans and by fueling his very own smaller enterprise at the similar time.

Oza claimed he learned “a great deal about finances” by spending off his financial loans and by fueling his personal business at the similar time.

OHIO Author Paid out OFF $48K IN Scholar Financial loans IN 14 MONTHS: IT WAS ‘AN ADVENTURE’

Today, the 25-12 months-outdated stated he would truly feel “more cozy” getting on different sorts of borrowing in the potential centered on the economical know-how he’s accrued.

The achievements of O3 Books is now having to pay for Oza’s next diploma in total, doing away with the burden of needing to get out another personal loan. 

Pathik Oza of N.J. started O3 Books — and used the money he made from his new business to completely pay off his student loan debt. 

Pathik Oza of N.J. began O3 Guides — and utilised the funds he created from his new business to wholly shell out off his pupil personal loan credit card debt. 
(Pathik Oza)

The modest business enterprise proprietor has considering the fact that switched career paths. 

He is been pursuing a degree in personal computer science, though the assumed of hefty med school financial loans maybe in his long run gave him an further raise to consider treatment of debt he previously had.

“I felt it was urgent to pay people off,” he mentioned.

HOW TO Come to a decision WHICH Pupil Financial loans TO Fork out OFF Initial

For other pupils with personal debt who are seeking for a way to pay down their loans, Oza mentioned weighing the alternative of starting a little enterprise is a fantastic thought. He particularly encouraged using gain of on-line marketplaces like Amazon and Etsy.

“Any enthusiasm you’ve started off, there is undoubtedly a industry for it,” he said.

“You only will need a compact part [of the population] to [help] produce income in product sales. As extensive as you have 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the buyers, you have a whole-fledged business,” he included. “There is generally a market for anything.”

Expanding his own small business has supplied Oza a boost in terms of monetary literacy, so he also suggested that saving and investing one’s money is usually the “very best option.”

ROWE: Idea OF CANCELING Pupil Financial loan Personal debt ‘MAKES ME CRAZY’

“Make positive to understand finances and how you can greatest allocate your income,” he explained. “Loans are a stress no one would like — but you will get rid of them.”

O3 Books founder Pathik Oza shared ideas for other students with debt to pay down their loans. "Social media has opened up many opportunities to market your skills and allow you to create a side or potentially full-time income," he said.

O3 Textbooks founder Pathik Oza shared concepts for other pupils with debt to pay out down their loans. “Social media has opened up numerous prospects to industry your skills and make it possible for you to develop a side or possibly full-time revenue,” he mentioned.
(Pathik Oza)

Oza hopes one day to depart O3 Publications with his parents — as a continual outlet for supplemental money. In other terms, he desires it to keep in the family.

“This is an incredible side money I’ll keep endlessly,” he reported. “I built a model all over it. I developed a neighborhood close to it. So, it’s a little something I simply cannot allow go.”

“There is a market for your talent and there are numerous platforms you can use to showcase your skill.”

Oza also shared added tips for any individual needing excess earnings or cash to pay out down their scholar personal debt.

“I would suggest obtaining a section-time task — and if you do not have that much time, then use all those accessible several hours to make funds with a ability you have,” he mentioned. 

Click on Below TO Sign UP FOR OUR Lifestyle Publication 

“It could be nearly anything like advertising and marketing, art, world wide web design and style, application improvement or training … There is a industry for your expertise and there are a lot of platforms you can use to showcase your ability.”

“For example,” he added, “Instagram is an superb place for artists to showcase their artwork … The greatest section about this is you can operate when you are accessible.” 

Click on In this article TO GET THE FOX Information Application

Claimed Oza, “Social media has opened up quite a few possibilities to current market your expertise and allow you to create a facet or probably total-time revenue from a passion or talent you have. Once again, if your circumstance lets you to do this, consider to decrease your investing charges as substantially as achievable.”

Wall Street’s Losing Streak Ends, but Uncertainty That Drove It Lingers

Wall Street’s Losing Streak Ends, but Uncertainty That Drove It Lingers

The inventory market’s staggering operate of losses came to an conclusion final week, with the S&P 500 snapping a seven-7 days shedding streak and pulling away from the brink of a bear sector with a 6.6 p.c bounce via Friday.

But the considerations that drove Wall Street’s stress this year stay unresolved. It is significantly way too quickly to know if skyrocketing shopper costs have peaked, if the Federal Reserve has charted the suitable path for curiosity prices, or how well the overall economy will be in a position to hold up in the experience of quickly inflation and increasing borrowing expenses.

Till there’s clarity on these concerns, analysts say, it would be a mistake to presume that this year’s fall in stocks was above. As share price ranges have tumbled, slipping about 13 per cent considering that early January, predictions that the selling has operate its class have regularly turned out to be mistaken, with the marketplace switching route as every new piece of knowledge on the economy came in. Last week’s bounce, as buyers plowed some $20 billion into global inventory funds, could be one more shorter-lived rally.

“There’s no certainty, especially in the brief term,” claimed Victoria Greene, main expense officer at G Squared Non-public Wealth, an investment decision adviser. “This could be a choppy summer months in which you are heading to have ups and downs and you’re likely to get jerked all over.”

The current gains had been underpinned by some great news about the well being of American shoppers. Various stores, such as Macy’s and Nordstrom, documented superior-than-anticipated quarterly final results, expressing buyers are keen to trade up on their buys as they get started to journey once again and return to places of work. On Friday, info from the government showed that Us citizens continued to invest in April, tapping into their savings to do so even as they contended with increased fees.

Just a week before, stories from two retail giants — Walmart and Goal — experienced induced the specific opposite response, increasing alarms that some shoppers experienced reached their limit and that inflation was starting up to hit company income, also. That concern assisted press the S&P 500 to its seventh consecutive weekly decline, the longest extend of declines considering the fact that 2001 after the dot-com bubble burst.

The blended stories discuss to the way inflation is impacting the inhabitants in another way, economists say, with decrease-profits Americans transforming their habits as a end result. But they also level to 1 of the major troubles investors have faced as they’ve experimented with to adjust expectations: a continuously shifting photo in which debates seem to be to be settled a single day only to be resurrected the upcoming.

Not prolonged back, the market’s rally was relentless, lifting shares of technological know-how giants like Apple, which in January was briefly truly worth $3 trillion, the 1st enterprise at any time to achieve that lofty point. Even as the pandemic raged, the S&P 500 was pulled from one history to the following, increasing 90 percent over three many years as a result of 2021.

Those ended up gains fueled by in close proximity to-zero curiosity rates, slashed to that degree by the Fed in March 2020. The very same insurance policies, as very well as governing administration stimulus paying out, contributed to a increase in consumer need for all the things from cars to electronics that assisted ignite the inflation difficulty spooking investors today.

With shopper rates increasing at their swiftest speed in 40 several years, the Fed has abruptly changed study course, raising curiosity costs in March for the 1st time due to the fact the pandemic began in an effort to cool the financial state. Russia’s invasion of Ukraine and new Covid-19 lockdowns in China also lifted dangers to advancement, the source of foods and energy, and the selling prices of items in typical.

All of these things have led economists to slash their anticipations for financial advancement in the United States. A survey from the Nationwide Affiliation for Small business Economics confirmed that forecasters assume gross domestic product or service to increase 1.8 percent in the fourth quarter from a yr previously, down from their prediction in February of 2.9 per cent.

Now, traders anticipate the Fed to elevate its benchmark borrowing fee to as higher as 2 percent by July, a large bounce but by no signifies the very last increase expected this yr. In addition to being a drag on the economy, the greater borrowing costs signify investors have been compelled to rethink what they are eager to pay out for shares or other dangerous investments — and the optimum fliers had been strike toughest.

“The world is repricing for the end of extraordinarily minimal fascination costs and terribly accommodative monetary plan,” claimed David Lefkowitz, head of equities for the Americas at UBS Worldwide Wealth Management. “The losses feel a great deal additional unpleasant than the pleasure we been given from looking at the gains.”

All the marketing could also have an effects on the actual financial state, as retirement nest eggs, college price savings accounts or rainy-working day money drop value and main executives turn into significantly less willing to just take challenges.

“A ton of prosperity has been wrecked in the very last five months,” reported Russ Koesterich, portfolio manager of the BlackRock World-wide Allocation Fund. “That has an impact on company sentiment and hiring and investing options by organizations. It also has an result on purchaser actions.”

For now, the stock marketplace has narrowly avoided falling into a bear market, generally defined as a 20 per cent drop from a modern superior that signifies a significant downturn in sentiment about the market place and the financial system.

It arrived near on May 20, even though, briefly falling into that stage right before rallying by the finish of buying and selling. Right after very last week’s bounce, the S&P 500 is 13.3 percent below its Jan. 3 history — significantly from bear market place territory.

But there are other ways to evaluate unease amongst traders. 1 of them is that massive swings in inventory rates are coming a lot more usually these days. Even if it is much easier to abdomen than a fall, previous week’s obtain was aspect of this volatility.

“This is volatility, way too,” Steve Sosnick, a trader and chief strategist at Interactive Brokers, reported of the week’s acquire. “This is what I like to connect with socially acceptable volatility.”

There will be a clearer turning point, Mr. Sosnick claimed, when traders choose the Fed is finished raising charges.

“The Fed does not essentially have to be finished — people just have to perceive they will be completed,” he said. Realizing when that will come about, however, is impossible at this issue.

How to Avoid Fraudulent Transactions in Your Online Business: Tips and Tricks

How to Avoid Fraudulent Transactions in Your Online Business: Tips and Tricks

Jogging an on the internet business can be a quite valuable venture, but it can also be fairly risky. 1 of the most important risks that you deal with is fraud. Fraudulent transactions can value your small business a large amount of funds, and they can also destruction your status. Just experts will also discuss about defending your self from frauds and malware. Let’s get commenced!


There are a number of factors that you can do to defend your on the net company from fraud. The initially issue is picking a reliable payment gateway with a superior reputation. You should also assure that your internet site is safe and that you have a excellent anti-virus system in place. A further crucial tip is never to give out your monetary details to any individual. If you are ever questioned for your credit rating card number or lender account amount, you really should quickly report it to the authorities.

One more way to guard your online business is to teach your self about the different kinds of fraud that are out there. Numerous cons goal firms, so it is vital to be conscious of them. Just one common rip-off is phishing. When somebody sends you an electronic mail that seems like it is from a reputable enterprise, but it’s in fact from a fraudster. They will test to get you to simply click on a backlink or open up an attachment that incorporates malware. A different widespread form of fraud is id theft. This is where a person steals your private data and employs it to make purchases or utilize for credit score in your identify.

If you are ever the sufferer of fraud, it is important to act rapidly. The faster you report it, the easier it will be to capture the culprit and get your cash again. You ought to also change all of your passwords and make certain that your internet site is secure. Fraud can be a extremely highly-priced mistake, but you can stay away from it if you are mindful and take the necessary safeguards. Many thanks for examining! We hope this short article has been beneficial.

All Your On the net Transactions Are at Danger

Fraudulent or Not?

You might consider that as extended as you are mindful about who you do small business with on the net, your transactions are safe and sound from fraud. Sad to say, which is not constantly the case. Fraud can occur to any person, even if you’re remaining pretty careful. Which is why it’s important to know what to do if it transpires to you.

Here are some guidelines on how to keep away from fraud in your online transactions:

  • Be watchful who you do company with. If you are not confident about a organization, do some analysis in advance of handing above any cash.
  • Check out out testimonials from other consumers. If one thing does not appear suitable, it likely isn’t.
  • Use a credit score card alternatively of a debit card. Credit history cards have additional protections in position in circumstance of fraud.
  • Continue to keep an eye on your account statements and report any suspicious action ideal absent.

If you do locate yourself the target of fraud, really do not worry. You can get steps to correct the problem and get your dollars again. The most crucial thing is to act rapidly. The faster you report the fraud, the easier it will be to take care of it.

Thanks for studying! We hope this report has been beneficial. Fraudulent transactions are a serious challenge, but you can steer clear of them if you’re careful and know what to glimpse out for.

Orange Business Services leverages AI for IT

Orange Business Services leverages AI for IT

Watcher operates with other IT support applications, makes use of predictive examination and a one dashboard to head off IT problems at the go

Orange Organization Expert services announced Tuesday the start of Provider Take care of-Observe. The new remedy, aimed at organization IT departments, displays community companies and purposes and takes advantage of synthetic intelligence (AI) for predictive analysis to watch potential complications.

Assistance Deal with-Watch (or Look at for limited) was developed to answer business demands to observe interconnected IT solutions, mentioned the firm.

“Monitoring and measuring, even so, are more and more elaborate as IT estates increase, likely ensuing in deficiency of world wide visibility to establish root will cause of concerns or recurring glitches, incapacity to foresee incidents, and lousy inform administration. Common checking tools consider a siloed technique dependent on one software for each assistance, proving insufficient for today’s dispersed infrastructure,” reported Orange Business Providers.

Check out supplies companies with holistic checking capabilities grouped into a single dashboard for effortless administration, in accordance to Orange Business Services. Monitoring resources harvest info into a staging place — an Orange-hosted details lake — the place the AI does assessment and generates predictive alerts.

View addresses the entire company IT ecosystem, according to the firm. It interfaces with other IT support management computer software to manage the provisioning and lifecycle of IT expert services.

“It handles the total Orange portfolio and can also combine any shopper-owned monitoring instrument. Furthermore, Orange Small business Solutions consulting groups can further assistance clients in their AIOps journeys,” stated Orange Company Expert services.

On Monday, Orange Business Providers introduced that Enovacom, its health care subsidiary, has agreed to acquire French telemedicine participant Exelus. The offer is topic to customary closing conditions. The firms did not disclose phrases.

Exelus’ Nomadeec system was the attract, in accordance to Orange. Nomadeec remotely connects people with health care pros and crisis connect with centers, to empower distant consultations and assessments. 

Nomadeec already promises use by one-quarter of France’s Providers d’Aide Médicale Urgente, or SAMUs — crisis health care service (EMS) organizations. A lot more than 200 wellness and social treatment facilities, and more than 150 ambulance organizations now use Nomadeec.

The enterprise suggests the acquisition will help it speed up Nomadeec’s progress inside and outdoors of France. The corporation sees the acquisition as component of a bigger option for digital transformation.

“Enovacom can leverage its critical and unique capabilities in the telemedicine market in just the more substantial locations of networks, 5G, IoT, interoperability, and information protection. This acquisition reinforces Orange Small business Services’ strategic positioning as a trustworthy husband or wife for digital transformation in the spot of e-overall health,” mentioned Orange Business Companies.

Orange’s “cloud-concentrated evolution”

The release of Observe and the Exelus acquisition reinforce Orange Small business Services’ ongoing cloud-focused evolution. Encouraging customers make that electronic transformation was major of head in March when Orange Organization Providers announced ideas to add Fortinet’s Secure Obtain Company Edge (SASE) security portfolio into its telco cloud infrastructure.

The Fortinet addition is aimed at Orange Small business Companies enterprise customers who have to have to offer you “work from anywhere” adaptability which employs zero-rely on community access (ZTNA) and firewall-as-a-service, no matter of the place they physically are found.

Anne-Marie Thiollet, Orange Enterprise Services’ EVP, World Options, mentioned in a assertion the Fortinet addition would assist Orange “enable our prospects to quickly adopt a cloud-native natural environment that is increasingly vital for companies globally.” 

In April, Orange Business enterprise Services announced that it had helped international producing business Siemens AG to migrate to a global Software-Outlined Extensive Region Network (SD-WAN), one of the most significant non-retail SD-WAN deployments outside of retail.

John Isch, director, Connectivity Remedies for the Americas at Orange Enterprise Companies named the changeover “a most effective-situation scenario when we do the job with our buyers.”

The firm labored with Siemens to migrate applications, solutions, and workflows to the cloud, radically reworking Siemens’ network targeted traffic administration in the process.