What the Fed’s fourth 0.75 percentage point rate hikes means for you

What the Fed’s fourth 0.75 percentage point rate hikes means for you

Here's what the Fed's interest rate hike means for you

The Federal Reserve raised the target federal funds rate by 0.75 percentage point for the fourth time in a row on Wednesday, marking an unprecedented pace of rate hikes.

The U.S. central bank has raised the benchmark short-term borrowing rate a total of six times this year, including 75 basis point increases in June, July and September, in an effort to cool down inflation, which is still near 40-year highs and causing most consumers to feel increasingly cash strapped. A basis point is equal to 0.01 of a percentage point.

A policy statement after the announcement noted that the Fed is considering the “cumulative” impact of its hikes so far when determining future rate increases. Economists are hoping this signals plans to “step-down” the pace of increases going forward, which could mean a half point hike at the December meeting and then a few smaller raises in 2023. Still, stocks tumbled after Federal Reserve Chair Jerome Powell said there were more rate hikes ahead.

“Americans are under greater financial strain, there’s no question,” said Chester Spatt, professor of finance at Carnegie Mellon University’s Tepper School of Business and former chief economist of the Securities and Exchange Commission.

More from Personal Finance:
How Fed’s interest rate hikes made borrowing costlier
Tips to help stretch your paycheck amid high inflation
‘Ugly times’ are pushing record annuity sales

However, “as the Fed tightens, this also has adverse effects on everyday Americans,” he added.

What the federal funds rate means to you

Inflation hit a new high since 1981. What is inflation and what causes it?

“Unfortunately, the economy will slow much faster than inflation, so we’ll feel the pain well before we see any gain,” said Greg McBride, Bankrate.com’s chief financial analyst.

Already, “mortgage rates have rocketed to 16-year highs, home equity lines of credit are the highest in 14 years, and car loan rates are at 11-year highs,” he said.

How higher rates affect borrowers

• Mortgage rates are already higher. Even though 15-year and 30-year mortgage rates are fixed and tied to Treasury yields and the economy, anyone shopping for a home has lost considerable purchasing power, in part because of inflation and the Fed’s policy moves.

Along with the central bank’s vow to stay tough on inflation, the average interest rate on the 30-year fixed-rate mortgage hit 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, up from below 4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} back in March.

On a $300,000 loan, a 30-year, fixed-rate mortgage at December’s rate of 3.11{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} would have meant a monthly payment of about $1,283. Today’s rate of 7.08{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} brings the monthly payment to $2,012. That’s an extra $729 a month or $8,748 more a year, and $262,440 more over the lifetime of the loan, according to LendingTree.

The increase in mortgage rates since the start of 2022 has the same impact on affordability as a 35{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} increase in home prices, according to McBride’s analysis. “If you had been approved for a $300,000 mortgage in the beginning of the year, that’s the equivalent of less than $200,000 today.”

For home buyers, “adjustable-rate mortgages may continue to be more popular among consumers seeking lower monthly payments in the short term,” said Michele Raneri, vice president of U.S. research and consulting at TransUnion. “And consumers looking to tap into available home equity may continue to look towards HELOCs,” she added, rather than refinancing.

Yet adjustable-rate mortgages and home equity lines of credit are pegged to the prime rate, so those will also increase. Most ARMs adjust once a year, but a HELOC adjusts right away. Already, the average rate for a HELOC is up to 7.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} from 4.24{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} earlier in the year.

• Credit card rates are rising. Since most credit cards have a variable rate, there’s a direct connection to the Fed’s benchmark. As the federal funds rate rises, the prime rate does as well, and your credit card rate follows suit within one or two billing cycles.

That means anyone who carries a balance on their credit card will soon have to shell out even more just to cover the interest charges. “This latest interest rate hike will most acutely impact those consumers who do not pay off their credit card balances in full through higher minimum monthly payments,” Raneri said.

Because of this rate hike, consumers with credit card debt will spend an additional $5.1 billion on interest, according to an analysis by WalletHub. Factoring in the rate hikes from March, May, June, July, September and November, credit card users will wind up paying around $25.6 billion more in 2022 than they would have otherwise, WalletHub found.

Already credit card rates are near 19{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, up from 16.34{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in March. “That’s the highest since the Fed began tracking in 1994 and is more than a full percentage point higher than the previous record set back in 2019,” according to Matt Schulz, chief credit analyst at LendingTree. And rates are only going to continue to rise, he said. “We’ve still got a ways to go before those rates hit their peak.”

The best thing you can do now is pay down high-cost debt — “0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} balance transfer credit cards are still widely available, especially for those with good credit, and can help you avoid accruing interest on the transferred balance for up to 21 months,” Schulz said.

“That can be an absolute godsend for folks struggling with card debt,” he added.

Otherwise, consolidate and pay off high-interest credit cards with a lower-interest home equity loan or personal loan, Schulz advised.

• Auto loans are more expensive. Even though auto loans are fixed, payments are getting bigger because the price for all cars is rising along with the interest rates on new loans, so if you are planning to buy a car, you’ll pay more in the months ahead.

The average interest rate on a five-year new car loan is currently 5.63{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, up from 3.86{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} at the beginning of the year and could surpass 6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} with the central bank’s next moves, although consumers with higher credit scores may be able to secure better loan terms.

Paying an annual percentage rate of 6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} instead of 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} would cost consumers $1,348 more in interest over the course of a $40,000, 72-month car loan, according to data from Edmunds.

Still, it’s not the interest rate but the sticker price of the vehicle that’s causing an affordability problem, McBride said. “Rising rates doesn’t help, certainly.”

• Student loans vary by type. Federal student loan rates are also fixed, so most borrowers won’t be affected immediately. But if you are about to borrow money for college, the interest rate on federal student loans taken out for the 2022-2023 academic year are up to 4.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, from 3.73{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} last year and 2.75{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in 2020-2021.

If you have a private loan, those loans may be fixed or have a variable rate tied to the Libor, prime or T-bill rates, which means that as the Fed raises rates, borrowers will likely pay more in interest, although how much more will vary by the benchmark.

Currently, average private student loan fixed rates can range from 3.22{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 14.96{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, and from 2.52{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 12.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for variable rates, according to Bankrate. As with auto loans, they vary widely based on your credit score.

Of course, anyone with existing education debt should see where they stand with federal student loan forgiveness.

How higher rates affect savers

• Only some savings account rates are higher. The silver lining is that the interest rates on savings accounts are finally higher after several consecutive rate hikes.

While the Fed has no direct influence on deposit rates, they tend to be correlated to changes in the target federal funds rate, and the savings account rates at some of the largest retail banks, which have been near rock bottom during most of the Covid-19 pandemic, are currently up to 0.21{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, on average.

Thanks, in part, to lower overhead expenses, top-yielding online savings account rates are as high as 3.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, according to Bankrate, much higher than the average rate from a traditional, brick-and-mortar bank.

“Savers are seeing the best yields since 2009 — if they’re willing to shop around,” McBride said. Still, because the inflation rate is now higher than all of these rates, any money in savings loses purchasing power over time. 

Now is the time to boost that emergency savings, McBride advised. “Not only will you be rewarded with higher rates but also nothing helps you sleep better at night than knowing you have some money tucked away just in case.”

“More broadly, it makes sense to be more cautious,” Spatt added. “Recognize that employment is maybe less secure. It’s reasonable to expect we’ll see unemployment going up, but how much remains to be seen.”
Subscribe to CNBC on YouTube.

OceanaGold turns to Orange Business Services to manage transformation to SD-WAN, Access Evolution

OceanaGold turns to Orange Business Services to manage transformation to SD-WAN, Access Evolution
    &#13

  • Versatile SD-WAN by Orange simplifies operations, decreases expenditures and permits inside sources to aim on core business
  • &#13

  • Optimised infrastructure delivers far better person experience with improved overall performance and agility
  • &#13

Orange Organization Products and services has sent a Managed Adaptable SD-WAN and provider to mining corporation OceanaGold globally. The optimised infrastructure supports new bandwidth-hungry programs within just its collaboration applications while simplifying the company’s IT management pursuits and cutting down expenses.

This method allows OceanaGold to choose advantage of the capabilities of Adaptable SD-WAN, such as dynamic visitors routing and bandwidth allocation, to supply an enhanced user knowledge for 2,000 in addition personnel. At the same time, the mining business can allocate inside resources away from WAN administration to company-generating projects across its territories in Asia Pacific and North The us.

A Managed assistance eliminates complexity for OceanaGold by enabling Orange Company Services to be one stage of get hold of for products and services and technologies, as nicely as centralised billing.

With OceanaGold hosting a lot more and more of its programs in the cloud as element of its digital transformation, it also essential a secure and flexible way to link to the world wide web. Versatile SD-WAN has authorized it to go away from MPLS to net-centered application accessibility, lessening overhead prices and expanding community efficiency. It is also proving a option to the skills lack, allowing the multinational to superior approach for capacity and growth.

“Through partnering with a managed providers company, we accomplished our vital objectives of gaining bigger adaptability and improving the overall performance of our network to enhance world connectivity during the organisation. Adaptable SD-WAN has enabled us to do this, and we glance ahead to further more collaboration with Orange as we accelerate our electronic transformation,” spelled out Steve VandenBerg, Head of Electronic Technological innovation at OceanaGold.

“We are delighted that OceanaGold’s Flexible SD-WAN roll out has supplied them with the sought after blend of price tag optimisation and bandwidth they were on the lookout for. It has helped reshape their eyesight of us from a pure telecommunications seller to a trusted digital expert services partner. The new system was co-built with OceanaGold’s group, from the answer style and design period to the deployment to generate a favourable impression for their enterprise,” commented Andrew Borthwick, Managing Director for Orange Organization Companies ANZ.

To locate out additional about electronic transformation in the mining marketplace, Orange Enterprise Companies will be talking at the International Mining and Assets Convention (IMARC) on 2- 4 November at the ICC Sydney.

Set up student for success with financial literacy education

Set up student for success with financial literacy education

Do you know the electric power of financial literacy? With Financial Literacy we can modify generational poverty, reinforce people, increase innovation, and make our communities extra secure.

Final thirty day period I shared the stage with fellow previous Bronco and Tremendous Bowl winner, Rod Smith. We went significantly outside of speaking about the new football period or the Broncos’ new quarterback and our most loved memories as players. We are on a greater crew now, one to encourage economical literacy in our communities.

We had an outstanding dialogue all over the have to have for money literacy and economic education, the personal lessons we have learned about generating sensible revenue choices, obtaining coaches (off the field) to mentor us, and what we hope for upcoming generations.

As Coloradans we have entrepreneurial spirit, innovation, epic sporting activities enthusiasts, and endless alternatives to accomplish our desires. For these explanations Colorado turned property for Rod and me all through and after our time as Broncos. However, in spite of Colorado’s entrepreneurial atmosphere, there are now no statewide graduation prerequisites for Colorado schools to give personalized finance or economic schooling classes. In point, only about 25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of faculty districts in the condition include personal finance in their authorized graduation qualifications. We will need to do far better for Colorado’s upcoming.

Economic Schooling Thirty day period, every Oct, just concluded and we have a golden opportunity to prioritize educating these important life capabilities — year ‘round.

The median credit history-card financial debt among the Coloradans is fourth optimum in the country and the point out was given a “C” in economic schooling by Champlain College’s Middle for Economic Literacy, which graded all 50 states on their efforts to develop fiscally literate substantial university graduates. We want to assist foreseeable future generations be prepared for key daily life choices they will deal with, how to help you save for the potential, and support the up coming technology.

When Rod and I sat on phase, in a fireside chat model at Economic Literacy Colorado’s fall fundraiser, we urged the viewers to equip our youthful persons with lifetime competencies that will set them up for accomplishment. Some of our vital takeaways consist of:

  1. Chase your goals but choose it slow. One of the most difficult factors to do as an grownup is help save cash. As two soccer stars who began building a lot of revenue at a speedy rate, we had been tempted to make significant-ticket purchases, as was the customized of our friends. But clever folks instructed us: help save 40{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of your revenue, and when it comes to a order, wait.
  2. Educate youth by taking them with you. Mentoring would make all the variance to a youthful individual. Bring them together with you on a enterprise offer, sit them upcoming to you on Zoom as you negotiate, and show them what you carry to the desk. This lights the route for them to do the same.
  3. We really don’t know what we don’t know. Faculty is where by you go to understand and acquire important lifestyle capabilities. We require our education and learning method to action up and provide our children with personal finance and financial instruction to established them up for long term accomplishment.

Before Rod and I had our time to communicate, we read from an unbelievably inspiring younger lady, Trinity Scales, a senior at the Denver University of the Arts. She needs to be a singer and songwriter and I have no question that she can accomplish nearly anything she sets her mind to.

Trinity just lately attended Financial Literacy Colorado’s Invest In Women summertime symposium to meet up with gals in the business enterprise and economic marketplace. She spoke about how meeting these inspirational women of all ages showed her that she has other options and profession paths she can choose to be prosperous in lifestyle as well. Trinity signifies our upcoming. We discover that no subject their background, youthful men and women in our point out are keen and ambitious to master far more about the instruments they have to achieve monetary independence. If we can increase obtain to academic programs, we will change our future generation’s good results.

Be part of me and Rod, and Financial Literacy Colorado in advocating for learners like Trinity. You can do so by:

  • Inquiring if your child’s faculty teaches own finance or economics.
  • Inquiring about the private finance and economics needs at your child’s faculty.
  • Championing financial and personal finance education and learning when talking to others.
  • Mentoring youth and discovering a seat for them at the desk.
  • Urging your legislators to make financial and private finance training graduation demands in educational institutions.

Colorado is the property of so lots of effective business owners and enterprise leaders. Let us make certain our youth are given the opportunity to study and develop into smart people, geared up and effective industry experts, all with monetary empowerment for several years to come.


Kevin O’Leary’s 5 Best Tips for Starting a Business

Kevin O’Leary’s 5 Best Tips for Starting a Business
A person flips through papers at a home desk with a phone and laptop.

Graphic supply: Getty Visuals

Aim on these factors to be prosperous in business enterprise.


Essential factors

  • Shark Tank investor Kevin O’Leary, aka Mr. Superb, has grown his net really worth to $400 million by adhering to significant investment decision concepts.
  • 1 is discovering how to lower your losses so you really don’t reduce even additional money.
  • By understanding when to pull the plug, you can protect your money and concentrate on investing in your profitable enterprises.

As the star of CBC’s Dragons’ Den and ABC’s Shark Tank, Kevin O’Leary has acquired a reputation as a hard but honest judge of enterprise proposals. He is also a productive entrepreneur in his individual right, with passions in all the things from program and wine to mutual funds and hockey. In other phrases, he understands a issue or two about what it normally takes to commence and mature a successful business enterprise. Listed here are 5 of his best guidelines for everyone hunting to do the exact same.

1. Do your homework

“Revenue may well go to poor people but it never goes to terrible thoughts,” says O’Leary. This signifies accomplishing your due diligence. You have to know everything about the sector, the possibility, the aggressive landscape, and your team. “If you’re talking about one thing like a incredibly hot sauce, or a food stuff item in which the means to get shelf place is pretty much zero — that’s not really appealing for me. I tend to be targeted on the products, the company, the current market and of program, the persons. But proper out of the gate if it can be an overly aggressive house: that’s a big detrimental.”

This usually means taking the time to truly have an understanding of your market within and out, determining probable threats and chances, and developing a powerful foundation you can insert to as your company grows. Know what operates and doesn’t function, and be prepared to transfer on.

2. Be frugal

O’Leary is popular for his no-nonsense approach to enterprise, and that extends to how he runs his possess providers. “Never ever waste income in the startup phase,” O’Leary urges. This may possibly necessarily mean building some sacrifices in the early days — like functioning out of your dwelling or forgoing fancy office environment room — but it will pay off in the extensive run when you’re capable to reinvest people cost savings again into your enterprise. 

O’Leary states that most organizations are unsuccessful because, “Their growth projections are mistaken. Their revenue projections are completely wrong and they run out of cash which is why 8 out of 10 enterprises are unsuccessful.” Currently being frugal and viewing your dollars stream is critical to accomplishment.

3. Focus on sales

“Regardless of what you pay back awareness to grows. Stop losing time and cash,” states O’Leary. “The most vital factor for a startup enterprise to do is to concentrate on product sales, that’s what the 1st two a long time are about.” 

“If you are not willing to do that perform — to get up in the early morning with a smaller firm and go get earnings, then you are not heading to be a profitable entrepreneur. It is really that very simple.” Income is what will eventually fund your growth and make it possible for you to scale up your operations. So even if you might be not successful at initial, as lengthy as you’re bringing in dollars, you’re on the appropriate track.

4. Know when to give up

A person of the most crucial choices you’ll make as an entrepreneur is when to stroll away from a failing small business enterprise. “If you can’t make cash following 36 months, it was a interest not a business enterprise,” suggests O’Leary. Do not be worried to slash your losses and transfer on to a little something new. “If you will not know how to pivot, you are heading to zero.” It might be agonizing in the shorter term, but it will conserve you a good deal of time, cash, and heartache in the long run. 

5. Construct a excellent team  

Encompassing oneself with gifted people who share your vision is 1 of the keys to success in enterprise — and daily life. “I would not be where by I am nowadays without the need of the amazing team I have crafted all-around me,” says O’Leary. “Discover people who are smarter than you are and who enhance your skillset.” This way, you’ll have the very best probable possibility of achieving your aims — regardless of what they may perhaps be. 

Starting off a enterprise is no straightforward feat — but with really hard work, determination, and these 5 tips from serial entrepreneur Kevin O’Leary, you’ll be well on your way to constructing a successful enterprise of your individual!

Skilled-picked business credit history playing cards with abundant rewards and benefits

Money back again, journey benefits, {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} intro APR financing: all of these can be great credit score card benefits for business enterprise homeowners. But how do you obtain the correct business enterprise credit rating card for you? There are tons of gives on the market place these days, and sifting via them to uncover the ideal one can be a major inconvenience. So we’ve completed the difficult get the job done for you.

Get started with just one of our prime small business credit rating card picks of 2022 today.

Authors discuss their book on student loans and Black borrowers

Authors discuss their book on student loans and Black borrowers

Scholar debt is a challenge that influences folks of all races in the United States.

But in A Desire Defaulted: The Student Mortgage Disaster Among Black Borrowers (Harvard Education and learning Push), Jason N. Houle and Fenaba R. Addo argue that the university student financial loan industry is not one that operates for anyone. Black pupils “are deprived in two opposing phases of the course of action: credit card debt accumulation and credit card debt reimbursement,” they create. Houle is an associate professor of sociology at Dartmouth College, and Addo is an affiliate professor of general public policy at the University of North Carolina at Chapel Hill. They responded to issues about their ebook via e mail.

Q: Some folks say “debt is debt” and that race doesn’t participate in a significant job in debt. What would you say in reaction?

A: So, we are not sure who these “some people” are … so we’d want to know extra about who is arguing that race does not make any difference to greater reply this dilemma. But we would say it is indeniable that race matters for university student mortgage financial debt in the United States, and that it issues far more than most any other social issue you could imagine of. The data bear that out in quite substantially every single details established we could leverage on this situation. Racial disparities in debt are substantial when persons leave higher education, and they only get greater in the a long time that comply with. Racial disparities in financial debt repayment—difficulties with repayment, or default—are massive throughout all sectors (two-calendar year/4-yr/community/private).

In simple fact, in a overview of the literature, Jacob Gross, Nick Hillman and other students have shown that race explains approximately as much variation in default prices as does school completion. So, race matters a wonderful deal, and we just cannot just chalk up these racial disparities in mortgage results to issues associated to faculty option or higher education completion. For case in point, we know, in the combination, that 4-year college graduates have really very low default charges. But when you break it down by race, you see a really different story. Twelve several years following graduating from a 4-yr school, 4 percent of white borrowers have defaulted. In the meantime, about just one in five (20 percent) of Black 4-year school graduates have defaulted on their financial loans. There’s a distinct racial divide right here in terms of debt accumulation, financial debt repayment and the outcomes that pupil loans have on the perfectly-remaining of borrowers.

Extra broadly, there are other means that “debt is debt” argument falls apart. Credit card debt is what economist sociologists phone “relational”—you have a contract concerning the loan company and the debtor (and listed here we could search to how Black pupils are discriminated towards in financial loan marketplaces, which would also undermine any assert that “debt is debt”). But debt is also tied to all types of relationships—the associations concerning you and your household as you come to a decision how you’re likely to fork out for faculty, for example, or even the relationship concerning you and your intimate husband or wife as you navigate personal debt reimbursement. So, credit card debt is profoundly social. And if we inquire thoughts like: Why are some people using on so a great deal [more] debt than other people? Why are some people today getting issue paying down financial debt when other people are not? Why is financial debt so stress filled, so consuming and so substantially a millstone that weighs down some individuals but not other people? What we obtain is that, for some, getting on debt is an chance, and for others, it’s a profound possibility. And, we argue in the e book, these variances are deeply tied to race.

But we’d also add this: it is not just that race matters. It’s that anti-Black racism issues. Why are Black students saddled with much more credit card debt, have far more trouble repaying that personal debt, and why is university doing work improved for white college students than it is for Black college students? We simply cannot response these queries without the need of recognizing that university student credit card debt the two displays and provides current racial inequalities that are rooted in historic processes of social exclusion, and that Black pupils and their people are expected to navigate institutions that were being not designed for them.

Q: When you interviewed Black debtors, how did they see the problem?

A: You would likely want to dig into the reserve to see all of these stories here—because our respondents have a whole lot to say about this issue, and your query is quite, very broad. So permit us just emphasis on one theme that arrived out of our interviews: quite a few of the folks we talked to were being struggling beneath the fat of their debt—they amassed a great deal of personal debt in university, they ended up obtaining trouble repaying that personal debt afterwards—and a ton of these debtors had been actually grappling with the query “What could I have completed in a different way?” Some folks took this to their extreme—blaming on their own for their situation—but fairly substantially everybody took responsibility and, with the reward of hindsight, think they could have designed some distinctive decision so that they wouldn’t have finished up saddled with all this personal debt. And of program, these debtors have … internalized the broader social narrative on financial debt: that we could resolve all of these troubles if people had been just extra fiscally literate, or designed greater conclusions.

When we were being conducting our interviews, we questioned everybody how they felt about their university student financial loans, and quite a great deal all people gave us some edition of the tale “I want I could have finished some thing differently,” as if there was some final decision that they could have built that would have kept them out of personal debt. But a single tale trapped out to us. This human being who we phone Alexandra was actually challenging on herself—you know, she had like $30k in financial debt, she was having a tricky time earning her payments each and every month, she was working with unfavorable amortization. And all she did was blame herself, and she deconstructed every single solitary final decision she created. Here’s one particular matter she claimed: “I just desire I was a lot more intense. I received scholarships, but I would like I was even more intense in successful much more scholarships. I just wish I realized, like, ‘Hey, you should actually set up a company in high school.’ So then, I’d be in a position to shell out for school outright.”

We definitely like this quote, and this tale, due to the fact it will make it so obvious that she did every little thing “right” and it just was not plenty of. And she has gotten to the issue where she has these insanely superior anticipations for her superior school–aged self that are wholly unrealistic. And it would make the remedy evident: no amount of money of fiscal planning, or literacy, was heading to save her from this final result. Which helps make it all the far more upsetting, and unfortunate, that she appears to be like inward at her own faults when she is pondering about her problem.

That is a person illustration, but it is just an illustration. So several of our job interview respondents ended up constantly weighing the economic expenses and rewards of distinctive conclusions: perhaps they wished to go to that HBCU out of state, but they went to the regional university down the street to preserve income and maintain living at dwelling. And nonetheless they nevertheless desire they could have carried out one thing otherwise.

We typically communicate about university student bank loan financial debt in this state as the final result of unique conclusions: that with some economical literacy, or cautious arranging, college students can stay clear of getting on far too a lot financial debt or obtaining into difficulty. Politicians speak about this all of the time. Much of the debate all around pupil financial debt forgiveness revolves around this pretty problem: that some folks argue we do not want to subsidize other people’s lousy choices. But there’s so numerous difficulties with this framing. One particular, is it frames personal debt as some form of “mistake”—like if you took on debt, or far too considerably financial debt, then that is your individual fault, the result of your have decisions. But naturally, we’ve made better education such that you practically have no preference but to borrow if you want to go to school. So heading into personal debt is not some choice that needs to be optimized or enhanced upon—it’s a element of the method.

Q: How does debt affect Black students’ decisions about likely to graduate or specialist university?

A: So if we’re asking why so lots of younger men and women are picking out to go to graduate/specialist faculty, we can assume of financial debt as component of this story, but only portion. What really matters are the options and occupations that are available for people immediately after they complete their undergraduate diploma. A good deal of the debtors we talked to who went to graduate faculty experienced a very similar tale: they graduated, had issues getting a job just after college and then finished up generating much fewer than they imagined they would have in employment that only occasionally aligned with their degree. Then, at the time their pupil financial loans arrived because of 6 months following graduation, they experienced 1 far more invoice to spend when they were being by now having difficulties to locate their footing. And so normally, a ton of them were like: very well, if I want to make a dwelling, or get my foot in the door at some better occupation, I guess I have to go to graduate faculty. This is classic credentialism: as companies ratchet up the demands for some employment, then the labor pool will follow.

And all over again, ordinarily scholars and policy makers are a lot less concerned about graduate school debt, possibly with excellent motive: individuals with specialist degrees (lawyers, health professionals) might have eye-popping financial debt masses, but on normal they never have significantly issues repaying that financial debt since they are in these superior-paying professions. But newer research demonstrates that graduate school financial debt is rising, and that racial disparities in graduate faculty financial debt have gone via the roof in the past decade or so, for several of the exact same good reasons we communicate about in the book. And of program, graduate university is exactly where you can rack up the serious eye-popping amounts of credit card debt: $60, $80, $100k—because numerous of these graduate courses are unfunded, they serve to deliver in revenue for the faculty, and there are no mortgage boundaries for Furthermore loans.

So the dilemma is, will these graduate degrees spend off? And the response is we just don’t know, but what we do know is not promising: that is, even among the specialist degree holders, we see large racial disparities in salaries, promotion and profession advancement. So, once again, not only are Black borrowers having on a lot more hazard in the pursuit of a graduate degree—which they’re carrying out not as a vainness venture, but simply because they really feel like they have no choice—but the benefits do not look to be the exact same as their white counterparts will take pleasure in.

Q: What about what President Biden is hoping to do? Has he acknowledged financial debt as a racial difficulty?

A: Very well, initially of all, Biden is in all probability executing near to every thing he can given the political realities of Congress. This in all probability wasn’t going to go in the Residence and Senate, so this debt-forgiveness plan is almost certainly the ideal we can hope for, and to be trustworthy, it was in all probability a lot more than quite a few of us considered was possible three or 4 several years ago.

Does Biden figure out that university student personal debt is a racial justice issue? Most likely this is an argument that other people in his celebration have manufactured, even if he doesn’t converse about this publicly. So, we don’t know what it is in his heart.

But if we want to request whether this debt forgiveness may perhaps reduce some of the stark racial disparities in the stress of student financial loan financial debt we argue in this ebook? Perhaps, but it is not a silver bullet. That claimed, there are some options of the method that are promising. A several factors: 1) the policy by itself is progressive, and acknowledges inequality, if at minimum as a result of the lens of income. Those people with Pell Grants—which include things like many Black borrowers—are in a position to get up to $20,000 in forgiveness, whilst other debtors who had been most likely a lot more socially advantaged get significantly less in forgiveness. 2) The method is simple to utilize for, and (hopefully) basic to profit from. Our colleagues Pam Herd and Don Moynihan compose eloquently about “administrative burden” and how very well-indicating social plans and procedures are exceptionally difficult for people to entry. This is notably true in the pupil mortgage program: cash flow-dependent compensation, for example, is hard to access and keep enrolled in, and we all listened to the horror stories about the rollout of the Public Services Financial loan Forgiveness program …

Q: What more really should Congress, the president and faculties do about this difficulty?

A: At the close of the day, personal debt forgiveness is an crucial plan, but it is a downstream remedy to an upstream difficulty. And if we do not do extra to deal with faculty affordability—perhaps by rising monetary help, or relocating forward a nationwide plan on no cost college—we’re likely to be right back to square 1 in one more decade. So we completely need to see a lot more action on this entrance. And, as we argue in the guide, so a lot of the story at the rear of racial disparities in university student bank loan debt replicate[s] broader racial inequalities in this nation that are so significantly larger than larger education—structural racism, discrimination in the labor industry and discrimination in personal loan markets—so this will need broader fixes. Indeed, these are exactly the problems that the Black Life Make any difference movement reminded so lots of individuals of throughout the pandemic. So, if we don’t deal with the root of the problem—racism—we’re not likely to clear up this issue wholly.

Supreme Court blocks Congress getting Trump tax returns

Supreme Court blocks Congress getting Trump tax returns

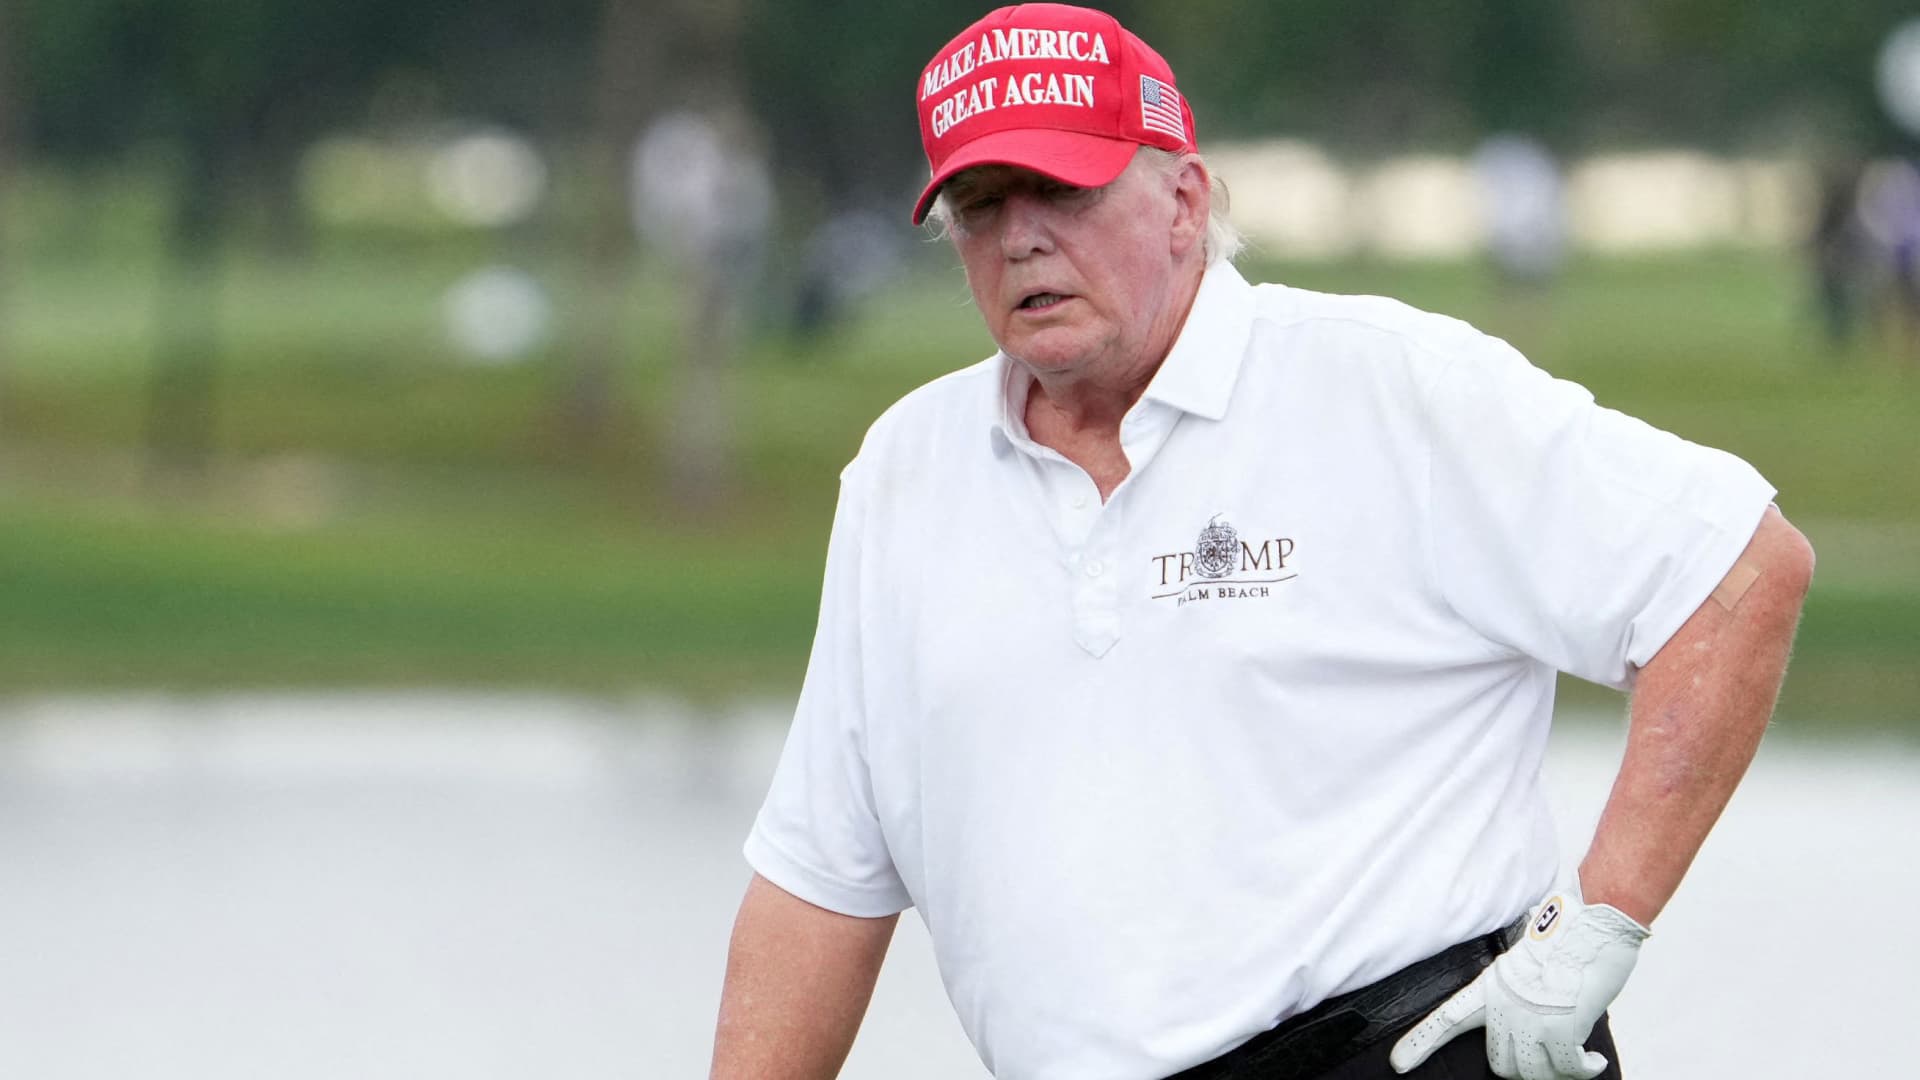
Former President Donald Trump stands on the 18th green in the course of the Professional-Am tournament prior to the LIV Golfing sequence at Trump National Doral, Oct. 27, 2022.

Jasen Vinlove | United states Right now Sports | Reuters

Supreme Courtroom Main Justice John Roberts on Tuesday temporarily blocked the House Strategies and Indicates Committee from obtaining a long time of federal cash flow tax returns of former President Donald Trump and similar business entities from the IRS.

Roberts’ buy came a day after Trump’s lawyers filed an emergency application with the Supreme Courtroom requesting the hold off, and two days in advance of the IRS was established to give the committee the Republican’s tax returns.

The main justice gave the Strategies and Signifies Committee until Nov. 10 to respond to Trump’s software for the hold off.

Trump needs the Supreme Courtroom to block the committee from acquiring his tax returns and all those of the related entities for the a long time 2015 through 2020 till he formally asks the significant court to let him to attraction decreased court rulings that cleared the way for the data to be handed in excess of.

The Democratic-managed Methods and Implies Committee has reported it wishes the returns as element of a probe of how the IRS audits presidential taxes.

Trump fraud case about 'greed and cheating,' says prosecutor

But Trump, who as a applicant and president broke 4 a long time of tradition by refusing to publicly release his tax returns, argues the committee is just making an attempt to embarrass him and ideas to make public his returns.

Trump’s application Monday was directed to Roberts because the main justice handles unexpected emergency applications, these types of as this 1, arising out of the U.S. Court docket of Appeals for the District of Columbia Circuit.

Dylan Peachey, a spokeswoman for the Methods and Indicates Committee, in a statement responding to Roberts’ get claimed the committee “maintains the regulation is on our aspect, and will file a timely response as asked for.”

Peachey also reported that Committee Chairman Richard Neal, D-Mass., “seems to be forward to the Supreme Court’s expeditious thought.” 

Trump’s lawyer, William Consovoy, did not right away react to a ask for for remark.

The Supreme Courtroom does not quickly grant appeals.

And it is not distinct if Trump will encourage ample justices on the court docket, a few of whom he appointed, to consider his scenario. But if the courtroom does so, it could avoid the committee from receiving the returns for months, or even many years.

Supreme Court circumstances can consider months or for a longer period to take care of.

And if Republicans get back vast majority handle of the Residence of Associates in following week’s midterm elections, they are guaranteed to shut down the Techniques and Indicates Committee’s energy to receive Trump’s returns.

That committee first requested the documents from the Treasury Section, the IRS’ guardian, in 2019, when Trump was nevertheless president.

The panel sought Trump’s specific cash flow tax returns and individuals of the Donald J. Trump Revocable Believe in and 7 minimal liability companies, 1 of which does organization as Trump Nationwide Golf Club in Bedminster, New Jersey.

The Treasury Office, at the time controlled by Trump appointee Steven Mnuchin, denied the request, expressing it lacked reputable objective.

The committee then filed match in U.S. District Court docket in Washington, D.C., in search of to compel the office to hand in excess of the returns.

In July 2021, months right after Democratic President Joe Biden took office, the Treasury Division reversed its stance and reported it had no choice but to comply with the committee’s request.

Trump then sued, trying to get to block the returns from currently being turned more than, arguing the committee lacked a legitimate legislative goal and violated the constitutional separation of powers involving the government and legislative branches of federal government.

CNBC Politics

Go through far more of CNBC’s politics coverage:

U.S. District Decide Trevor McFadden, who was appointed to the bench by Trump, in December rejected Trump’s arguments and ordered the IRS to give his returns to the committee.

Trump then appealed the purchase to the U.S. Court of Appeals for the District of Columbia Circuit. But he missing that work in August.

A a few-decide panel of the appeals court docket, in a unanimous choice that month, famous that even though tax returns, as a rule, are private less than federal regulation, an exception is when the chairman of the Strategies and Signifies Committee requests returns in composing from the secretary of the Treasury Section, the mother or father of the IRS.

Very last week, the appeals court denied Trump’s ask for that a larger panel of judges on that court rethink the circumstance. That led to his emergency software Monday asking the Supreme Courtroom to intervene.

Correction: Trump’s attorney is William Consovoy. An earlier edition misspelled his name.