CPA Jamie Trull Uses Care, Simplicity to Help Small Businesses Thrive

CPA Jamie Trull Uses Care, Simplicity to Help Small Businesses Thrive

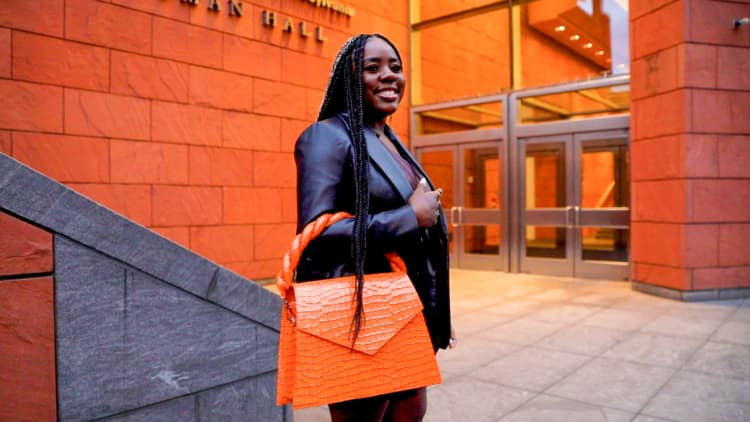
Each year in recognition of Women’s History Month, SPARK functions outstanding females compact-company leaders. Concluding its 2023 coverage is Jamie Trull, a monetary literacy mentor and gain strategist.

Jamie Trull desires to be a various sort of CPA.

“Everyone has a picture in their mind when a person talks about their CPA,” she says. “A standard business product goes together with that, one that I will not subscribe to. I have the designation, but I want to be extra approachable. I want to be with it.”

Who in the environment is Jamie Trull?

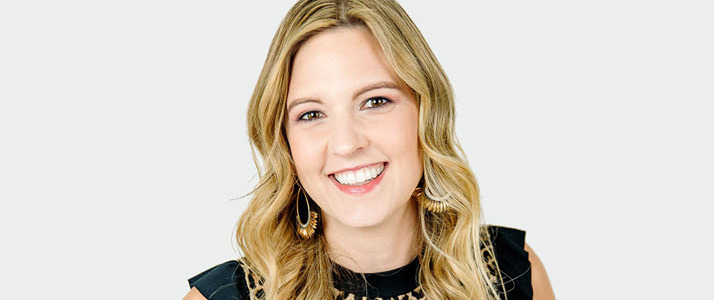
Jamie Trull is the founder and proprietor of jamietrull.com, a digital – approachable – finance education business that will help smaller businesses get manage of their dollars. Jamie’s an experienced financial qualified and CPA, acquiring expended 13 decades at Ernst & Youthful and Coca-Cola Enterprises. Her property is the South, her head is crammed with numbers and her coronary heart belongs to modest-organization homeowners.

Reflecting on her beginnings, Jamie states, “I started supporting modest-small business owners that I realized desired help with finance. I was like, ‘Well, I did it for a Fortune 100 enterprise. I can possibly do it for them.'”

But that epiphany arrived soon after Jamie remaining a 10 years-very long job at Coke. Her explanation for leaving? A merger, with no which she may perhaps not have uncovered her entrepreneurial objective.

Coke was great. Home was much better.

Jamie’s departure from company America isn’t like other tales you may perhaps have read. She didn’t go away the Fortune 100 simply because she was unhappy or trying to find a new profession. She left her expert home for the reason that she failed to want to go away her individual dwelling: the United States.

“We experienced a significant merger inversion, and our headquarters moved to London,” she suggests. “I beloved the firm I labored for, but I had a option: go away Coca-Cola or transfer to Europe. I was expecting with my next youngster at the time, and I finished up choosing to remain. It was a loved ones-pushed final decision, and Tennessee is exactly where my loved ones is, so I moved closer to dwelling.”

Goodbye, Atlanta!

Howdy, Franklin, Tennessee!

Cash, motherhood and combined thoughts

Jamie moved house with her relatives, a severance offer and no strategies for her job. Jogging a virtual finance training enterprise? Nope. Hadn’t even crossed her mind.

1st and foremost, Jamie was targeted on caring for her then-new child. She took an extended maternity go away, relying on her severance for support. When that ran out, it was again to perform.

“I mentioned, ‘Okay, perhaps I am likely back again to a different company work.’ But I was picky,” she suggests. “It was all through that time that I commenced to think, ‘Is there a further alternative below?’ I didn’t want to go again to a different 70- or 80-hour-a-week task with two youthful children at home. That didn’t make sense.”

But Jamie felt she had no preference. She delivered out her resume to recruiters and was on monitor to land a terrific occupation, albeit one particular that needed her to be away from property. All she had to do was give an up to date resume.

“But at that moment, I just cried,” she claims. “I looked at my daughter and mentioned, ‘I can not do it.'”

Residence (n). A put for gaining point of view.

Jamie desired (and required) to return to perform, but she did not want to return to an business. Luckily, the freshly merged Coca-Cola Enterprises attained out to her. They necessary assistance schooling their new staff. The ideal element? She could do it from home. But not forever. When the Coke gig kept her at home, exactly where she could prioritize her youngsters, contractually, it was temporary.

“I truly preferred doing work from home, and I reported, ‘I want to do some thing that I can do whilst obtaining my lifetime, far too. Probably I have to have to develop it.’ And which is wherever it commenced,” she claims. “I just started off encouraging some tiny corporations with their finances.”

That is also when Jamie realized she’d stumbled onto an idea. She started putting her identify out there, reaching out to many modest firms and turning out to be a lot more lively on social media. She swiftly amassed 10 shoppers and a waiting around listing. But 10 was her utmost.

“I was presently doing work a lot,” she suggests. “I understood I experienced to do this a unique way.”

A distinctive way

Jamie started out delivering her know-how on Fb Are living and in a Fb team she designed, to satisfy client desire. The team exploded, she states.

“That is when I realized there was this require for education and learning and this will need to empower men and women,” she additional. “But the men and women I seriously preferred to work with were being the scaled-down companies that could not find the money for a digital CFO, which is what I was doing with my clientele. I required to help compact firms.”

Jamie dropped the company organization model, phasing out her purchasers individually, and pivoted to an education-based mostly design prioritizing little-organization funds.

These days, jamietrull.com takes advantage of snackable educational information and intelligent electronic advertising and marketing to entice new enterprises. In other text, jamietrull.com is “with it.” Jamie’s grow to be an successful articles internet marketing equipment, building courses, bundles, cheat sheets and toolboxes for all to love.

“These days,” she suggests, “my work is extra online marketing and advertising than being a CPA or undertaking just about anything in the economic realm.”

And you can tell. Visit Jamie’s web page, and you may explore how a lot time she places into generating an engaging educational practical experience. Her brand is upbeat, encouraging, clear-cut and down-to-earth, and there is certainly a superior rationale for that.

Interested in finance or accounting? Subscribe to our publication.

Eliminating the judgment

Jamie’s troubled by some economic professionals’ inclination towards judgment and criticism. She says this inclination can retain people today from finding the monetary support they have to have. In the end, it could maintain them away from financial experts like Jamie, who reject judgment and criticism in favor of compassion and empathy.

“When men and women are previously judging on their own for their selections, it truly is quick for them to choose up on judgment from many others, and then they maintain things near to the chest,” she claims. “They don’t make beneficial improvements or get enable for the behaviors that have held them again. Cash-smart, routines-intelligent, they just stay the place they are.”

Discovering a economical professional who does not make you sense undesirable about your conclusions can be a body weight lifted off your shoulders. By means of jamietrull.com, Jamie wants to help additional compact-business enterprise homeowners really feel validated.

“When you locate somebody you can open up up to and discuss about these matters with, you understand you might be regular,” she says. “When you do the job with any individual who can make you really feel like you happen to be ordinary and that your situation is usual, it empowers you and paints a picture of what a optimistic potential can seem like.”

She ongoing, “Quite a few people do the ‘tough love’ issue in this business. I think it’s detrimental that we are generally utilizing that to manipulate persons about their money. I wanted to build this room that helps make persons say, ‘I employed to operate away from revenue, but now it feels doable.'”

Decoding the jargon

Jamie’s also interested in simplifying the jargon some tiny-business entrepreneurs come upon while controlling and expanding their funds. She’s noticed the problem firsthand when doing work with mother-and-pop outlets, boutique homeowners, pet sitters, landscapers and other little enterprises across the U.S.

“These are people today in our day-to-day lives who did not get an MBA,” she claims. “They all own businesses, and they did it mainly because it truly is something they cherished or had been superior at. The finance things arrived secondary.”

Jamie claims the jargon can get above when you achieve a selected position in your business’s development, generating confusion, miscommunication and irritation.

“When you get to the point of needing to use men and women to scale your small business or of needing to devote in a variety of things to make the business enterprise expand, it starts receiving really hard,” she says. “You can get missing in all the jargon of taxes and other things that are intimidating for people.”

Jamie encourages small-business homeowners to try to remember just one point when they are emotion defeated: In the conclusion, it truly is seriously just straightforward math.

“Even though accountants adore to make up fancy terms for factors (really don’t get me started out on EBITDA),” Jamie says, “the components that seriously matters is an easy 1: revenue minus bills equals gain.”

Check out Jamie’s Money Health Essentials program for extra on decoding the jargon.

Jamie’s modest-business enterprise outlook: Economic downturn and inflation

Recession: Planning is all the things

Recent stories of a probable recession have stoked fears among tiny-business enterprise proprietors, including individuals below Jamie’s wing.

“Regrettably, when you can find far more dread about a recession, the worse that possible economic downturn receives mainly because everybody stops paying,” Jamie states. “Certainly, other factors are at play, but there’s also this stress that comes about.”

Jamie’s advice

Just take a deep breath, put together and get imaginative.

“Let’s sense assured in the items we can handle and not enable them arrest us,” she says. “We have to lean into our creativeness. These cycles happen, and they are likely to hold occurring. We require to build up our reserves. We need to be very clear about our gain margins and make sure we’re priced correctly. We want to be agile and able to adjust speedily. Can you minimize selected locations proactively, together with where by you might be overspending, which may perhaps continue to keep you from lowering employees? There are so many factors we can do.”

Get the scoop on economic downturn preparedness in this MainStreet Macro online video.

Inflation: Deflation is not likely

Jamie advises compact-enterprise owners to believe critically about resources boasting inflation will decrease and turn into deflation, or a normal ongoing decrease in selling prices. As a substitute of deflation, disinflation, which is a non permanent slowdown in costs, is a lot more very likely.

“If you glimpse at background, inflation will slow, but it hardly ever goes damaging,” she says. “We rarely have deflation. For case in point, if we’re at 7 per cent inflation, it may slow to 4 percent, but which is still increasing. It is not heading to go detrimental, so you really don’t want to hold out to act. You are hurting your self if you wait far too very long to adjust your charges.”

Jamie’s information

Have an understanding of the big difference in between rate gouging and monitoring your profit margins.

“The compact-business enterprise proprietors get squeezed because the huge enterprises they’re purchasing provides from are increasing their rates. If you’re a restaurant buying meat, for example, from 2020 to 2022, average meat prices enhanced by far more than 20 percent,” Jamie suggests. “You cannot retain promoting at a reduction, for the reason that you happen to be not going to remain in business, and then you happen to be going to have to let go of your workers, impacting their lives and all those of your prospects. Making sure your gain margins are sustainable is not price tag gouging. You have to [watch your profit margins] to be able to stay in small business.”

Read through How Leaders Can Deal with Concerns About Inflation and Help Staff for additional on adapting to inflation.

Empowering women tiny-business proprietors

1st and foremost, Jamie needs all tiny-business enterprise house owners to sense self-assured about their enterprise funds. But she has a unique position in her coronary heart for encouraging women of all ages, especially mothers. It stems from her experiences performing and starting up a company with two youthful young children at her feet.

“I started off to recognize with motherhood that there are unique issues girls encounter,” she says. “I was always a large achiever at get the job done. It was a tough changeover when perform went from being my most important priority to me having a loved ones and obtaining to determine out how to alter. My job, for so extensive, was my identity, and now I am a mother, so I treatment considerably less about that, but I nevertheless treatment about it. Turning out to be a mom built it tricky to are living up to my anticipations of what I could do basically simply because I experienced much less time that I was eager to commit to operate.”

She ongoing, “When I went into the tiny-business enterprise entire world, I discovered with so a lot of of the women small-business enterprise owners mainly because they were caretakers for their young children or their ageing mother and father and wanted one thing extra flexible than a career that involves you to sit in an business each individual day. They needed one thing distinctive. I have gotten so considerably flexibility and versatility out of my business that I want more women to truly feel that way. I want them to notice that there are alternatives. It really is not one or the other. You can operate a enterprise and be a mother.”

By means of jamietrull.com, Jamie hopes she can assist a lot more girls smaller-enterprise house owners, moms integrated, reach freedom and adaptability in their function and particular life.

“I want additional girls to truly feel confident,” Jamie suggests. “I want them to sense much more empowered with funds, with building choices about their funds. I want them to obtain the freedom they are searching for.”

One particular thing’s for absolutely sure: Monetary literacy and savvy revenue administration can be liberating resources for all. And if the help obtained alongside the way takes place to be compassionate and uncomplicated, the journey to economical assurance will be that a great deal a lot easier – and a whole lot significantly less agonizing.

Jamie’s partnership with ADP

Aiding Jamie do well guiding the scenes is Operate, Powered by ADP, a compact-enterprise payroll solution that handles the nitty-gritty, so Jamie can concentrate on her small business.

“I’ve seriously savored making use of Run,” Jamie claims. “I assume it can be definitely effortless to use. I’m massive on intuitive application. I’ve applied a handful of unique payroll systems, and I actually like [how intuitive RUN is]. What I like about it most is that I have my possess advisor. If I have a issue, I can ask and get an remedy from the exact human being. I don’t have to get in touch with a 1-800 variety. I really don’t have to sit on keep for a million many years. It really is nice to have any person who can just just take care of it.”

Expertise Operate, just one of Jamie’s best picks for payroll options.

Additional Women’s Record Thirty day period stories

Lights the Way with Cate Luzio and Luminary

Mamaprenista Stephanie Cartin on Motherhood, Business enterprise, Ladies at Work
&#13
Tags:&#13
&#13
Variety and Inclusion&#13
Management&#13
Trends and Innovation&#13
Tiny Business Payroll&#13
Tiny Enterprise&#13
Article content&#13
Finance&#13
Vocation Management&#13
Economic Products and services&#13
Business Proprietor&#13

Michael B. Jordan talks financial literacy at HBCU basketball classic

Michael B. Jordan talks financial literacy at HBCU basketball classic

Michael B. Jordan claims the biggest lessons he is discovered about revenue management arrived from “life.”

Nonetheless, he wonders where by he would be if he had been taught additional about income when he was more youthful.

“I picture how significantly additional I would have and the improved place I would be in today if I had that sort of know-how at an early age and recognizing how to take treatment of your money,” he tells CNBC Make It.

That is one particular rationale he is aiming to support Black students and university student athletes attain obtain to fiscal literacy schooling early.

The actor, director and producer partnered with Invesco QQQ to make the Invesco QQQ Legacy Common, a men’s higher education basketball showcase that includes Historically Black University and University (HBCU) scholar athletes, broadcast nationally on TNT. For its second 12 months, the celebration was held on Feb. 4 at Prudential Centre in Newark, New Jersey, exactly where Jordan grew up.

Obtaining younger individuals thrilled about studying how to well handle their money was at the heart of the occasion — and Jordan’s mission.

“There are a good deal of things out there telling them to shell out their revenue on this or that,” he says. “So possessing yet another procedure in area to assistance them commence wondering in another way about their funds is crucial.”

Equitable entry to economic literacy can help shut the racial prosperity hole

In the U.S., the common white house has a net worth of $875,600, although the typical Black residence has a internet really worth of $126,300.

Whilst you can find no basic option for closing the racial prosperity hole amongst white Us citizens and Black Us citizens, strengthening monetary awareness between Black and Brown learners could aid bridge the divide, suggests Yanely Espinal, director of instructional outreach at Upcoming Gen Private Finance, a nonprofit centered on furnishing money schooling to middle and higher college students.

At present, learners throughout the country aren’t receiving equal entry to private finance schooling, according to investigate by NGPF.

A lot less than 12{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of students are expected to get a stand-alone individual finance system to graduate from high faculty outdoors of the six states that mandate it, in accordance to NGPF. Even so, just 7.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Black and Brown college students are expected to take a class.

Without having equivalent obtain to personal finance educational resources, the racial wealth gap will only get wider, Espinal tells CNBC Make It.

Plus, when monetary literacy is taught early, it pays off in the future, analysis from the Brookings Institution demonstrates.

Higher faculty college students who are necessary to choose personal finance classes have a tendency to have superior average credit score scores and decrease personal debt delinquency fees as young grownups, according to the Economical Industry Regulatory Authority’s Trader Schooling Foundation.

Additionally, when pupils receive entry to personal finance training, it can have a ripple outcome on their households and communities.

“The college students completely acquire this home,” Espinal suggests. “You see mothers and fathers inquiring about Roth IRA accounts and whether or not they ought to open them.”

Sign up now: Get smarter about your income and vocation with our weekly newsletter

Do not skip: Self-made millionaire: You never have to give up lattes to get rich—do this instead

How these Black female entrepreneurs are building wealth

Bill would mandate teaching financial literacy | Local News

Bill would mandate teaching financial literacy | Local News

A new bill would require Vermont public university learners to take a own finance training course to graduate high school.

If the invoice, H.228, passes, the mandate will go into impact July 1 and utilize to all community large university college students graduating all through or after following university calendar year.

Teachers support personal finance education

Teachers support personal finance education

by Courtney Poquette, et al We are Vermont educators who teach high school personal finance, and we are united in support of legislation that would guarantee a full-semester, standalone personal finance course as a graduation requirement for all Vermont students.

Why is it so important to the future of our young students? Research by Next Gen Personal Finance (NGPF) and others demonstrates clearly that guaranteed personal finance education leads to positive outcomes and improves lives forever.

That is why we heartily endorse HB228, which would require just such a standalone course.

The traditional approach in high school is to teach students how to manage money for companies they will work for. But our young people never learn how to manage their own money, and their parents often are not money-savvy either, since they also were not taught personal finance.

In 2023, we believe that all high school graduates must be financially literate, whether they are headed to college, work or the military after graduation.

We are fortunate to be in schools that have a guaranteed personal finance course. Many of us have designed our own lessons and materials, but now, free curricula, lesson plans and other resources are available online through non-profits like NGPF.

Some high schools have partnered with the Community College of Vermont to attract students to the class who were college bound and had busy schedules. Now they can take the class and obtain college credit.

Our students think they will be rich if they earn $40,000 a year when they graduate. In our classes, we help them to realize how expensive their dream lifestyles are. Such reality checks force them to question decisions in their near futures, like college majors, job salaries, the cost of credit and more.

You would not believe how often we hear from students and their parents that our course has changed the direction of students’ lives for the better. And as teachers, we learn too. After all, we have household budgets, kids to send to college and retirement to think about.

Not long ago, a report showed that parents would rather talk to their kids about sex than about money. Personal finance classes make talking about money at the dinner table the new normal. Students in our classes use math, reading and language skills while working on monthly budgets and retirement plans. What could be more important today?

Many of Vermont’s educators have become confident teaching personal finance through free training provided by Champlain College’s Center for Financial Literacy, NGPF or other organizations like the Jump$tart Coalition.

So we have confident, trained teachers, free curriculum and with innovative ideas, we can make room for high school personal finance. There is no reason not to move forward.

The good news is that teachers, administrators and legislators across the nation are passionately advocating for this change. As of this writing, 17 states have passed legislation guaranteeing full-semester personal finance courses, and NGPF reports that there are currently 74 bills in 21 other states, including Vermont, in process.

We hope all states, including Vermont, adopt a guaranteed high school course. It’s an especially important issue in many black and brown school districts, where access to personal finance learning is more limited than in whiter, more affluent district.

Personal finance is a critical skill that perhaps more than any course sets  students up to succeed in life. We never have to explain to our students why the course is important. They get it. Let’s make sure all Vermont high school students get it.

Signed,

Courtney Poquette, Winooski High School, Winooski

Mary Brouilette, Bellows Free Academy, St. Albans

Bob Fredette, Lamoille Union High School, Hyde Park

Angela Pandis, Missisquoi Valley Union HS/MS, Swanton

Drew Gordon, South Burlington High School, Burlington


Evidence that Financial Education Improves Behavioral OutcomesTeachers support personal finance education


Evidence-Based Policy & Implementation Resources


Evidence that Financial Education Improves Behavioral Outcomes


a) The Effects of K-12 Financial Education Mandates on Student Postsecondary Education Outcomes

Research from the National Endowment for Financial Education. Financial education mandates have positive impacts on student borrowing behaviors across all income groups. States with personal finance graduation requirements have students with a higher incidence of applying for financial aid, a lower incidence of borrowing from private student lenders, a higher incidence of receiving grants and federal aid, and a lower likelihood of carrying credit card balances.


b) Does Financial Education Impact Financial Literacy and Financial Behavior, and If So, When?

Most earlier studies of financial education rely on outdated financial education requirements. Kaiser and Menkhoff show significant positive effects of financial education on both financial literacy (knowledge) and financial behavior. This meta-analysis corrects an often cited meta-analysis from Fernandes et. al. (2014), adding additional interventions and a more rigorous statistical methodology to make its conclusions. Compelling, rigorously critiqued evidence of the need for “just in time” financial education for high school students.


c) Financial Education Matters: Testing the Effectiveness of Financial Education Across 76 Randomized Experiments

We study the rapidly growing literature on the causal effects of financial education programs in a meta-analysis of 76 randomized experiments with a total sample size of over 160,000 individuals. The evidence shows that financial education programs have, on average, positive causal treatment effects on financial knowledge and downstream financial behaviors. Treatment effects are economically meaningful in size, similar to those realized by educational interventions in other domains, and are at least three times as large as the average effect documented in earlier work. These results are robust to the method used, restricting the sample to papers published in top economics journals, including only studies with adequate power, and accounting for publication selection bias in the literature. We conclude with a discussion of the cost-effectiveness of financial education interventions.


d) Does State-Mandated Financial Education Affect High-Cost Borrowing? (UPDATED 2019)

“…young adults who were required to take personal finance courses in high school were significantly less

likely to borrow payday loans than their peers who were not. These effects do not significantly differ by race/ethnicity or gender, suggesting that financial education may be useful regardless of demographics.” 


e) Retirement Savings with School-Based Financial Education

Students’ financial literacy performance is significantly associated with their schools’ and teachers’ characteristics, both positive and negative. Students who attend a school with adequate teaching materials and competent teachers — those who demonstrate control over their classroom and try to actively engage with students — are more likely to perform at the two highest levels on the PISA financial literacy test.


f) Optimal Financial Knowledge and Wealth Inequality

Financial literacy plays a key role in explaining inequality. Different levels of financial knowledge early in life have important implications for how much people will save. Adding financial knowledge to life cycle models permits a more accurate rendering of a world where consumers must cope with complex financial markets and must save so as to provide for their own retirement.


g) The impact of high school financial education: experimental evidence from Brazil

This paper studies the impact of a comprehensive financial education program spanning six states, 868 schools, and approximately 20,000 high school students in Brazil through a randomized control trial. The program increased student financial knowledge, increased saving rates for purchases, better likelihood of financial planning, and greater participation in household financial decisions by students. “Trickle-up” impacts on parents were also significant, with improvements in parent financial knowledge, savings, and spending behavior. The study also finds evidence that the program affected students’ inter-temporal preferences and attitudes.


h) Personal Finance Education Mandates & Student Loan Repayment

“Students with higher-income parents respond by adjusting borrowing, reducing median balances by 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. By contrast, first-generation and low-income borrowers bound by mandates did not significantly adjust borrowing, but were nonetheless more likely to pay down balances..”


i) Can financial literacy reduce domestic violence?

“Yes. Using data on more than 3.7 million intimate partner violence (IPV) incidents between 1994 and 2016, and exploiting the staggered introduction of state-mandated personal finance high school graduation requirements across U.S. states for identification, we show that improvements in women’s financial literacy can significantly reduce the rates of violence against women perpetrated by their male partners. We conservatively estimate a reduction in violence by between 3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and 11{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. Our evidence points to financial literacy deterring financial abuse, thereby empowering women to leave abusive relationships earlier or by preventing the first incident from ever occurring.”


Evidence-Based Policy & Implementation Resources


a) Transforming the Financial Lives of a Generation of Young Americans POLICY RECOMMENDATIONS FOR ADVANCING K-12 FINANCIAL EDUCATION

What we propose here is a comprehensive strategy to impart personal financial management skills to young people while they are in school. Recommendation 1: Introduce key financial education concepts early and continue to build on that foundation consistently throughout the K-12 school years. In addition, CFPB encourages states to make a stand-alone financial education course a graduation requirement for high school students. Recommendation 2: Include personal financial management questions in standardized tests. Recommendation 3: Provide opportunities throughout the K-12 years to practice money management through innovative, hands-on learning opportunities. Recommendation 4: Create consistent opportunities and incentives for teachers to take financial education training with the express intention of teaching financial management to their students


Consumer Financial Protection Bureau. (2013). Transforming the Financial Lives of a Generation of Young Americans POLICY RECOMMENDATIONS FOR ADVANCING K-12 FINANCIAL EDUCATION. [online] consumerfinance.gov. Available at: http://files.consumerfinance.gov/f/201304_cfpb_OFE-Policy-White-Paper-Final.pdf


b) Final Report – President’s Advisory Council on Financial Capability

The Council acknowledges that financial capability must be woven into the fabric of our lives—into our homes, our schools, our workplaces, our communities, even the design and regulation of the financial products and services we use. 


United States Treasury. (2013). Final Report President’s Advisory Council on Financial Capability. [online] treasury.gov. Available at: https://www.treasury.gov/resource-center/financial-education/Documents/PACFC{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20final{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20report{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20revised{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}2022513{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}288{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}29_R.pdf


c) Financial Capabilities of College Students from States with Varying Financial Education Policies

Well-educated students exhibit positive financial behaviors. After analyzing data from 15,797 college students, Gutter found that students from states where a financial education course was required had the highest reported financial knowledge and were more likely to display positive financial behaviors and dispositions. Compared to other students, these young adults were: More likely to save; Less likely to max out their credit cards; Less likely to make late credit card payments; More likely to pay off credit cards in full each month; Less likely to be compulsive buyers; More likely to be willing to take average financial risk

https://www.nefe.org/_images/research/Financial-Education-Mandates-Report/Financial-Education-Mandates-Report-Executive-Summary.pdf


d) Financial Education in High Schools Across America

State-level embedded course requirement mandates do not result in full compliance. While this lack of compliance could be because course catalog descriptions do not detail financial literacy instruction in all schools, it could also be because state departments of education have trouble auditing embedded course mandates. In our estimate, only 43{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} within states that have embedded course mandates have either a standalone or embedded course requirement.


e) Financial Literacy Subject Survey

Between July 15th and 17th, 2017 the National Financial Educators Council asked 5,123 young adults, “What high school-level course would benefit your life the most?” Respondents chose money management more often than math, science, and social studies:

  • 49.97{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Money Management (Personal Finance)”
  • 18.25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Mathematics (Algebra, Geometry)”
  • 14.43{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Social Studies (History, Government)”
  • 17.35{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Science (Biology, Chemistry)”


State by state results are available: NFEC Survey: “Should High Schools Require Financial Literacy?” 


NFEC. (2017). Financial Literacy Subject Survey. [online] Available at: https://www.financialeducatorscouncil.org/Financial-literacy-subject-survey/


f) A review of youth financial education: Effects and Evidence

“This report reviews current research and reporting in the field, and is intended to inform policymakers, practitioners, financial educators, and researchers of the current state of rigorous evidence on financial education in schools”… “This report features studies that (1) evaluate youth financial education programs in schools, (2) have a causal interpretation evidenced by a randomized controlled trial, natural experiment setting, or a valid pre-post study design, and (3) have been published in peer-reviewed academic journals or as reviewed working papers. Note that the studies predominantly relate to school based programs, as this is the context in which most youth financial education research has occurred.”

  • “Well-implemented state financial education mandates led to a clear improvement in financial behaviors.”
  • “Many U.S. financial education programs improve financial knowledge for students, though effect sizes vary based on the population served, amount of instruction time, and topics covered.”
  • “Other countries have used more widespread randomized controlled trials to study the effects of programs as they embed and expand them broadly. Those studies also provide useful information.”
  • Consumer Financial Protection Bureau. (2019). A review of youth financial education: Effects and Evidence. [online] consumerfinance.gov. Available at: https://files.consumerfinance.gov/f/documents/cfpb_youth-financial-education_lit-review.pdf


g) Digital vs. in-person financial education: What works best for Generation Z?

“Nowadays, financial literacy is one of the most important skills that can be acquired by a tech-savvy Generation Z student. In order to understand what format of financial education works best for Generation Z, we set up an experiment that involved implementing a financial education program called “Futuro Sicuro” with a sample of 650 High School students in Italy. The program allowed us to gather data from two treatments at the class level, namely 1) a traditional financial education simplified program with the presence of a financial advisor, and 2) a digital financial education program using web-based applications based on learning-by-playing concepts. The two treatments were associated with different costs but showed similar effects: three weeks after their conclusion, we find that both courses did increase actual financial knowledge and the results also aligned with participants’ realistic assessments of their own financial skills. A follow-up study also reveals the persistence of these effects three months later for the traditional course.”


h) Best Practices Implementing Financial Education in High Schools

“…breaks the implementation into eight stages: (0) building a coalition, (1) crafting and passing either legislation or administrative rule change, (2) constructing an implementation plan, (3) funding, (4) teacher professional development, (5) developing standards and selecting course resources, (6) teacher endorsement models, and (7) auditing and creating a feedback loop for continuous improvement.”

Urban, Carly (2022). Best Practices Implementing Financial Education in High Schools [online] Available at: https://papers.carlyurban.com/MTBestPracticesReportFINAL.pdf

California High Schoolers to Learn Insurance Under Mandatory Finance Education Bill

California High Schoolers to Learn Insurance Under Mandatory Finance Education Bill
New You can now pay attention to Coverage Journal content articles!

How a lot of older people not in the coverage market can describe the dangers financial loss and how coverage shares that chance, or identify components impacting coverage rates and grasp the romance between premiums, deductibles, and coverage boundaries?

How several can condition how the insurers use risk pooling and math to deliver insurance plan coverage and make a gain?

There are no specific solutions to people inquiries – all those within the marketplace may well have justifiably guessed “too several.” Nonetheless, 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of all large college pupils in the U.S. may possibly shortly be equipped to tackle these inquiries.

A new bill released in California would include a one particular-semester course in private finance to large school graduation prerequisites starting up with pupils graduating in the 2028–29 faculty yr.

Assembly Bill 984, released by Assemblymember Kevin McCarty, D-Sacramento, very last week would require community instructional companies as perfectly as constitution educational institutions to provide a personalized finance system starting off in the 2025–26 school calendar year, fundamentally imposing a condition-mandated regional plan.

The state is the most up-to-date in a drive to get all states to adopt such a mandate, a push that is observing great success.

AB 984 would deliver California in line with 17 other states now demanding a personal finance class. According to the team backing the bill, the selection of states where by a personal finance class is section of the necessary substantial college curriculum has nearly doubled in two yrs.

At the moment, one particular-in-4 U.S. higher college pupils is demanded to acquire a particular finance training course. Incorporating California’s extra than 1.7 million students to the number of pupils in states exactly where a own finance system is required would signify approximately 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} the nation’s high faculty college students will be getting the class.

Some universities already involve personal finance as part of other classes, typically economics. But the importance and breath of individual finance – controlling or keeping away from financial debt, preserving for the long term, danger management, insurance policy – are far too weighty to be crammed in with broader matters, says the head of a team driving the invoice.

“We believe that that a semester class is the bare minimum that college students want,” reported Tim Ranzetta, co-founder of Up coming Gen Particular Finance, a Palo Alto, California-centered nonprofit that delivers cost-free curriculum and expert advancement for personalized finance academics in every point out.

In accordance to the team, which is pushing for a certain, total-semester, standalone particular finance course for every single U.S. superior schooler, there are equivalent expenditures in 21 other states.

The group created a detailed guideline curriculum that breaks down models and contains interactive assets.

A sizable area of the curriculum is committed to insurance coverage lessons. People units incorporate an introduction to insurance policies, classes on danger management and threat protection procedures, and a phase on auto coverage that outlines deductibles, aspects that ascertain rates, and how to pick an acceptable stage of motor vehicle insurance policies.

A renters and owners insurance policies section handles studying a rental insurance coverage agreement, the price of house insurance, and knowledge which perils are covered and excluded in a plan.

Prolonged-time period incapacity, overall health coverage, and everyday living insurance are other insurance policies-connected segments in the guideline training course.

The course also covers kinds of credit and controlling credit history, preserving and budgeting, investing, shopper capabilities and taxes.

Up coming Gen Private Finance reports education about 15,000 instructors to instruct the program in the previous three yrs.

In accordance to Ranzetta, there’s broad aid among the Californians for producing private finance a required course. A poll by the group demonstrates 85{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of California older people support getting the study course as a prerequisite.

The bill would also place the condition on track to capture up with other states.

In accordance to Subsequent Gen Personal Finance, 70{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of significant faculty college students on other states show up at a college that delivers a individual finance class as an elective or a necessity. Only 25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of California significant schoolers attend a faculty wherever a personalized finance study course is made available, the group claims.

The bill was launched on Feb. 15 and is tentatively established to be taken up in committee on March 18.

Subjects
California
Teaching Progress

Fascinated in Schooling Enhancement?

Get computerized alerts for this subject.

What Is Financial Abuse and What to Do About It

What Is Financial Abuse and What to Do About It

When fiscal abuse influences the two gentlemen and ladies, women of all ages are a lot more frequently the victims. According to the Bureau of Justice Studies, 85{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of domestic violence victims are women of all ages (opens in new tab), and regrettably, the selection of incidents is rising. The latest studies about abuse for the duration of the pandemic are worrisome, exhibiting a spike in 911 phone calls reporting violence versus ladies (opens in new tab). States these as New York observed that domestic violence reports were up in excess of 30{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} (opens in new tab) in April 2020, in contrast to the year in advance of. 

According to UN Gals, one in a few gals around the globe activities actual physical or sexual abuse (opens in new tab), generally inflicted on them by a passionate partner. Moreover, given that the outbreak of COVID-19, UN Gals shares that rising data demonstrates that domestic violence has intensified and is not going absent. In reality, thanks to growing money pressure and mental well being troubles, numerous households remain at an elevated possibility for domestic violence (opens in new tab).