Apple loans Globalstar $252 million for satellite purchases | Business News

Apple loans Globalstar $252 million for satellite purchases | Business News

Apple will loan Globalstar $252 million to support the Covington firm acquire a fleet of satellites that will empower satellite communications on iPhones, federal regulatory filings exhibit.

Globalstar, a satellite technological know-how provider, introduced in September it experienced been tapped to provide the community for a new emergency SOS function on iPhones. The services allows Iphone 14 customers to deliver messages above satellites if they are in rural or remote locations significantly away from cell towers.

In advance of that partnership was formally unveiled, Globalstar said in February 2022 it struck an agreement with Canadian enterprise Macdonald, Dettwiler and Associates Corp. to acquire 17 satellites for $327 million and start them by 2025. That offer aided World “replenish” its existing satellite fleet, in accordance to Securities and Trade Fee filings.

The $252 million mortgage from Apple will assist finance that satellite invest in, Globalstar said in SEC filings. Globalstar will go over the remaining cost by means of its running income flows.

The mortgage was part of an update to the primary deal the two sides struck in 2020 when they began discovering the partnership. As section of that deal, Apple had already despatched Globalstar two different payments of $37.5 million in 2021 prior to the satellite provider released in November.

Below their partnership, Apple agreed to pay back 95{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the costs Globalstar will incur in launching new satellites to make out the network. Apple has mentioned a “majority” of the $450 million it invested to make out the essential infrastructure for the satellite aspect went to Globalstar.

Globalstar experienced claimed it would raise funds to deal with the value of making and launching the satellites. However, the newest loan “replaces the Company’s prerequisite to elevate third-party financing for these kinds of costs,” Globalstar’s SEC filings stated.

Apple will bank loan the funds on a quarterly foundation. Globalstar will have to repay it in 16 quarterly installments starting no later on than the 3rd quarter of 2025.

As a ailment of the loan, Globalstar will have to refinance other loans it took out in 2019 by March 13 and give Apple a “first-priority lien” on its belongings, SEC filings claimed. The harmony on the financial loans was $143 million as of Dec. 31.

The Apple partnership accounted for 24{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Globalstar’s a lot more than $148.5 million in earnings in 2022, SEC filings demonstrate. No other purchaser made up far more than 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Globalstar’s complete fees in 2022 were $369.5 million, together with a $166.5 million depreciation of “long-lived assets”, these types of as some of the firm’s satellite phones, in accordance to its annual report. Its running bills ended up $189.8 million in 2021.

Good news: Personal loan interest rates fall for 3-year fixed-rate loans

Good news: Personal loan interest rates fall for 3-year fixed-rate loans

Our goal here at Credible Operations, Inc., NMLS Number 1681276, referred to as “Credible” below, is to give you the tools and confidence you need to improve your finances. Although we do promote products from our partner lenders who compensate us for our services, all opinions are our own.

The latest trends in interest rates for personal loans from the Credible marketplace, updated weekly. (iStock)

Borrowers with good credit seeking personal loans during the past seven days prequalified for rates that were lower for 3-year loans and higher for 5-year loans compared to the previous seven days.

For borrowers with credit scores of 720 or higher who used the Credible marketplace to select a lender between Feb. 23 and Mar. 1:

  • Rates on 3-year fixed-rate loans averaged 11.71{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, down from 11.88{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} the previous seven days and up from 10.51{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} a year ago.
  • Rates on 5-year fixed-rate loans averaged 15.32{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, up from 15.04{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} over the previous seven days and up from 13.05{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} a year ago.

Personal loans have become a popular way to consolidate and pay off credit card debt and other loans. They can also be used to cover unexpected expenses like medical bills, take care of a major purchase or fund home improvement projects.

Personal loan interest rates rose over the last seven days for 5-year fixed-rate loans, while rates 3-year loans edged down. Rates for 3-year loans fell 0.17 percentage points, while rates for 5-year loans climbed 0.28 percentage points. In addition to this week’s rate changes, interest rates for both loan terms remain higher than they were this time last year. Still, borrowers can take advantage of interest savings with a 5-year personal loan right now. Both loan terms offer interest rates that are much lower than higher-cost borrowing options such as credit cards. 

Whether a personal loan is right for you often depends on multiple factors, including what rate you can qualify for. Comparing multiple lenders and their rates could help ensure you get the best possible personal loan for your needs. 

It’s always a good idea to comparison shop on sites like Credible to understand how much you qualify for and choose the best option for you.

Here are the latest trends in personal loan interest rates from the Credible marketplace, updated weekly.  

Personal loan weekly rates trends

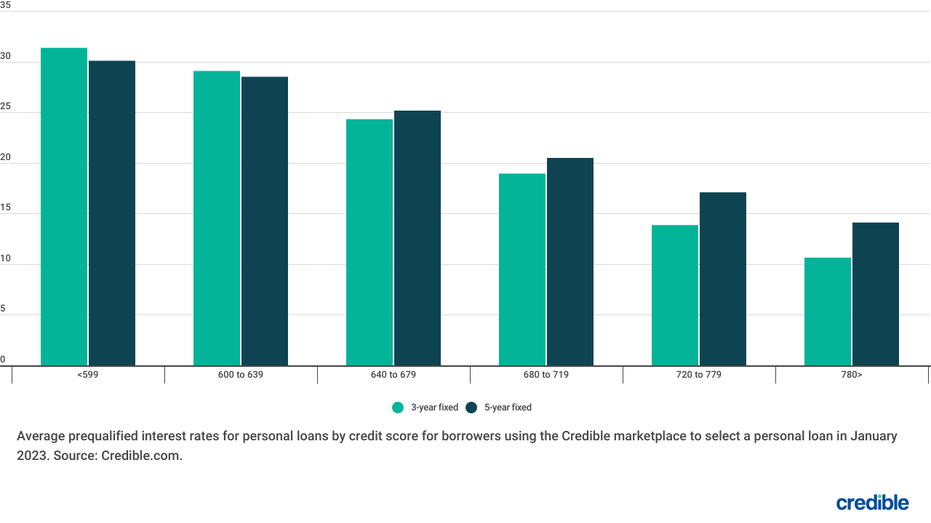
The chart above shows average prequalified rates for borrowers with credit scores of 720 or higher who used the Credible marketplace to select a lender. 

For the month of January 2023:

  • Rates on 3-year personal loans averaged 12.51{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, down from 13.03{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in December.
  • Rates on 5-year personal loans averaged 15.68{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, down from 17.21{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in December.

Rates on personal loans vary considerably by credit score and loan term. If you’re curious about what kind of personal loan rates you may qualify for, you can use an online tool like Credible to compare options from different private lenders. Checking your rates won’t affect your credit score.

All Credible marketplace lenders offer fixed-rate loans at competitive rates. Because lenders use different methods to evaluate borrowers, it’s a good idea to request personal loan rates from multiple lenders so you can compare your options.

Current personal loan rates by credit score

In January, the average prequalified rate selected by borrowers was: 

  • 10.63{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for borrowers with credit scores of 780 or above choosing a 3-year loan
  • 30.07{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for borrowers with credit scores below 600 choosing a 5-year loan

Depending on factors such as your credit score, which type of personal loan you’re seeking and the loan repayment term, the interest rate can differ. 

As shown in the chart above, a good credit score can mean a lower interest rate, and rates tend to be higher on loans with fixed interest rates and longer repayment terms. 

How to get a lower interest rate

Many factors influence the interest rate a lender might offer you on a personal loan. But you can take some steps to boost your chances of getting a lower interest rate. Here are some tactics to try.

Increase credit score

Generally, people with higher credit scores qualify for lower interest rates. Steps that can help you improve your credit score over time include:

  • Pay bills on time. Payment history is the most important factor in your credit score. Pay all your bills on time for the amount due.
  • Check your credit report. Look at your credit report to ensure there are no errors on it. If you find errors, dispute them with the credit bureau.
  • Lower your credit utilization ratio. Paying down credit card debt can improve this important credit-scoring factor.
  • Avoid opening new credit accounts. Only apply for and open credit accounts you actually need. Too many hard inquiries on your credit report in a short amount of time could lower your credit score.

Choose a shorter loan term

Personal loan repayment terms can vary from one to several years. Generally, shorter terms come with lower interest rates, since the lender’s money is at risk for a shorter period of time.

If your financial situation allows, applying for a shorter term could help you score a lower interest rate. Keep in mind the shorter term doesn’t just benefit the lender – by choosing a shorter repayment term, you’ll pay less interest over the life of the loan.

Get a cosigner

You may be familiar with the concept of a cosigner if you have student loans. If your credit isn’t good enough to qualify for the best personal loan interest rates, finding a cosigner with good credit could help you secure a lower interest rate.

Just remember, if you default on the loan, your cosigner will be on the hook to repay it. And cosigning for a loan could also affect their credit score.

Compare rates from different lenders

Before applying for a personal loan, it’s a good idea to shop around and compare offers from several different lenders to get the lowest rates. Online lenders typically offer the most competitive rates – and can be quicker to disburse your loan than a brick-and-mortar establishment. 

But don’t worry, comparing rates and terms doesn’t have to be a time-consuming process.

Credible makes it easy. Just enter how much you want to borrow and you’ll be able to compare multiple lenders to choose the one that makes the most sense for you.

About Credible

Credible is a multi-lender marketplace that empowers consumers to discover financial products that are the best fit for their unique circumstances. Credible’s integrations with leading lenders and credit bureaus allow consumers to quickly compare accurate, personalized loan options – without putting their personal information at risk or affecting their credit score. The Credible marketplace provides an unrivaled customer experience, as reflected by over 4,500 positive Trustpilot reviews and a TrustScore of 4.7/5.

Broward man gets 6 years for bilking millions from fed

Broward man gets 6 years for bilking millions from fed

Broward

Valesky Barosy, 28, pictured right here on his Instagram web site, was convicted of fraudulently acquiring pandemic-aid loans to invest in a Lamborghini, amongst other luxury goods.

– Instagram

A Broward County man convicted of buying a Lamborghini and other luxury goods with $2 million in U.S. government loans meant for struggling businesses during the pandemic was sentenced Wednesday to six years in prison and ordered to pay back the money.

Valesky Barosy, 28, who dropped out of high school and became president of a company known as VBarosySolutions Inc., was found guilty in December of wire fraud, money laundering and identity theft by a Fort Lauderdale federal jury in a rare COVID-19 loan scheme case that went to trial.

For various loan applications totaling more than $4 million, Barosy fabricated prior-year business expenses, net profits, and employee payrolls, and submitted bogus IRS tax forms to secure the payments for himself and other people, according to an indictment and trial evidence. He then used the tainted money to buy the Lamborghini, fancy watches and designer clothes.

Barosy’s defense attorney, Omar Lopez, tried to downplay the “sophisticated, complex and intricate” nature of his scheme to rip off the Small Business Administration’s Paycheck Protection Program — factors that affected his punishment before U.S. District Judge Rodney Smith. Lopez noted that the PPP loans were processed by a bank, and Barosy received the proceeds either directly into his account or as commissions from other applicants whom he represented in the scheme.

“All that it took was the issuing of subpoenas [by federal agents] to the bank that did business with Mr. Barosy,” Lopez wrote in court papers. “Once the government received the bank records, it was evident that Mr. Barosy received wire transfers from the individuals who received PPP loans and then used that money to purchase watches, make a down payment on a sports car and purchase luxury handbags.”

Barosy showed off his exploits while stealing from the SBA’s Paycheck Protection Program, posting social media shots of himself driving an exotic Lamborghini and flying on a private jet. He boasted an Instagram account with over 110,000 followers.

He touted himself as an immigrant success story, arriving from Haiti a decade ago, working his way up from a menial job at Walmart to “regional vice president” of a credit repair company that purportedly racked up “$3.6 million in sales,” according to court records. He also started his own exotic car washing business, records show.

On Instagram, Barosy posed often with the white Lambo, pitching himself as an inspiring mentor. “It’s not the Lamborghini or the million dollar home that will inspire the world but the trials and tribulations you overcame,” Barosy, who was born in Haiti and immigrated to South Florida as a teen, wrote in one post.

But in reality, prosecutors with the U.S. Attorney’s Office said, Barosy was fleecing taxpayers — fraudulently securing $2 million in loans from the PPP system to buy classic Miami status symbols: a Lamborghini Huracán EVO, Rolex and Hublot watches, and designer clothing from Louis Vuitton, Gucci and Chanel. The U.S. will seize those items.

The Paycheck Protection Program was approved by Congress in 2020 to help businesses decimated following shutdowns caused by the rapid spread of the COVID-19 virus. The program allowed for the loans to be forgiven, if borrowers followed criteria laid out by the Small Business Administration. Hundreds of billions of dollars in emergency loans were distributed during the pandemic, but fraud quickly surfaced as a serious problem across the country.

As the nation’s No. 1 fraud capital, South Florida has led the financial crime wave that followed the passage of the CARES Act, according to the U.S. Attorney’s Office.

In South Florida, that’s included a businessman using PPP money to buy a $318,000 Lamborghini, a nurse alleged to have lied about his business to get $474,000 that was used in part to pay a Mercedes-Benz lease and child support, and a North Miami suburban couple that claimed to be farmers to qualify for $1 million in relief benefits.

Around the same time that Barosy was arrested in December 2021, two Florida men pleaded guilty to helping arrange over $35 million in PPP loans. The ring also netted the conviction of former NFL player Joshua Bellamy, who was sentenced to more than three years in prison for wire-fraud conspiracy.

Valesky 3.jpg
Valesky Barosy, pictured in this article on his Instagram web site, was sentenced to 6 decades in prison for fraudulently getting pandemic-relief loans to obtain a Lamborghini, amid other luxury merchandise. He was also requested to shell out back again the dollars. – Instagram

This story was originally posted March 1, 2023, 12:30 PM.

Profile Image of Jay Weaver

Jay Weaver writes about federal crime at the crossroads of South Florida and Latin The united states. Considering the fact that joining the Miami Herald in 1999, he’s coated the federal courts nonstop, from Elian’s custody fight to A-Rod’s steroid abuse. He was element of the Herald workforce that won the 2001 Pulitzer Prize for breaking information on Elian’s seizure by federal agents. He and a few Herald colleagues ended up 2019 Pulitzer Prize finalists for explanatory reporting for a sequence on gold smuggling among South The united states and Miami.

Opinion: Who’s stopping the government from giving Americans relief from crushing student loans

Opinion: Who’s stopping the government from giving Americans relief from crushing student loans

Editor’s Note: Jill Filipovic is a journalist based mostly in New York and author of the ebook “Ok Boomer, Let’s Communicate: How My Era Received Still left Behind.” Adhere to her on Twitter. The views expressed in this commentary are entirely her personal. Look at far more belief on CNN.


CNN
 — 

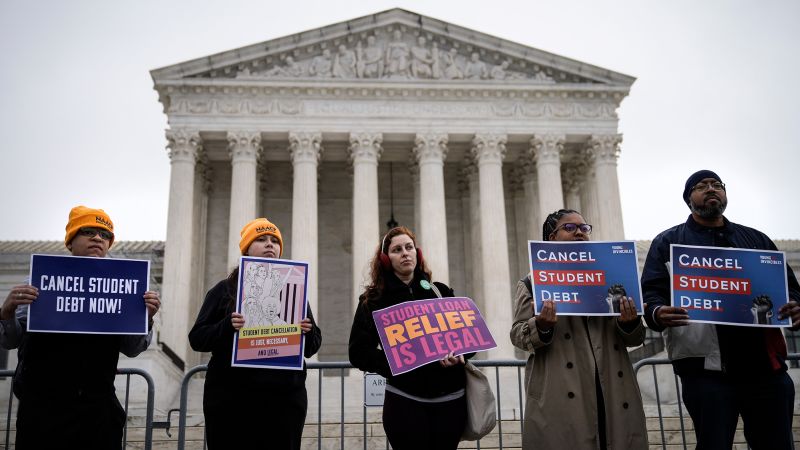
President Joe Biden is hoping to give the thousands and thousands of Us residents saddled with college student financial loan debt some aid. Republicans, and the Supreme Court docket, may possibly not allow him.

Immediately after Biden took business final calendar year, his administration declared a strategy to discharge hundreds of thousands and thousands of pounds in student loans in a plan that would forgive as substantially as $20,000 for every borrower. Biden did this thanks to the Increased Schooling Reduction Alternatives for Learners Act of 2003, or the HEROES Act, which lets the secretary of education to modify or get rid of scholar personal debt in the context of “a war or other military procedure or national emergency.”

Jill Filipovic

A pandemic is clearly a nationwide emergency, a position previous President Donald Trump also took when he paused university student financial debt payments in 2020. Biden expanded on that, placing loans again into compensation starting in July, but also placing ahead a prepare to forgive relatively than just pause at minimum some debt.

Several of the extra than 43 million People saddled with some $1.75 trillion dollars in pupil debt ended up thrilled. Numerous Republicans cried foul.

6 Republican governors and two debt holders filed lawsuits hard the plan. Their argument is basically that this method is further than the scope of Biden’s power he’s making use of Covid as a pretext, they say, for a law that ought to be authorised by Congress. On this position – and in a great deal of the situation – the Court’s conservative justices appeared sympathetic during Tuesday’s oral arguments in the two issues to Biden’s system. The situation “presents extraordinarily serious critical issues about the purpose of Congress,” Main Justice John Roberts explained, incorporating, “We take pretty significantly the strategy of separation of powers and that ability really should be divided to reduce its abuse.”

He has a point: The US authorities was without a doubt established up to different and balance powers, and to steer clear of unilateral government action – the Founders gave us a president, not a king.

But Congress also gave us the HEROES Act, which explicitly provides the president the authority to cancel student financial debt in the circumstance of a nationwide unexpected emergency. The pandemic was plainly a nationwide unexpected emergency. There are often a large amount of “really confusing” statutes that appear just before the Court docket, Justice Elena Kagan said, and “this is not just one.” Clearly, Congress supposed for the president to have the electricity to waive pupil debt in a national unexpected emergency can it definitely be the circumstance that the president was offered that power, but he’s not permitted to use it devoid of Congress weighing in?

The conservative judges feel to say certainly.

This is a situation that may slide apart right before the judges even get to the actual meat of it, many thanks to standing challenges with the plaintiffs. In order for a court to hear a case like this one particular, the men and women or entities suing have to have experienced some real harm – they simply cannot just dislike a law or coverage, they have to be negatively impacted by it. The Courtroom will initially have to take into account if the Republican governors who are suing have satisfied the threshold to sue in the initial area.

Whichever the result, this case will be a political acquire for the Biden administration. The optics are clear: Democrats want to forgive your college student financial loans Republicans are prepared to go all the way to the Supreme Courtroom to quit them.

If the Republican governors earn, however, and the university student loan forgiveness software is scrapped, the serious losers will be indebted former learners, not the GOP.

Pupil personal loan personal debt is crushing, and it has exploded in the previous few a long time. According to the Education Knowledge Initiative, even though the normal borrower usually takes out $30,000 in financial loans to shell out for a bachelor’s diploma, the average federal debt owed is extra than $37,500, and the ordinary non-public pupil mortgage personal debt is a whopping $54,921.

And all credit card debt is not made equal. Learners who choose out loans to get, say, enterprise degrees from top rated universities obtain them selves in a extremely different situation from learners who attend predatory for-profit establishments and wind up with degrees that are not truly worth all that a lot – if they conclusion up with levels at all. A terrific several students who take out student loans do not graduate, leaving them in the worst of all positions: In personal debt, but with no degree to clearly show for it.

These pupils – those who are indebted but really don’t have a diploma – are normally susceptible in numerous other strategies. Debtors who default on their loans are a lot much more probable than learners who graduate to be initially-technology higher education learners, to be Black or Hispanic, to have attended a for-gain faculty, and to have under no circumstances done their diploma.

Though Biden’s mortgage forgiveness system would advantage numerous men and women with scholar loan debt – myself incorporated – it is the debtors who in no way graduated or who went to predatory institutions that are at the moment becoming damage the worst, and would see the greatest reward by getting a chunk of their financial debt knocked off.

Struggling with pupil financial debt – or worse, defaulting and looking at your total monetary lifestyle consider a enormous strike – is part of what keeps so many Individuals living in a condition of precarity. Millennials, the oldest of whom are now in our 40s, have been notoriously unwilling to have little ones, late to marry, and unable to conserve for residences. Pupil debt isn’t the only driver of these shifts – substantially of it is cultural as substantially as financial – but starting your grownup everyday living owing tens or hundreds of hundreds of bucks does not exactly generate a steady foundation on which to develop a existence.

To add insult to injuries, an 18-12 months-aged who used four decades racking up credit rating card credit card debt acquiring luxury cars, putting on designer apparel and likely on unique vacations can discharge that financial debt in bankruptcy. An 18-calendar year-previous who signed a $100,000 mortgage arrangement at 7.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} fascination because it was their only way to pay out for college are unable to.

The Biden pupil financial loan forgiveness system is considerably from ideal. It does not do practically enough to be certain that we are not heading to be ideal again listed here a couple yrs down the street. It is arguably not generous sufficient to the most in have to have and way too generous to the white-collar experts who can afford to shell out off their financial loans. And liberals need to have authentic concerns about government overreach.

But we really should be involved about overreach from a conservative Supreme Court docket, as well, as effectively as a college student loan technique that destinations significant economic burdens on youthful individuals as quickly as they embark on their grownup life.

The Republican talking level on this situation is that Biden’s system is a enormous taxpayer giveaway, and that he cunningly employed Covid as an justification to thrust by a coverage Congress would have in no way authorized. So it is truly worth asking Republican politicians: Why won’t Congress act to relieve scholar financial loan financial debt — even if it usually means producing the uber-wealthy and huge firms pay out much more in taxes — and strengthen the economic and individual futures of so quite a few youthful people?

The GOP opposes Biden’s college student personal debt reduction prepare, and associates of the party are so from it that they are willing to choose it all the way to the Supreme Court. Voters like me, who even now have significant college student financial debt that has very a great deal impacted my economical wellbeing and curtailed my means to help you save for minimal points like at any time becoming ready to retire, want solutions from the GOP: If you are prepared to struggle college student mortgage forgiveness in front of the Supreme Court, why are not you eager to battle for the tens of millions of Us citizens who are currently being crushed by the credit card debt we necessary to choose on to get our levels?
Student loan forgiveness Supreme Court hearing, explained

Student loan forgiveness Supreme Court hearing, explained

WASHINGTON (AP) — The Supreme Courtroom is about to listen to arguments around President Joe Biden’s scholar personal debt reduction approach, which impacts thousands and thousands of debtors who could see their loans wiped away or minimized.

So much, Republican-appointed judges have kept the Democratic president’s strategy from going into impact, and it continues to be to be found how the courtroom, dominated 6-3 by conservatives, will answer. The justices have scheduled two hours of arguments in the case Tuesday, nevertheless it will probably go for a longer time. The public can hear in on the court’s web page commencing at 10 a.m. EST.

Where by items stand in advance of the hearing as perfectly as what to be expecting:

HOW DOES THE FORGIVENESS Strategy Operate?

The financial debt forgiveness approach announced in August would cancel $10,000 in federal pupil bank loan financial debt for individuals making much less than $125,000 or homes with a lot less than $250,000 in profits for each year. Pell Grant recipients, who usually reveal far more money need, would get an added $10,000 in credit card debt forgiven.

Higher education learners qualify if their financial loans have been disbursed prior to July 1. The system tends to make 43 million borrowers eligible for some financial debt forgiveness, with 20 million who could have their credit card debt erased entirely, in accordance to the Biden administration.

The White Residence states 26 million people have used for financial debt reduction, and 16 million folks experienced currently had their reduction accepted. The Congressional Finances Business has claimed the program will price about $400 billion around the up coming a few a long time.

HOW DID THE Concern WIND UP AT THE SUPREME Court?

The Supreme Courtroom is hearing two challenges to the prepare. Just one involves 6 Republican-led states that sued. The other requires a lawsuit filed by two college students.

A lower court docket dismissed the lawsuit involving the pursuing states: Arkansas, Iowa, Kansas, Missouri, Nebraska and South Carolina. The court explained the states could not challenge the application because they weren’t harmed by it. But a panel of a few federal appeals court docket judges on the U.S. Court docket of Appeals for the 8th Circuit — all of them appointed by Republican presidents — set the plan on keep during an enchantment. The Supreme Court then agreed to weigh in.

The students’ circumstance includes Myra Brown, who is ineligible for personal debt reduction for the reason that her loans are commercially held, and Alexander Taylor, who is qualified for just $10,000 and not the total $20,000 mainly because he didn’t receive a Pell grant. They say that the Biden administration didn’t go via the right procedure in enacting the strategy, amongst other matters.

Texas-primarily based U.S. District Judge Mark Pittman, an appointee of President Donald Trump, sided with the learners and dominated to block the application. Pittman dominated that the Biden administration did not have apparent authorization from Congress to put into action the plan. A federal appeals court docket still left Pittman’s ruling in place, and the Supreme Court docket agreed to take up the circumstance along with the states’ challenge.

HOW DID BIDEN GET TO Terminate THE Credit card debt?

To terminate college student personal loan personal debt, the Biden administration relied on the Greater Education and learning Aid Prospects for Learners Act, generally acknowledged as the HEROES Act. Initially enacted soon after the Sept. 11, 2001, terror attack, the regulation was at first supposed to keep provider customers from being worse off fiscally although they fought in wars in Afghanistan and Iraq. Now prolonged, it enables the secretary of schooling to waive or modify the conditions of federal college student financial loans as necessary in connection with a countrywide crisis.

Trump, a Republican, declared the COVID-19 pandemic a national unexpected emergency in March 2020, but Biden not long ago introduced that designation will close May 11. The Biden administration has stated that the close to the nationwide crisis does not change the legal argument for student bank loan personal debt cancellation for the reason that the pandemic impacted tens of millions of scholar borrowers who may have fallen driving on their financial loans all through the unexpected emergency.

WHAT ARE THE JUSTICES Most likely TO Inquire ABOUT?

Expect the justices to be focused on many significant challenges. The first a person is whether the states and the two borrowers have the correct to sue in excess of the plan in the to start with put, a authorized notion identified as “standing.” If they really don’t, that clears the way for the Biden administration to go forward with it. To verify they have standing, the states and debtors will have to show in section that they’re economically harmed by the approach.

Beyond standing, the justices will also be inquiring no matter if the HEROES Act offers the Biden administration the energy to enact the strategy and how it went about doing so.

WHEN WILL Borrowers KNOW THE Consequence?

It will possible be months ahead of debtors find out the outcome of the situation, but there’s a deadline of types. The court usually troubles all of its choices by the end of June right before likely on a summer months break.

Whether or not or not the credit card debt will get cancelled, the case’s resolution will deliver improvements. Whilst federal college student financial loan payments are now paused, that will conclude 60 times soon after the case is solved. And if the case hasn’t been resolved by June 30, payments will start out 60 days soon after that.

___

Abide by the AP’s coverage of the U.S. Supreme Courtroom at https://apnews.com/hub/us-supreme-court.

Supreme Court could axe Biden’s loan forgiveness but other paths exist

Supreme Court could axe Biden’s loan forgiveness but other paths exist

President Joe Biden’s student loan debt relief plan is teetering on the edge of a Supreme Court cliff. 

Other avenues for forgiving or winnowing student loan borrowers’ debt, however, are alive and well. There’s even a plan in the works to keep people from borrowing to attend a subpar school.

The administration has streamlined loan forgiveness for people who work in the public sector, canceled the debts of students taken advantage of by predatory colleges and universities and unveiled a new income-driven repayment plan that could reduce how much borrowers have to pay.

Together, these programs affect millions of borrowers, have led to billions in student loan debt being forgiven and could erase billions more. Most are meant to be long-term changes rather than a one-time fix.