Humana Leaving Commercial Business, Will Focus on Government-Funded Programs

Humana Leaving Commercial Business, Will Focus on Government-Funded Programs

Humana will move out of business plans over the next 18 to 24 months and concentration far more on federal government-funded applications and specialty businesses. Incorporated in the business enterprise Humana is leaving are all absolutely insured, self-funded, and Federal Staff Overall health Gains health care plans.

The business announced the move following a strategic evaluation that determined the Employer Group Commercial Health-related Items business was no extended in a place to “sustainable satisfy the demands of professional members more than the very long expression,” according to a push release.1

“This determination enables Humana to emphasis methods on our greatest options for development and exactly where we can deliver market main worth for our customers and shoppers,” Bruce D. Broussard, Humana’s president and CEO, said in a assertion. “It is in line with the company’s method to aim our well being plan choices mainly on govt-funded systems (Medicare, Medicaid and Army) and specialty businesses, though advancing our leadership situation in built-in price-based care and expanding our CenterWell well being treatment products and services abilities.”

In late 2022, Humana declared that it was increasing CenterWell, which offers payer-agnostic, senior-centered major treatment solutions. The prepare to increase CenterWell involves including new centers in Indiana, Kentucky, Louisiana, Mississippi, Nevada, North Carolina, South Carolina, Tennessee, Texas, and Virginia.2

As of September 30, 2022, Humana had 8.7 million Medicare customers in all 50 states, as very well as Washington, DC, and Puerto Rico. In addition, far more than half (5.1 million) of those members have been enrolled in a Medicare Edge (MA) program.3

The information of Humana’s move will come just days just after a new report highlighted the expansion of MA plans. Health care consulting group Chartis observed that whilst MA development experienced slowed this year in comparison with the 3 past many years, in general participation in the method continue to grew by 5.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, or an extra 1.5 million beneficiaries.4 There is now a report 29.5 million individuals enrolled in MA designs with 46{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of all Medicare beneficiaries enrolled in MA. In comparison, 37{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of all Medicare beneficiaries had been in MA ideas in 2019.

In the report, Humana was mentioned as a single of the drivers of MA progress. UnitedHealthcare led the way, accounting for 55{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of market growth, Chartis noted, followed by Humana, which accounted for 23{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of progress. From 2022 to 2023, Humana’s enrollment in MA grew 6.8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

“While these 2 overall health options generally led in several years previous, this improve demonstrates substantially additional concentrated overall performance,” according to the report.

Chartis also highlighted the great importance of CMS’ star rankings on enrollment. Well being programs with growing quality experienced enrollment gains and, all round, 73{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of MA beneficiaries are in health and fitness designs that have 4 stars or improved. Similarly, Humana claimed that 96{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of all of Humana’s MA users are enrolled in options that have 4 stars or above.5

The fact that MA options address additional rewards, like dental, vision, physical fitness memberships, and extra, make them extremely beautiful to Medicare beneficiaries and has contributed to the recognition and immediate advancement of these programs, Dennis Scanlon, PhD, professor of overall health coverage and administration, Pennsylvania Condition University, explained to The American Journal of Managed Treatment® in an job interview.

In spite of their recognition, there are downsides to MA options. Kaiser Spouse and children Foundation observed that in 2022, 99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of MA enrollees are in plans that have to have prior authorization for some expert services.6 Not only is PA generally essential for high-priced products and services, these types of as Portion B drugs and experienced nursing facility stays, but it is required for the vast majority of enrollees for some of all those added positive aspects, such as dental providers and hearing and eye examinations.

“In contrast to Medicare Advantage strategies, regular Medicare does not usually call for prior authorization for providers and does not need phase therapy for Section B medication,” the authors famous.

Reference

1. Humana to exit employer team commercial health care products business enterprise. News launch. Humana. February 23, 2023. https://press.humana.com/information/information-aspects/2023/Humana-to-Exit-Employer-Group-Professional-Health care-Goods-Enterprise/default.aspx

2. CenterWell senior key care 2023 enlargement program contains new markets of Indiana, Mississippi, and Virginia. News release. Humana. November 16, 2022. Accessed February 23, 2023. https://push.humana.com/information/news-specifics/2022/CenterWell-Senior-Principal-Care-2023-Enlargement-System-Involves-New-Markets-of-Indiana-Mississippi-and-Virginia/default.aspx

3. U.S. Information and Planet Report names Humana 2023 ideal total Medicare Benefit plan enterprise. News Release. Humana. November 10, 2022. Accessed February 23, 2023. https://press.humana.com/information/information-aspects/2022/U.S.-News-and-World-Report-names-Humana-2023-Most effective-General-Medicare-Edge-Plan-Organization/default.aspx

4. Herro N, Pathiyal A, Wokurka J. In a shifting sector, Medicare Advantage displays continued—but decelerating—growth. Chartis. February 21, 2023. Accessed February 23, 2023. https://www.chartis.com/insights/shifting-industry-medicare-gain-shows-continued-decelerating-progress

5. 96{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Humana’s Medicare Edge members are in contracts amount 4-star or previously mentioned for 2023 66{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} are in contracts rated 4.5-star or better. News release. Humana. Oct 7, 2022. Accessed February 23, 2023. https://press.humana.com/information/information-details/2022/96-of-Humanas-Medicare-Benefit-Associates-are-in-Contracts-rated-4-Star-or-Above-for-2023-66-are-in-Contracts-Rated-4.5-Star-or-Higher/default.aspx

6. Freed M, Fuglesten Biniek J, Damico A, Neuman T. Medicare Edge in 2022: rates, out-of-pocket limits, cost sharing, supplemental rewards, prior authorization, and star rankings. Kaiser Spouse and children Basis. August 25, 2022. Accessed February 23, 2023. https://www.kff.org/medicare/situation-transient/medicare-gain-in-2022-rates-out-of-pocket-boundaries-expense-sharing-supplemental-gains-prior-authorization-and-star-rankings/

XCPCNL Business Services Awarded $2M from Global Major Tech Company

XCPCNL Business Services Awarded M from Global Major Tech Company

CHARLOTTE, NC / ACCESSWIRE / February 23, 2023 / XCPCNL Enterprise Services Corporation (OTC Pink:XCPL), a enterprise improvement business that leverages awareness, skill, and expertise in the client goods field, is pleased to announce, it has been awarded a invest in order in the volume of $2 million from a huge tech enterprise.

The scope of get the job done for the acquire purchase contains material development for how adverts function, digital fraud, and monitoring narrative, IoT and app retail outlet principles, and enlargement of client advocate and developer network on coverage engagement, together with gatherings. This is a important milestone for XCPCNL Enterprise Providers, and the business is psyched to embark on this venture.

CEO Tim Matthews expressed his optimism and enjoyment about the purchase order, stating, “We are thrilled to have been awarded this buy order, and we glance forward to working with our partners to supply remarkable final results. This is a testomony to the hard function and devotion of our workforce, and we are confident that our expertise in SaaS and CaaS platforms will enable us to supply high-high quality methods to our partners.”

XCPCNL Enterprise Expert services is committed to partnering with visionary business people and supplying them with access to markets and consumers. The firm’s platforms are constructed on a strategic network of innovation ecosystem, company, and college interactions that assist their associates inform and accelerate go-to-current market methods.

For legality purposes, the title of this tech business simply cannot be described.

XCPCNL Organization Providers Corporation (OTC Pink: XCPL) encourages shareholders to take a look at their corporate Twitter account at https://twitter.com/RealXCPCNL.

Forward-Seeking Statements Disclaimer:

This press launch may perhaps contain, and oral statements manufactured from time to time by associates of the Corporation could involve “ahead-looking statements” within the this means of Portion 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Trade Act of 1934, as amended. Statements concerning possible business enterprise mixtures and the financing thereof, and associated matters, as perfectly as all other statements other than statements of historical truth involved in this push release, are forward-wanting statements. When made use of in this press release, words these types of as “anticipate,” “believe that,” “go on,” “could,” “estimate,” “hope,” “intend,” “may perhaps,” “may well,” “approach,” “achievable,” “potential,” “predict,” “project,” “ought to,” “would” and comparable expressions, as they relate to us or our management group, recognize forward-seeking statements. These kinds of forward-hunting statements are dependent on the beliefs of administration, as effectively as assumptions manufactured by, and details now out there to, the Firm’s administration. Precise effects could vary materially from people contemplated by the forward-searching statements as a end result of sure factors in-depth in the Firm’s filing with the In excess of the Counter Marketplace (“OTC”). All subsequent written or oral ahead-seeking statements attributable to us or folks performing on our behalf are certified in their entirety by this paragraph. Ahead-hunting statements are topic to many circumstances, numerous of which are beyond the control of the Organization. The Firm undertakes no obligation to update these statements for revisions or changes immediately after the date of this release, besides as demanded by regulation.

About XCPCNL:

Charlotte, NC-dependent XCPCNL Organization Companies is a undertaking growth small business that leverages its awareness, competencies, and working experience in the shopper solutions market. Our most important mission is to deliver advertising, technologies, and other organization companies to quick-developing buyer item organizations and significant-box shops. XCPCNL is a minority-owned and controlled agency.

To study more about our businesses, solutions, and prospects, be sure to speak to facts@xcpcnl.com.

To learn additional about XPCNL, pay a visit to www.xcpcnl.com.

For Inquiries:

Email: ir@xcpcnl.com

Supply: XCPCNL Organization Companies Corp.

View supply model on accesswire.com:
https://www.accesswire.com/740493/XCPCNL-Business enterprise-Services-Awarded-2M-from-Global-Major-Tech-Business

Bill would mandate teaching financial literacy | Local News

Bill would mandate teaching financial literacy | Local News

A new bill would require Vermont public university learners to take a own finance training course to graduate high school.

If the invoice, H.228, passes, the mandate will go into impact July 1 and utilize to all community large university college students graduating all through or after following university calendar year.

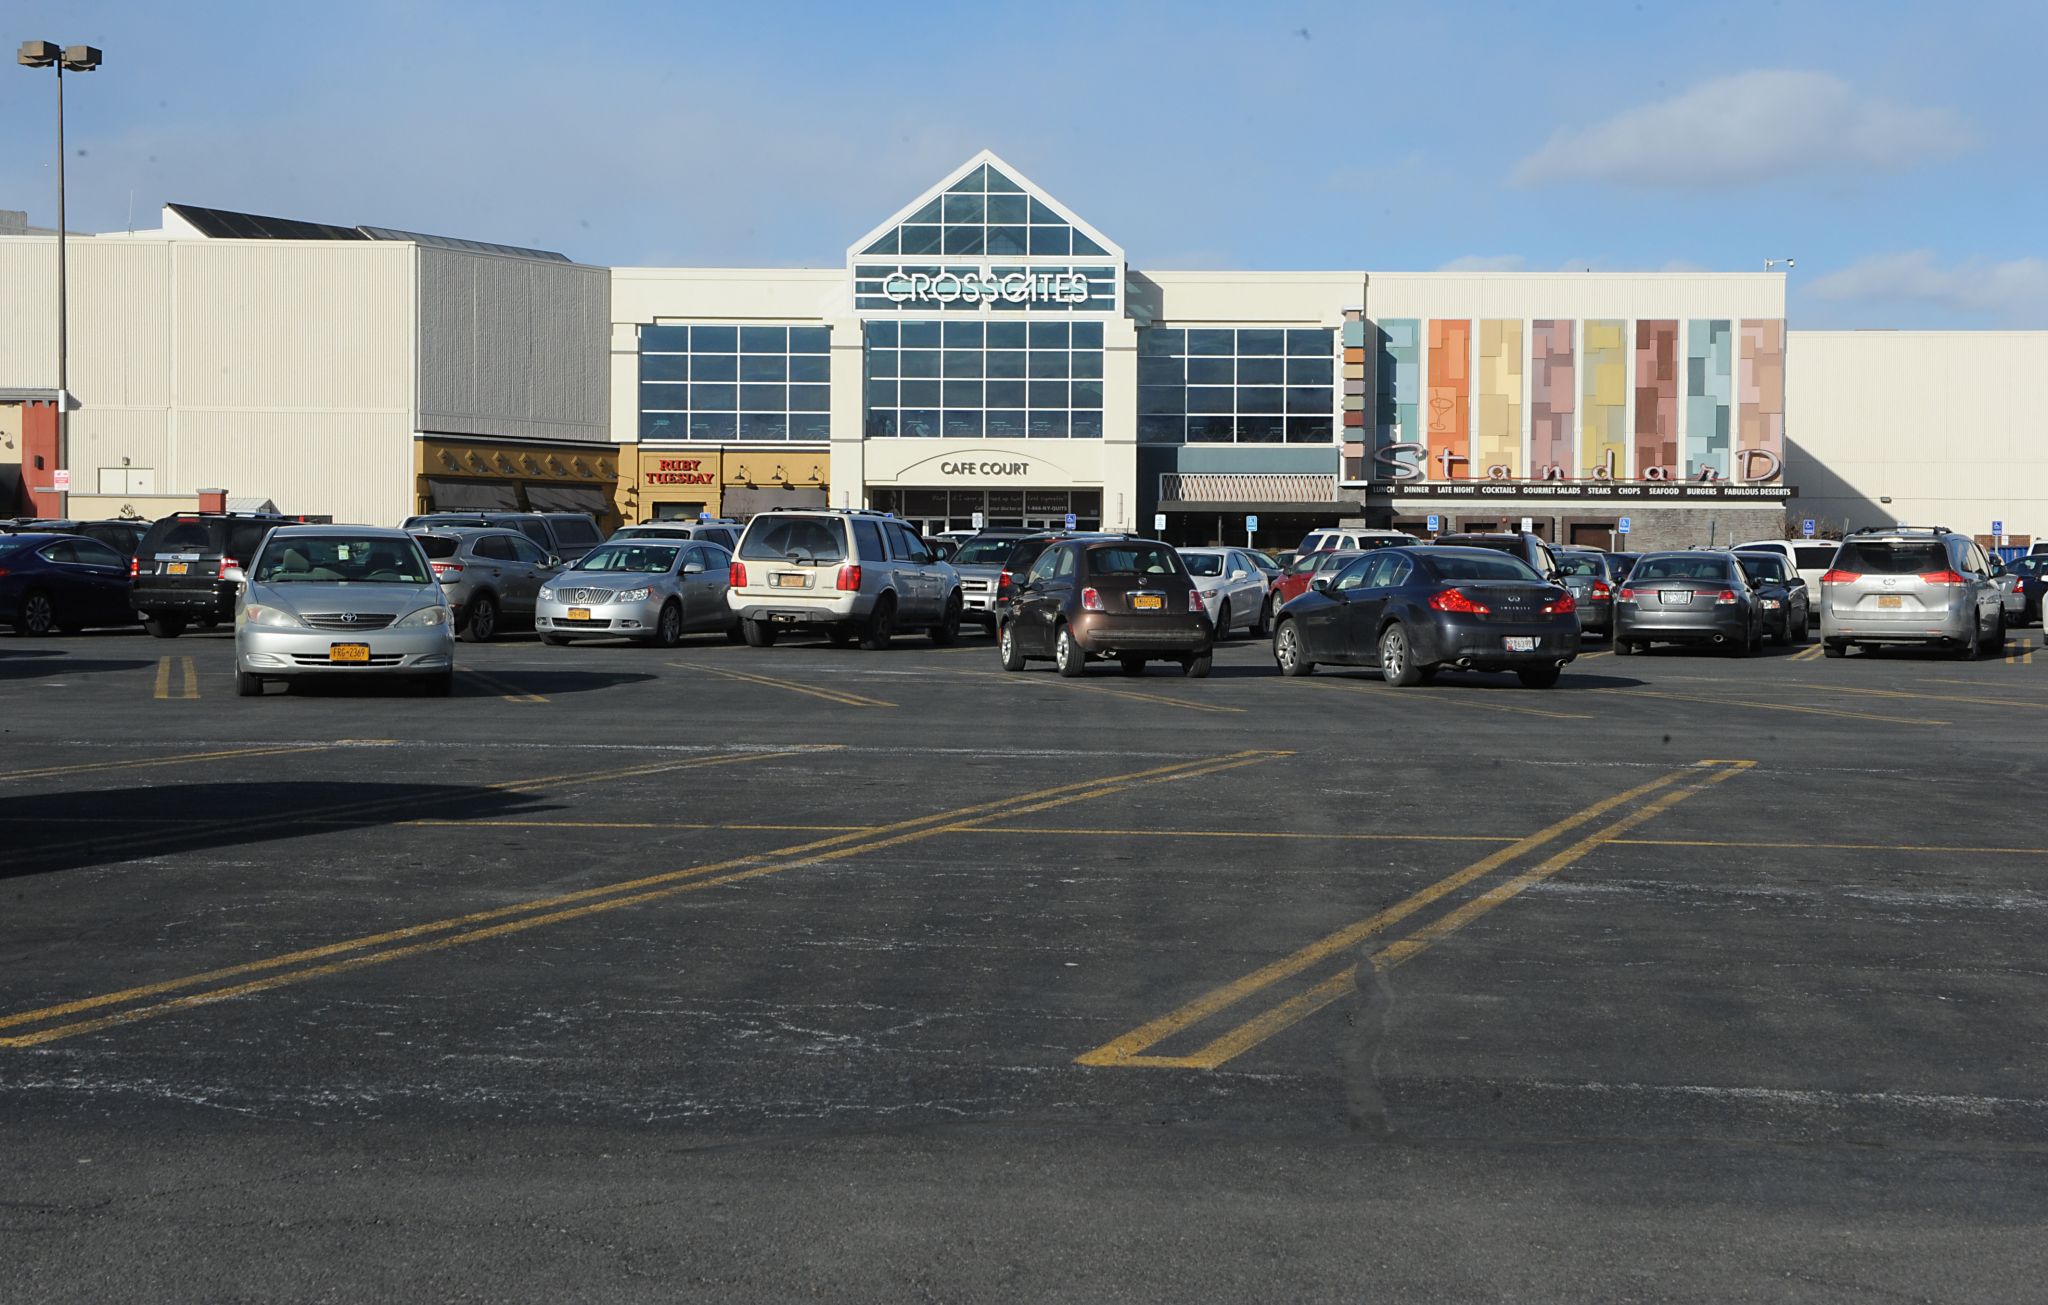
Pyramid’s Crossgates Mall loans lurch toward default

Pyramid’s Crossgates Mall loans lurch toward default

GUILDERLAND — Two loans valued at $157 million taken out by the proprietors of Crossgates Mall look to be headed once once more towards opportunity default amid the prevalent money issues facing big indoor browsing malls throughout the region.

The loans are thanks to be compensated off in whole in May well just after Crossgates was able to get a one-calendar year extension very last yr on the financial debt.

Bloomberg Information described that Trimont Genuine Estate Advisors of Atlanta was hired earlier this month to check out and salvage the mortgage and modify the phrases if necessary. A 3rd personal loan that Bloomberg says is valued at $88 million has not been designated for special servicing, Bloomberg mentioned.

Pyramid Management of Syracuse, which owns Crossgates and other malls across upstate, did not answer to a request for responses. The shopping mall has 1.7 million sq. toes of area.

Troubles with Pyramid’s home loans on malls it owns throughout upstate and elsewhere have been happening for several many years now just after the pandemic pressured many of its tenants into personal bankruptcy and pressured the mall to renegotiate leases, commonly at considerably reduce rents, of pretty much all of its tenants.

Scores organizations have been downgrading the credit history of debt securities backed by indoor shopping malls for decades now on slipping occupancy charges and rents.

Crossgates and other substantial indoor malls throughout the region had by now been dealing with a complicated retail ecosystem when traditional anchor shops like Macy’s fell out of favor with the general public amid the rise of convenient on the net buying made available by Amazon and some others.

As portion of that change, Crossgates and other malls had by now invested greatly in attracting new tenants and amusement when the COVID-19 pandemic strike in 2020. Government-compelled shutdowns more compounded Pyramid’s fiscal challenges by fundamentally shutting off its revenue stream.

On the other hand, Pyramid has efficiently restructured numerous of the challenge financial loans so significantly, so it truly is very likely that the present-day issues with the Crossgates financial loans will be settled, as nicely, right before they occur because of in Might.

Final June, Pyramid Administration CEO Stephen Congel introduced a deal to refinance personal debt from Crossgates Commons, Pyramid’s massive box retail  residence throughout Washington Avenue Extension from the primary mall property.

“Getting a deal accomplished definitely speaks volumes to Pyramid’s persistence, resolve, and resilience as a developer, and our determination to reinvesting in our centers to make sure their long-phrase advancement and ongoing success,” Congel reported at the time.

Pyramid has also been searching for to significantly lessen its house tax expenditures in the city of Guilderland, and it has been compelled to lay bare the facts of its money complications in lawsuits it has submitted against the town in state Supreme Court as part of that effort and hard work.

Danone North America Announces $65 Million Investment to Support Long-Term Business Growth

Danone North America Announces  Million Investment to Support Long-Term Business Growth

Major capital financial investment assists grow production capabilities and scale important U.S. brands, which includes Global Delight creamers, Silk plant-based mostly creamers and StoK completely ready-to-consume espresso

BROOMFIELD, Colo. and WHITE PLAINS, N.Y., Feb. 22, 2023 /PRNewswire/ — Danone North America, a foremost meals and beverage organization, right now declared it will spend up to $65 million over the upcoming two a long time to generate a new bottle creation line in Jacksonville, Florida. The investment will assist Danone North America’s extended-phrase expansion system and will supply vital positive aspects across the U.S. company, together with advancing operational excellence, enabling flexibility in bottle layout, accelerating the company’s sustainability plans, and driving cost efficiencies.

“We are delighted to announce this investment decision in our North American enterprise, which will enable us to capitalize on shopper demand in crucial beverage types which include espresso creamers, plant-primarily based creamers, and all set-to-consume coffee, while also supporting our extended-term progress agenda,” explained Shane Grant, Team Deputy CEO, CEO Americas. “This investment decision will assistance us continue to keep our goods on our customers’ cabinets and give extra American individuals the Danone merchandise they really like.”  

This multi-million-greenback financial investment will raise generation of several of Danone’s espresso and creamer brands in the U.S., including International Delight, Silk and SToK. It also serves to meet up with client demand from customers in these categories though supporting the company’s sustainability target by lowering all round drinking water use, lowering carbon emissions and accelerating the firm’s intention of packaging circularity.

The expansion will also build up to 40 new whole-time work opportunities with competitive wages and advantages. New staff members will be suitable for Danone North America’s parental bonding depart policy, enabling all production personnel with one calendar year of tenure to choose up to 18 months of compensated time off just after the start or adoption of a boy or girl.

Mike Sloboda, Danone North America’s Main Functions Officer commented, “We are thrilled to be investing in the people today and financial system of Jacksonville, creating 40 new work opportunities in addition to supporting our close to 110 current workers, all with aggressive wages and gains. This expenditure will allow for us to improved provide our clients and run our business enterprise in an even a lot more efficient and sustainable way.”

“This expansion of Danone North The united states goes to show that Jacksonville continues to be the spot to be,” Jacksonville Mayor Lenny Curry claimed. “I want to thank Danone North America for recognizing the power and commitment of our neighborhood and investing in the Jacksonville campus, our people, and our location. This $65 million will make work and enable us all get the job done to sustainable and liable economic progress.”

“Advanced producing is vital to a profitable technique for Northeast Florida and we are thrilled that Danone North The us will continue being and develop its facility in this article,” claimed Aundra Wallace, president of JAXUSA Partnership. “Our area is regarded all over the world for its depth of competent talent, decreased working expenditures and small business friendliness – all of which will bear fruit for the two Danone and our neighborhood at substantial.”

Danone North America is dedicated to bringing wellness via foodstuff to as lots of people today as achievable through reason-pushed, market-winning advancement. As a B Corp™, Danone North The united states leverages its organization as a drive for superior to create a much more inclusive and sustainable overall economy via its spouse and children of makes.

About Danone North America:

Danone North America is a intent-pushed firm and an business leader in the meals and beverage category. As a Licensed B Corporation®, Danone North The usa is committed to the generation of each financial and social benefit, when nurturing organic ecosystems via sustainable agriculture. Our sturdy portfolio of brands incorporates: Activia®, DanActive®, Danimals®, Dannon®, evian®, Happy Relatives® Organics, Trustworthy to Goodness®, Horizon® Natural and organic, International Delight®, Light + In good shape®, Oikos®, Silk®, So Delectable® Dairy Cost-free, STōK®, Two Very good®, Wallaby® Natural and YoCrunch®. With extra than 6,000 staff and 16 production areas across the U.S. and Canada, Danone North America’s mission is to provide wellbeing by way of foodstuff to as lots of individuals as doable. For extra information, visit www.danonenorthamerica.com/.

Danone North The usa is a Danone subsidiary.

Press Contact:

Erin Brooks
Danone North The usa
[email protected]

Resource Danone North The us

Teachers support personal finance education

Teachers support personal finance education

by Courtney Poquette, et al We are Vermont educators who teach high school personal finance, and we are united in support of legislation that would guarantee a full-semester, standalone personal finance course as a graduation requirement for all Vermont students.

Why is it so important to the future of our young students? Research by Next Gen Personal Finance (NGPF) and others demonstrates clearly that guaranteed personal finance education leads to positive outcomes and improves lives forever.

That is why we heartily endorse HB228, which would require just such a standalone course.

The traditional approach in high school is to teach students how to manage money for companies they will work for. But our young people never learn how to manage their own money, and their parents often are not money-savvy either, since they also were not taught personal finance.

In 2023, we believe that all high school graduates must be financially literate, whether they are headed to college, work or the military after graduation.

We are fortunate to be in schools that have a guaranteed personal finance course. Many of us have designed our own lessons and materials, but now, free curricula, lesson plans and other resources are available online through non-profits like NGPF.

Some high schools have partnered with the Community College of Vermont to attract students to the class who were college bound and had busy schedules. Now they can take the class and obtain college credit.

Our students think they will be rich if they earn $40,000 a year when they graduate. In our classes, we help them to realize how expensive their dream lifestyles are. Such reality checks force them to question decisions in their near futures, like college majors, job salaries, the cost of credit and more.

You would not believe how often we hear from students and their parents that our course has changed the direction of students’ lives for the better. And as teachers, we learn too. After all, we have household budgets, kids to send to college and retirement to think about.

Not long ago, a report showed that parents would rather talk to their kids about sex than about money. Personal finance classes make talking about money at the dinner table the new normal. Students in our classes use math, reading and language skills while working on monthly budgets and retirement plans. What could be more important today?

Many of Vermont’s educators have become confident teaching personal finance through free training provided by Champlain College’s Center for Financial Literacy, NGPF or other organizations like the Jump$tart Coalition.

So we have confident, trained teachers, free curriculum and with innovative ideas, we can make room for high school personal finance. There is no reason not to move forward.

The good news is that teachers, administrators and legislators across the nation are passionately advocating for this change. As of this writing, 17 states have passed legislation guaranteeing full-semester personal finance courses, and NGPF reports that there are currently 74 bills in 21 other states, including Vermont, in process.

We hope all states, including Vermont, adopt a guaranteed high school course. It’s an especially important issue in many black and brown school districts, where access to personal finance learning is more limited than in whiter, more affluent district.

Personal finance is a critical skill that perhaps more than any course sets  students up to succeed in life. We never have to explain to our students why the course is important. They get it. Let’s make sure all Vermont high school students get it.

Signed,

Courtney Poquette, Winooski High School, Winooski

Mary Brouilette, Bellows Free Academy, St. Albans

Bob Fredette, Lamoille Union High School, Hyde Park

Angela Pandis, Missisquoi Valley Union HS/MS, Swanton

Drew Gordon, South Burlington High School, Burlington


Evidence that Financial Education Improves Behavioral OutcomesTeachers support personal finance education
 

Evidence-Based Policy & Implementation Resources


Evidence that Financial Education Improves Behavioral Outcomes


a) The Effects of K-12 Financial Education Mandates on Student Postsecondary Education Outcomes

Research from the National Endowment for Financial Education. Financial education mandates have positive impacts on student borrowing behaviors across all income groups. States with personal finance graduation requirements have students with a higher incidence of applying for financial aid, a lower incidence of borrowing from private student lenders, a higher incidence of receiving grants and federal aid, and a lower likelihood of carrying credit card balances.


b) Does Financial Education Impact Financial Literacy and Financial Behavior, and If So, When?

Most earlier studies of financial education rely on outdated financial education requirements. Kaiser and Menkhoff show significant positive effects of financial education on both financial literacy (knowledge) and financial behavior. This meta-analysis corrects an often cited meta-analysis from Fernandes et. al. (2014), adding additional interventions and a more rigorous statistical methodology to make its conclusions. Compelling, rigorously critiqued evidence of the need for “just in time” financial education for high school students.


c) Financial Education Matters: Testing the Effectiveness of Financial Education Across 76 Randomized Experiments

We study the rapidly growing literature on the causal effects of financial education programs in a meta-analysis of 76 randomized experiments with a total sample size of over 160,000 individuals. The evidence shows that financial education programs have, on average, positive causal treatment effects on financial knowledge and downstream financial behaviors. Treatment effects are economically meaningful in size, similar to those realized by educational interventions in other domains, and are at least three times as large as the average effect documented in earlier work. These results are robust to the method used, restricting the sample to papers published in top economics journals, including only studies with adequate power, and accounting for publication selection bias in the literature. We conclude with a discussion of the cost-effectiveness of financial education interventions.


d) Does State-Mandated Financial Education Affect High-Cost Borrowing? (UPDATED 2019)

“…young adults who were required to take personal finance courses in high school were significantly less

likely to borrow payday loans than their peers who were not. These effects do not significantly differ by race/ethnicity or gender, suggesting that financial education may be useful regardless of demographics.” 


e) Retirement Savings with School-Based Financial Education

Students’ financial literacy performance is significantly associated with their schools’ and teachers’ characteristics, both positive and negative. Students who attend a school with adequate teaching materials and competent teachers — those who demonstrate control over their classroom and try to actively engage with students — are more likely to perform at the two highest levels on the PISA financial literacy test.


f) Optimal Financial Knowledge and Wealth Inequality

Financial literacy plays a key role in explaining inequality. Different levels of financial knowledge early in life have important implications for how much people will save. Adding financial knowledge to life cycle models permits a more accurate rendering of a world where consumers must cope with complex financial markets and must save so as to provide for their own retirement.


g) The impact of high school financial education: experimental evidence from Brazil

This paper studies the impact of a comprehensive financial education program spanning six states, 868 schools, and approximately 20,000 high school students in Brazil through a randomized control trial. The program increased student financial knowledge, increased saving rates for purchases, better likelihood of financial planning, and greater participation in household financial decisions by students. “Trickle-up” impacts on parents were also significant, with improvements in parent financial knowledge, savings, and spending behavior. The study also finds evidence that the program affected students’ inter-temporal preferences and attitudes.


h) Personal Finance Education Mandates & Student Loan Repayment

“Students with higher-income parents respond by adjusting borrowing, reducing median balances by 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. By contrast, first-generation and low-income borrowers bound by mandates did not significantly adjust borrowing, but were nonetheless more likely to pay down balances..”


i) Can financial literacy reduce domestic violence?

“Yes. Using data on more than 3.7 million intimate partner violence (IPV) incidents between 1994 and 2016, and exploiting the staggered introduction of state-mandated personal finance high school graduation requirements across U.S. states for identification, we show that improvements in women’s financial literacy can significantly reduce the rates of violence against women perpetrated by their male partners. We conservatively estimate a reduction in violence by between 3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and 11{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. Our evidence points to financial literacy deterring financial abuse, thereby empowering women to leave abusive relationships earlier or by preventing the first incident from ever occurring.”


Evidence-Based Policy & Implementation Resources


a) Transforming the Financial Lives of a Generation of Young Americans POLICY RECOMMENDATIONS FOR ADVANCING K-12 FINANCIAL EDUCATION

What we propose here is a comprehensive strategy to impart personal financial management skills to young people while they are in school. Recommendation 1: Introduce key financial education concepts early and continue to build on that foundation consistently throughout the K-12 school years. In addition, CFPB encourages states to make a stand-alone financial education course a graduation requirement for high school students. Recommendation 2: Include personal financial management questions in standardized tests. Recommendation 3: Provide opportunities throughout the K-12 years to practice money management through innovative, hands-on learning opportunities. Recommendation 4: Create consistent opportunities and incentives for teachers to take financial education training with the express intention of teaching financial management to their students


Consumer Financial Protection Bureau. (2013). Transforming the Financial Lives of a Generation of Young Americans POLICY RECOMMENDATIONS FOR ADVANCING K-12 FINANCIAL EDUCATION. [online] consumerfinance.gov. Available at: http://files.consumerfinance.gov/f/201304_cfpb_OFE-Policy-White-Paper-Final.pdf


b) Final Report – President’s Advisory Council on Financial Capability

The Council acknowledges that financial capability must be woven into the fabric of our lives—into our homes, our schools, our workplaces, our communities, even the design and regulation of the financial products and services we use. 


United States Treasury. (2013). Final Report President’s Advisory Council on Financial Capability. [online] treasury.gov. Available at: https://www.treasury.gov/resource-center/financial-education/Documents/PACFC{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20final{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20report{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20revised{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}2022513{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}288{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}29_R.pdf


c) Financial Capabilities of College Students from States with Varying Financial Education Policies

Well-educated students exhibit positive financial behaviors. After analyzing data from 15,797 college students, Gutter found that students from states where a financial education course was required had the highest reported financial knowledge and were more likely to display positive financial behaviors and dispositions. Compared to other students, these young adults were: More likely to save; Less likely to max out their credit cards; Less likely to make late credit card payments; More likely to pay off credit cards in full each month; Less likely to be compulsive buyers; More likely to be willing to take average financial risk

https://www.nefe.org/_images/research/Financial-Education-Mandates-Report/Financial-Education-Mandates-Report-Executive-Summary.pdf


d) Financial Education in High Schools Across America

State-level embedded course requirement mandates do not result in full compliance. While this lack of compliance could be because course catalog descriptions do not detail financial literacy instruction in all schools, it could also be because state departments of education have trouble auditing embedded course mandates. In our estimate, only 43{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} within states that have embedded course mandates have either a standalone or embedded course requirement.


e) Financial Literacy Subject Survey

Between July 15th and 17th, 2017 the National Financial Educators Council asked 5,123 young adults, “What high school-level course would benefit your life the most?” Respondents chose money management more often than math, science, and social studies:

  • 49.97{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Money Management (Personal Finance)”
  • 18.25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Mathematics (Algebra, Geometry)”
  • 14.43{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Social Studies (History, Government)”
  • 17.35{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Science (Biology, Chemistry)”


State by state results are available: NFEC Survey: “Should High Schools Require Financial Literacy?” 


NFEC. (2017). Financial Literacy Subject Survey. [online] Available at: https://www.financialeducatorscouncil.org/Financial-literacy-subject-survey/


f) A review of youth financial education: Effects and Evidence

“This report reviews current research and reporting in the field, and is intended to inform policymakers, practitioners, financial educators, and researchers of the current state of rigorous evidence on financial education in schools”… “This report features studies that (1) evaluate youth financial education programs in schools, (2) have a causal interpretation evidenced by a randomized controlled trial, natural experiment setting, or a valid pre-post study design, and (3) have been published in peer-reviewed academic journals or as reviewed working papers. Note that the studies predominantly relate to school based programs, as this is the context in which most youth financial education research has occurred.”

  • “Well-implemented state financial education mandates led to a clear improvement in financial behaviors.”
  • “Many U.S. financial education programs improve financial knowledge for students, though effect sizes vary based on the population served, amount of instruction time, and topics covered.”
  • “Other countries have used more widespread randomized controlled trials to study the effects of programs as they embed and expand them broadly. Those studies also provide useful information.”
  • Consumer Financial Protection Bureau. (2019). A review of youth financial education: Effects and Evidence. [online] consumerfinance.gov. Available at: https://files.consumerfinance.gov/f/documents/cfpb_youth-financial-education_lit-review.pdf


g) Digital vs. in-person financial education: What works best for Generation Z?

“Nowadays, financial literacy is one of the most important skills that can be acquired by a tech-savvy Generation Z student. In order to understand what format of financial education works best for Generation Z, we set up an experiment that involved implementing a financial education program called “Futuro Sicuro” with a sample of 650 High School students in Italy. The program allowed us to gather data from two treatments at the class level, namely 1) a traditional financial education simplified program with the presence of a financial advisor, and 2) a digital financial education program using web-based applications based on learning-by-playing concepts. The two treatments were associated with different costs but showed similar effects: three weeks after their conclusion, we find that both courses did increase actual financial knowledge and the results also aligned with participants’ realistic assessments of their own financial skills. A follow-up study also reveals the persistence of these effects three months later for the traditional course.”


h) Best Practices Implementing Financial Education in High Schools

“…breaks the implementation into eight stages: (0) building a coalition, (1) crafting and passing either legislation or administrative rule change, (2) constructing an implementation plan, (3) funding, (4) teacher professional development, (5) developing standards and selecting course resources, (6) teacher endorsement models, and (7) auditing and creating a feedback loop for continuous improvement.”

Urban, Carly (2022). Best Practices Implementing Financial Education in High Schools [online] Available at: https://papers.carlyurban.com/MTBestPracticesReportFINAL.pdf