How To Calculate Your Debt-To-Income Ratio For A Mortgage

How To Calculate Your Debt-To-Income Ratio For A Mortgage

There’s a lot that goes into the home buying process, especially if you’re a first-time home buyer. One criteria mortgage lenders use to assess your mortgage application is the debt-to-income ratio (DTI). Your debt-to-income ratio is a comparison of how much you owe (your debt) to how much money you earn (your income). The income you make before taxes (your gross income) is used to measure this number.

A lower debt-to-income ratio tells lenders you have a healthy balance between debt and income. However, a higher debt-to-income ratio indicates that too much of your income is dedicated to paying down debt. This could make some lenders see you as a risky borrower. While the DTI isn’t the only factor used to assess how much you can borrow, it’s still important to understand before you begin the home loan process.

Subscribe to the Select Newsletter!

Our best selections in your inbox. Shopping recommendations that help upgrade your life, delivered weekly. Sign-up here.

What is a good debt-to-income ratio?

A debt-to-income ratio of 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} means that 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of your income is going toward debt payments. This includes cumulative debt payments, so think credit card payments, car payments, student loans, personal loans and any other debt you may have taken on.

According to a breakdown from The Mortgage Reports, a good debt-to-income ratio is 43{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} or less. Many lenders may even want to see a DTI that’s closer to 35{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, according to LendingTree. A ratio closer to 45{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} might be acceptable depending on the loan you apply for, but a ratio that’s 50{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} or higher can raise some eyebrows.

Simply put, having too much debt relative to your income will make it harder to qualify for some home loans. That’s why many common forms of debt — like student loan debt or credit card debt — can be a major barrier to homeownership.

Mortgage lenders want to make sure borrowers haven’t overextended themselves in terms of how much debt they can afford to take on. This is why having a high DTI could cause lenders to decline your mortgage application.

How do you calculate debt-to-income ratio?

The formula for calculating your DTI is actually pretty simple: You’ll just need to add up your total monthly debt payments and divide it by your total gross monthly income.

Let’s say you have a student loan payment, a car payment and a credit card payment that total to $1,000 per month. Your gross monthly income is $5,000. When we divide 1,000 (your debt) by 5,000 (your gross income), we get 0.2, which is 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. So in this case, your DTI is 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

How do you lower your debt-to-income ratio?

Marcus by Goldman Sachs Personal Loans

  • Annual Percentage Rate (APR)

    6.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 24.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} APR when you sign up for autopay

  • Loan purpose

    Debt consolidation, home improvement, wedding, moving and relocation or vacation

  • Loan amounts

  • Terms

  • Credit needed

  • Origination fee

  • Early payoff penalty

  • Late fee

Alternatively, you might consider using a balance transfer credit card to move your balance over to a new card with a 0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} intro APR offer. This way, you can have an extended period where you aren’t being charged interest on your payments and can pay down the principal debt faster.

The Citi Simplicity® Card offers a 0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} intro APR for 21 months on balance transfers from the date of your first transfer (after, 17.74{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} – 28.49{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} variable APR; balance transfers must be completed within four months of account opening).

Citi Simplicity® Card

  • Rewards

  • Welcome bonus

  • Annual fee

  • Intro APR

    0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for 21 months on balance transfers; 0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for 12 months on purchases

  • Regular APR

  • Balance transfer fee

    Introductory fee of 3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} ($5 minimum) for transfers completed within the first 4 months of account opening, then up to 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} ($5 minimum).

  • Foreign transaction fee

  • Credit needed

Another solid option is the Wells Fargo Active Cash® Card. It offers an introductory 0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} APR for 15 months from account opening (after, 19.24{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, 24.24{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, or 29.24{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} variable APR ). In addition, this card offers a welcome bonus: you can earn $200 cash rewards bonus after spending $1,000 in purchases in the first three months.

Wells Fargo Active Cash® Card

On Wells Fargo’s secure site

  • Rewards

    Unlimited 2{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} cash rewards on purchases

  • Welcome bonus

    Earn a $200 cash rewards bonus after spending $1,000 in purchases in the first 3 months

  • Annual fee

  • Intro APR

    0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} intro APR for 15 months from account opening on purchases and qualifying balance transfers; balance transfers made within 120 days qualify for the intro rate

  • Regular APR

    19.24{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, 24.24{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, or 29.24{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} variable APR on purchases and balance transfers

  • Balance transfer fee

    Introductory fee of 3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for 120 days from account opening, then up to 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} ($5 minimum)

  • Foreign transaction fee

  • Credit needed

Mortgages and DTI

When applying for a mortgage, you should also consider all the costs that come with purchasing a home, including private mortgage insurance (PMI) (if you put down less than 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, homeowner’s insurance), property taxes, interest, lender fees, inspections, appraisals, closing costs and more.

Needless to say, it’s an expensive process. But you can make it a little more affordable by choosing a lender that offers ways to help you save. For example, Ally Bank doesn’t charge certain lender fees such as an application fee, origination fee, processing fee or underwriting fee. This can help you save some cash on the upfront process.

Ally Bank

  • Annual Percentage Rate (APR)

    Apply online for personalized rates; fixed-rate and adjustable-rate mortgages included

  • Types of loans

    Conventional loans, HomeReady loan and Jumbo loans

  • Terms

  • Credit needed

  • Minimum down payment

    3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} if moving forward with a HomeReady loan

Pros

  • Ally HomeReady loan allows for a slightly smaller downpayment at 3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}
  • Pre-approval in just three minutes
  • Application submission in as little as 15 minutes
  • Online support available
  • Existing Ally customers can receive a discount that gets applied to closing costs
  • Doesn’t charge lender fees

Cons

  • Doesn’t offer FHA loans, USDA loans, VA loans or HELOCs
  • Mortgage loans are not available in Hawaii, Nevada, New Hampshire, or New York

PNC Bank also offers a few specialized loan options designed to help certain members of the community save money on their home purchase. This lender offers a loan option for medical professionals who are looking to buy a primary residence only. With this loan, medical professionals can apply for as much as $1 million and won’t have to pay private mortgage insurance (PMI), regardless of their down payment amount. 

PNC Bank

  • Annual Percentage Rate (APR)

    Apply online for personalized rates; fixed-rate and adjustable-rate mortgages included

  • Types of loans

    Conventional loans, FHA loans, VA loans, USDA loans, jumbo loans, HELOCs, Community Loan and Medical Professional Loan

  • Terms

  • Credit needed

  • Minimum down payment

    0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} if moving forward with a USDA loan

Pros

  • Offers a wide variety of loans to suit an array of customer needs
  • Available in all 50 states
  • Online and in-person service available
  • Pre-approval in as little as 30 minutes

Cons

  • Doesn’t offer home renovation loans

Bottom line

Taking on a mortgage is a hefty responsibility, so lenders want to make sure you aren’t biting off more than you can chew when it comes to your current debt responsibilities. This is why they calculate a debt-to-income ratio to judge how much of your income goes toward debt payments.

Of course, the DTI isn’t the only criteria a lender will look at, so don’t feel too discouraged if your DTI is a little higher than most lenders prefer. Calculating your DTI sooner rather than later will allow you ample time to pay down debt or increase your income so you can lower that DTI.

Catch up on Select’s in-depth coverage of personal finance, tech and tools, wellness and more, and follow us on Facebook, Instagram and Twitter to stay up to date.

Editorial Note: Opinions, analyses, reviews or recommendations expressed in this article are those of the Select editorial staff’s alone, and have not been reviewed, approved or otherwise endorsed by any third party.

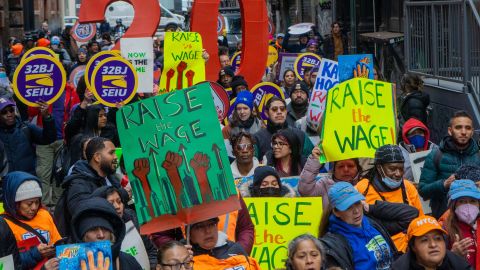
These states are raising their minimum wage in 2023

These states are raising their minimum wage in 2023


Minneapolis
CNN
 — 

The current period of high inflation that has significantly impacted the US economy will also influence a New Year’s tradition: The annual state minimum wage increases.

By January 1, hourly minimum wages in 23 states will rise as part of previously scheduled efforts to reach $15 an hour or to account for cost-of-living changes. The increases account for more than $5 billion in pay boosts for an estimated 8.4 million workers, the Economic Policy Institute estimates.

Additionally, nearly 30 cities and counties across the US will increase their minimum wage, according to the EPI, a left-leaning think tank.

The larger-than-typical increases for a dozen states come after inflation hit a 40-year high this summer, leaving families struggling to keep up with the rising costs.

“The fact that there’s high inflation really just underscores how necessary these minimum wage increases are for workers,” said Sebastian Martinez Hickey, a research assistant at the EPI. “Even before the pandemic, there was no county in the United States where you could affordably live as a single adult at $15 an hour.”

The pandemic and the subsequent period of economic recovery has further revealed the growing chasm in America’s wealth gap. During the past two years, working conditions and low pay contributed to a swelling of labor movement activity and actions by many large corporations to raise their wage floor.

RaiseUpNY Coalition, including the Laborers Internation Union 79 and 32BJ SEIU, hold a rally at City Hall Park to fight for a higher minimum wage in Manhattan, New York, on November 15, 2022.

The pandemic also led to a structural upheaval in the nation’s labor market, creating an imbalance of worker supply and demand that still persists. Employers have found themselves short of workers for most of the year, which has pushed up average annual hourly wages in the battle to recruit and retain staff. While some workers in competitive industries such as retail and dining have found their new salary outpaces inflation, most pay has been outpaced by rising prices.

“The story is different because wages have been increasing at the low-end, much faster than inflation and much faster than in middle- or high-wage jobs,” said Michael Reich, economics professor at the University of California at Berkeley. “And that means that many workers, even in the $7.25 states, are already getting paid above the minimum wage.”

In other words, he said, the minimum wage “has become less and less binding.”

“Even though minimum wages might go up by 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, in many states and cities, labor costs aren’t going to go up anywhere as much as they have in the past, because they already have gone up,” he said. “That also means that prices aren’t going to go up at [places like] restaurants.”

The federal minimum wage of $7.25 per hour hasn’t budged since 2009, and 20 states have a minimum wage either equal to or below the federal level, making $7.25 their default baseline. The value of the federal minimum wage peaked in 1968 when it was $1.60, which would be worth about $13.46 in 2022, based on the Bureau of Labor Statistics’ inflation calculator.

  • Delaware: $10.50 to $11.75
  • Illinois: $12 to $13
  • Maryland: $12.50 to $13.25
  • Massachusetts: $14.25 to $15
  • Michigan: $9.87 to $10.10
  • Missouri: $11.15 to $12
  • Nebraska: $9 to $10.50
  • New Jersey: $13 to $14.13* (scheduled increase also includes inflation adjustment)
  • New Mexico: $11.50 to $12
  • New York: $13.20 to $14.20 (Upstate New York); $15 (in and around NYC)
  • Rhode Island: $12.25 to $13
  • Virginia: $11 to $12
  • Alaska: $10.34 to $10.85
  • Arizona: $12.80 to $13.85
  • California: $14.50 (firms with 25 or fewer employees) /$15 (firms with 26+ employees) to $15.50
  • Colorado: $12.56 to $13.65
  • Maine: $12.75 to $13.80
  • Minnesota: $8.42 to $8.63 (small employer); $10.33 to $10.59 (large employer)
  • Montana: $9.20 to $9.95
  • Ohio: $9.30 to $10.10
  • South Dakota: $9.95 to $10.80
  • Vermont: $12.55 to $13.18
  • Washington: $14.49 to $15.74
  • Connecticut (effective July 1): $14 to $15
  • Florida (September 2023): $11 to $12
  • Nevada (effective July 1): $9.50 to $10.25 (firms that offer benefits); $10.50 to $11.25 (no benefits offered)
  • Oregon: $13.50 (effective July 1, indexed annual increase to be based on the CPI)

Sources: State websites, National Conference of State Legislatures, Economic Policy Institute

Is Bowman Consulting Group (BWMN) Stock Outpacing Its Business Services Peers This Year?

Is Bowman Consulting Group (BWMN) Stock Outpacing Its Business Services Peers This Year?

For these on the lookout to come across strong Enterprise Solutions stocks, it is prudent to search for businesses in the group that are outperforming their peers. Has Bowman Consulting (BWMN) been just one of these shares this yr? Let us just take a closer glimpse at the stock’s 12 months-to-date performance to obtain out.

Bowman Consulting is a single of 332 particular person shares in the Company Solutions sector. Collectively, these companies sit at #12 in the Zacks Sector Rank. The Zacks Sector Rank considers 16 diverse groups, measuring the common Zacks Rank of the individual stocks in the sector to gauge the toughness of just about every team.

The Zacks Rank emphasizes earnings estimates and estimate revisions to locate stocks with strengthening earnings outlooks. This system has a extended document of success, and these stocks have a tendency to be on observe to beat the marketplace in excess of the following just one to three months. Bowman Consulting is at this time sporting a Zacks Rank of #1 (Robust Obtain).

The Zacks Consensus Estimate for BWMN’s comprehensive-calendar year earnings has moved 36.6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} greater within the previous quarter. This implies that analyst sentiment is more powerful and the stock’s earnings outlook is enhancing.

Centered on the most current offered information, BWMN has obtained about .7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} so much this calendar year. In the meantime, stocks in the Enterprise Products and services team have missing about 31.7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} on normal. This means that Bowman Consulting is accomplishing far better than its sector in phrases of yr-to-day returns.

A different Small business Products and services inventory, which has outperformed the sector so far this yr, is Paysign, Inc. (PAYS). The stock has returned 40{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} 12 months-to-date.

The consensus estimate for Paysign, Inc.’s present 12 months EPS has enhanced 33.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} more than the previous a few months. The stock at present has a Zacks Rank #2 (Acquire).

To break points down much more, Bowman Consulting belongs to the Small business – Providers business, a team that includes 25 individual companies and now sits at #160 in the Zacks Sector Rank. On common, stocks in this team have missing 46.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} this year, which means that BWMN is undertaking greater in phrases of calendar year-to-date returns.

Paysign, Inc. nevertheless, belongs to the Financial Transaction Companies industry. At the moment, this 39-stock field is rated #189. The business has moved -14{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} so much this calendar year.

Investors interested in the Business enterprise Providers sector may perhaps want to preserve a close eye on Bowman Consulting and Paysign, Inc. as they attempt to continue their good effectiveness.

Zacks Names “One Most effective Pick to Double”

From countless numbers of shares, 5 Zacks authorities every single have preferred their beloved to skyrocket +100{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} or more in months to occur. From those 5, Director of Investigation Sheraz Mian hand-picks just one to have the most explosive upside of all.

It is a tiny-acknowledged chemical business which is up 65{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} more than very last yr, but nevertheless filth low-cost. With unrelenting desire, soaring 2022 earnings estimates, and $1.5 billion for repurchasing shares, retail investors could jump in at any time.

This corporation could rival or surpass other latest Zacks’ Stocks Set to Double like Boston Beer Enterprise which shot up +143.{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in minimal a lot more than 9 months and NVIDIA which boomed +175.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in one year.

No cost: See Our Top Inventory and 4 Runners Up >>

Want the most current suggestions from Zacks Financial investment Research? Today, you can obtain 7 Best Stocks for the Next 30 Days. Simply click to get this free of charge report

Bowman Consulting Team Ltd. (BWMN) : Absolutely free Inventory Examination Report

Paysign, Inc. (PAYS) : Cost-free Inventory Evaluation Report

To examine this short article on Zacks.com click below.

Zacks Financial investment Research

The sights and views expressed herein are the sights and views of the writer and do not automatically reflect those of Nasdaq, Inc.

These Are the 10 Highest- and Lowest-Paying Jobs in the U.S.

These Are the 10 Highest- and Lowest-Paying Jobs in the U.S.
A child sitting on his mother's lap while a doctor checks his heartbeat with a stethoscope.

Image source: Getty Images

Your career has a huge impact on how much money you make.


Key points

  • Chief executives and medical professions make up many of the highest-paying jobs in the United States.
  • The lowest-paying jobs are entry-level positions that don’t require specialized training or education.
  • If you want to earn more, you could start a training program for a high-paying career, become a freelancer, or work a side hustle.

According to data from the U.S. Bureau of Labor Statistics, the average U.S. income was $97,962 in 2021. High-earning outliers bring that number up, as the median income was $69,717. But averages vary heavily depending on the job. Some positions make more than double the average, whereas others earn only a fraction of it.

If you’re making a career change or deciding on a career path for the first time, you may want to go where the money is. To give you ideas of occupations that do and don’t lead to big earnings, here are the highest- and lowest-paying jobs in the United States.

The 10 highest-paying jobs in the United States

Here are the 10 highest-paying jobs in the United States and their average salaries as of 2021:

  1. Chief executives: $213,020
  2. Nurse anesthetists: $202,470
  3. Pediatricians (general): $198,420
  4. Airline pilots/copilots/flight engineers: $198,190
  5. Dentists (specialists): $179,400
  6. Dentists (general): $167,160
  7. Computer and information systems managers: $162,930
  8. Architectural and engineering managers: $158,970
  9. Podiatrists: $158,380
  10. Natural sciences managers: $156,110

Unsurprisingly, chief executives come in at the top of the list. Half of the jobs on the list are in the medical field, but there is still some variety among the highest-earning occupations. Airline pilots and flight engineers earn large salaries, as do managers in several fields.

All these jobs require a college degree and/or specialized training. That’s something that most high-paying jobs have in common, and studies have shown that people with more education earn more. If you want an above-average salary, look for a field you’re interested in studying with quality job opportunities.

The 10 lowest-paying jobs in the United States

Here are the 10 lowest-paying jobs in the United States and their average salaries as of 2021:

  1. Shampooers: $25,160
  2. Fast food cooks: $25,490
  3. Hosts and hostesses (restaurant/lounge/coffee shop): $26,000
  4. Fast food and counter workers: $26,060
  5. Amusement and recreation attendants: $26,110
  6. Ushers, lobby attendants, and ticket takers: $26,390
  7. Cashiers: $26,770
  8. Lifeguards, ski patrol, and other recreational protective service workers: $27,320
  9. Dishwashers: $27,350
  10. Childcare workers: $27,860

As you can see, these are entry-level jobs that don’t require much or any specialized training. That’s not to say these jobs are unimportant, or the pay is fair. But because there are so many people who can perform these jobs, employers pay low wages for them.

How to increase your pay

If you’re in a low-paying job that makes it hard to get ahead financially, the best goal you can set for yourself is increasing your pay. Personal finance advice often focuses on saving more, but this only gets you so far. When you aren’t making a livable wage, earning more money is the only real fix.

This is easier said than done, but it’s possible for those who put in the work. Here are a few options to consider:

  • Get the training required for a high-paying job. You could pursue a college degree or complete a certification program. Look for a career you like first, and then see what kind of education you need for it. There are plenty of six-figure jobs you could land with the right training.
  • Become a freelancer. If you have an in-demand skill, you could make money from it by freelancing. In fact, the average freelancer makes $93 per hour.
  • Start a side hustle. If your issue is that you aren’t getting enough hours, there are side hustles that could earn you $10,000 or more.

There are lots of options out there to increase your earnings — and thereby your savings account balance. Take some time to think about your income goals and what you want to do so you can find the option that works best for you.

Alert: highest cash back card we’ve seen now has 0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} intro APR until 2024

If you’re using the wrong credit or debit card, it could be costing you serious money. Our expert loves this top pick, which features a 0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} intro APR until 2024, an insane cash back rate of up to 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, and all somehow for no annual fee. 

In fact, this card is so good that our expert even uses it personally. Click here to read our full review for free and apply in just 2 minutes. 

Read our free review

A 39-year-old who makes $160,000/month in passive income shares his best advice

A 39-year-old who makes 0,000/month in passive income shares his best advice

When starting a organization, it is in some cases difficult to know what to prioritize, and likely at it alone can be overwhelming. But there are methods you can use to avoid common pitfalls.

My mission is to instruct folks how to make funds from their passions. It can be what I did: I went from dwelling on meals stamps to developing two on line organizations.

Nowadays, I run a songs web site, The Recording Revolution, and a entrepreneurship coaching organization. I work just 5 hrs a 7 days from my residence workplace and make $160,000 a thirty day period in passive income.

Here’s what I notify my 3,000 shoppers to think about in the very first 30 days of starting up a enterprise:

1. Be very clear about how you want to spend your time.

A lot of new business entrepreneurs I meet up with know only 1 detail: how a great deal revenue they want to make. 

Whilst that’s a great starting off place, it really is incomplete. Your company really should provide your life, not the other way about. So make absolutely sure it aligns with your hopes, desires and aims.

To get clear about the style of company and daily life you want, question a few concerns:

  1. What does a perfect day glance like to you? Never just believe about your typical workday. Consider other daily life functions you want to healthy into your working day, like performing exercises or shelling out time with household.
  2. How numerous hours do you want to perform a week? You you should not have to comply with the regular 40-hour workweek. Recognizing exactly how numerous several hours you want to perform will assist you superior prioritize tasks.
  3. How vital is time off? Some people today really don’t care significantly about using time off, as extended as they appreciate what they do. Other individuals price extended time off. In order to have funds flowing in when you happen to be not working, you are going to need to have to have some type of passive cash flow stream.

2. Simplify your company product.

When I started off my audio training enterprise, folks told me I required to test my gross sales web pages, toss start events and pre-file a bunch of adverts in purchase to mature.

Alternatively than stretching myself slender executing items that didn’t make sense to me, I retained it simple and targeted on a few factors: making weekly articles for my blog and YouTube channel, expanding my email record from that audience, and advertising and marketing the paid out products I developed to that checklist.

If you happen to be just setting up out, build content all around your expertise to improve an audience. It does not have to be great. You can iterate as you go and design and style new goods based mostly on what your prospects want extra of.

3. Cut out needless every day tasks.

Identify what each day routines will assist you earn additional. Do not squander time or melt away oneself out focusing on unimportant tasks.

It may possibly feel excellent to get to inbox zero or improve the color of the buttons on your website, primarily in the early days in which you want to sense like you have obtained a goal. But neither of people things will make you money.

Prior to you start out a new endeavor, inquire by yourself a few inquiries:

  1. What’s the anticipated final result for doing this task? 
  2. Does it direct to much more revenue?
  3. Can I level to a direct link between accomplishing that endeavor and earning income?
  4. What is the value of undertaking this as a substitute of a little something else? 

4. Prioritize having entertaining.

I quit my $35K job to grow my side hustle — now it brings in $141 million a year

What borrowers can do while student loan forgiveness is up in the air

What borrowers can do while student loan forgiveness is up in the air

Creatas | Creatas | Getty Illustrations or photos

1. Make the most of excess money

2. Look at making payments in any case

Boy_anupong | Moment | Getty Illustrations or photos

If you have a healthier rainy day fund and no credit score card debt, it might make feeling to keep on paying out down your pupil loans even for the duration of the split, professionals say.

There is a huge caveat below, nonetheless. If you might be enrolled in an cash flow-driven reimbursement program or pursuing general public service personal loan forgiveness, you you should not want to carry on shelling out your loans.

Which is simply because months during the government’s payment pause nevertheless count as qualifying payments for all those programs, and given that they the two outcome in forgiveness just after a specified amount of time, any income you toss at your financial loans through this period just lessens the volume you may at some point get excused.

3. Assessment your possibilities for when payments resume

President Biden: 22 million people have signed on for student debt relief

If you might be unemployed or dealing with a further economical hardship, you could possibly want to set in a ask for for an financial hardship or unemployment deferment. Individuals are the perfect means to postpone your federal pupil financial loan payments, because curiosity isn’t going to accrue.

If you you should not qualify for possibly, even though, you can use a forbearance to proceed suspending your bills. Just continue to keep in intellect that with forbearance, curiosity will rack up and your equilibrium will be bigger — possibly considerably larger — when you resume paying out.

4. Test if refinancing would make feeling now

Greater instruction pro Mark Kantrowitz experienced previously suggested that federal university student loan borrowers chorus from refinancing their personal debt with a personal loan provider though the Biden administration deliberated on how to move forward with forgiveness. Refinanced pupil loans wouldn’t qualify for the federal reduction.

Now that debtors know how a great deal in loan cancellation is on the table — if the president’s coverage survives the Supreme Court — debtors may want to consider the choice, Kantrowitz explained. With the Federal Reserve expected to keep on boosting interest prices, he added, you’re far more probable to select up a lower rate with a lender currently than down the highway.

Even now, Kantrowitz extra, it’s possibly a modest pool of borrowers for whom refinancing is wise.

Your level does not matter if you get rid of your career, have sudden medical charges, won’t be able to afford your payments and uncover that defaulting is your only option.

Betsy Mayotte

president of The Institute of College student Loan Advisors

These include borrowers who really don’t qualify for the Biden administration’s forgiveness — the system excludes anybody who earns far more than $125,000 as an personal or $250,000 as a household — and people who owe additional on their student loans than the administration strategies to cancel, he stated. The latter debtors may possibly want to look at refinancing the part of their credit card debt more than the relief quantities, he additional.

Still, borrowers really should initially understand the federal protections they are offering up by refinancing, warns Betsy Mayotte, president of The Institute of Scholar Bank loan Advisors.

For illustration, the U.S. Division of Schooling allows you to postpone your costs devoid of desire accruing if you can establish financial hardship. The government also features financial loan forgiveness programs for lecturers and public servants.

“Your rate isn’t going to make any difference if you reduce your work, have unexpected clinical charges, won’t be able to manage your payments and come across that defaulting is your only solution,” mentioned Mayotte in a former job interview about refinancing.