Developments driving the Global Business Services market

Developments driving the Global Business Services market

Above the previous yrs, several corporates have been professionalising their BPO and SSC environments as a result of the establishment of Worldwide Business enterprise Services. Marja van den Tweel, lover at Quintop and specialist on the make a difference, outlines some of the primary components driving the escalating reputation of Global Enterprise Services.

World Enterprise Providers (GBS) is the evolution of Shared Expert services Facilities (SSC) and Business Method Outsourcing (BPO) into a a lot more holistic, and cross-functional set up that focuses on system performance advancement, assistance good quality and cost reduction.

Although Worldwide Company Solutions appear in numerous shapes, dimensions, and flavours (worldwide as opposed to regional onshore, nearshore, and offshore providers in-household and outsourced), they normally provide together many help features such as finance, procurement, technological know-how, human methods and amenities underneath a person streamlined roof.

Developments driving the Global Business Services market

Going through an at any time-rising need to run agile and efficiently, corporates are progressively turning to World Business Providers as a usually means to boost personnel or user working experience, enrich productiveness or to speed up business enterprise insights.

An field well worth in accordance to a single estimate about $620 billion, the market Worldwide Small business Services is growing quick. In the coming many years, double-digit growth is envisioned for the sector, driven by trends and developments which includes:

1) Cross-functional optimisation

In a aid function, it is tempting to only optimise within the silo and end at the points the place a process is handed about to an additional office. The concentration of that functionality is then on its individual included benefit and its personal operational enhancements.

On the other hand, mainly because GBS functions across capabilities, a structural shift can get spot to stop-to-conclusion processes and journeys. As a consequence, organisations are cashing in on possibilities that ended up formerly skipped.

For illustration, where an HR SSC was successful in lowering charges for the HR administration and payroll input only, in a GBS surroundings there is area to construct a broader enterprise scenario with IT and Finance to increase the processes close-to-stop for the profit of the firm as a full.

By agreeing on a joint GBS roadmap across capabilities, options and investments are built primarily based on broader business enterprise aims. This is an accelerator for the company’s supporting capabilities. Correct end-to-finish system improvements need a broader look at on establishing thoughts and employing options fairly than just wanting in a silo. And that is specifically what GBS is about: spotting, analysing, and exploiting these collective opportunities for the organisation.

2) Deploying smart automation

Cloud methods have brought a whole lot to the planet of shared companies and business method automation. However, organisations come across that the many applications readily available make it additional difficult to hold matters very simple and make procedures clear.

GBS offers way and accelerates automation by integrally developing good processes. Less than central governance, strategic priorities are translated into an automation roadmap. This helps prevent an organisation from owning more and more fragmented procedures and tools.

The most usually deployed automation technologies are system integrations, workflows, electronic kinds and approvals/e-signatures, robotic approach automation (for repetitive jobs) and electronic doc management (which include storage and retention).

GBS is also committed to establishing a digital company culture, as perfectly as how workforce collaborate inside of the organisation. Based mostly on the broader organisational system, GBS is able to make improved long-time period expense choices. This means that the picked out technology or automation answers can yield a better ‘return on investment’ and obtain larger organisational get-in.

3) Higher productivity and decreased prices

In the past 10 years, businesses improved productiveness by centralising companies into an SSC or outsourcing to a BPO companion. In parallel, perform was transferred to low-price nations in Eastern Europe or Asia. Financial savings were reached due to the fact of centralisation and lower labour costs.

Organisations transferring from an SSC or BPO model to a GBS model come across that, even just before producing this transition, their expenditures are now lower.

But the additional value of owning an organisational GBS strategy goes outside of centralisation and labour arbitrage. With a aim on the broader small business targets, GBS is in a position to lead to the organisation’s productiveness and cost discounts at yet another amount – bringing the now-current push for efficiency of SSC and BPO versions to the stage of enterprise extra worth.

A vital explanation for this is the broader point of view of GBS – by looking across the supporting functions, it will help uncover sources of inefficiency that have been previously concealed. As a result, system advancements carried out within just a GBS organisation have the probable to achieve even larger productivity and reduced expenditures.

4) Digital teams ‘in the mix’

The Covid-19 pandemic has demonstrated that doing work in virtual teams can be an superb alternative to performing physically in a single spot. With the accelerated advancement of on the internet collaboration instruments, digital collaboration is here to keep.

For the progress of GBS, this is a massive chance. In the great combine of onshore, nearshore, and offshore services, virtual groups are going to lead to the expansion of capabilities and the continuity of services delivery. But over all, it signifies that place no for a longer time needs to be a limiting component in recruiting the best talent for GBS.

5) Info insights

Another great component of the included value GBS offers is owed to the assortment and analysis of electronic information. GBS is strengthening the organisation’s accessibility to electronic details, for the reason that the GBS data workforce collects details required by the firm. The velocity of nearly authentic-time insights, stories, and dashboards from uncooked data offers wonderful business worth for the business, enabling leadership to make additional exact and proactive business decisions.

Additionally, by bringing alongside one another the competence of the unique supporting features comprised below GBS, digital abilities are jointly created. As this kind of, the growth of knowledge applications and analytics abilities is attaining progressively much more ability in the GBS placing.

6) Professionalised governance

With a GBS model, organisations are building a true governance organisation in which assessment, companion assortment and service supply conclusions are introduced together. In a produced GBS organisation, the GBS governance workforce is of a senior degree so that affect can be exercised to all stakeholders. This usually means an huge strengthening of interior competence with regard to alignment on company requirements, the constructing of sourcing procedures and executing these techniques.

In addition, methodologies for transitions, modify and conversation across the organisation are standardised and professionalised.

GBS ensures superior selection-building and support shipping and delivery management for supporting functions this kind of as Finance, IT and HR, by the continual alignment of initiatives with the strategic goals of the organisation. An advancement especially when in comparison to a predicament in which every function was performing their personal point.

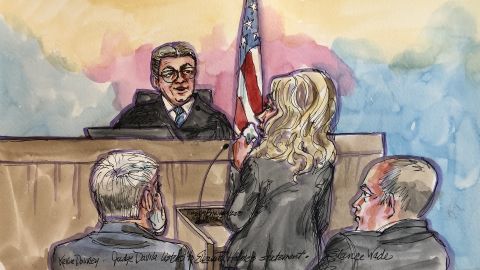
Elizabeth Holmes sentenced to more than 11 years in prison for fraud

Elizabeth Holmes sentenced to more than 11 years in prison for fraud


CNN
 — 

Elizabeth Holmes was sentenced to far more than 11 several years in prison on Friday following her conviction in January for defrauding investors when managing the unsuccessful blood screening startup Theranos.

Decide Edward Davila imposed a sentence of 11 many years and three months in jail, with yet another three several years of supervision right after Holmes is produced. The sentence also incorporates a wonderful of $400, or $100 for every single count of fraud. Restitution will be established at a afterwards date. Holmes was ordered to flip herself into custody on April 27, 2023. She is envisioned to enchantment her conviction.

Holmes, who was uncovered guilty in January on 4 costs of defrauding investors, confronted up to 20 many years in jail as well as a good of $250,000 furthermore restitution for just about every rely.

Lawyers for the governing administration requested for a 15-yr prison phrase, as very well as probation and restitution, when Holmes’ probation officer pushed for a 9-year time period. Holmes’ protection crew requested Davila, who presided around her situation, to sentence her to up to 18 months of incarceration adopted by probation and neighborhood support.

In advance of the sentencing was announced, a tearful Holmes spoke to the courtroom in San Jose, California. “I cherished Theranos. It was my life’s function,” she explained. “The folks I tried out to get involved with Theranos were the people today I beloved and respected the most. I am devastated by my failings.”

Elizabeth Holmes, the founder of failed blood testing startup Theranos who was convicted of fraud earlier this year, was sentenced today by a judge in court in San Jose, California. She is shown here making a statement to the judge before the sentencing.

She also apologized to the employees, traders and individuals of Theranos. “I’m so, so sorry. I gave all the things I experienced to make our firm and to conserve our organization,” she claimed. “I regret my failings with every single cell in my physique.”

“The judge imposed a potent sentence that confirms that fraud are not able to masquerade as innovation in Silicon Valley,” mentioned George Demos, a previous SEC enforcement attorney and adjunct legislation professor at UC Davis. “When presented the opportunity to converse, Elizabeth Holmes built a assertion that she takes obligation for Theranos but did not say she will take obligation for the fraud.”

In arguments ahead of the choose on Friday over her sentence, Kevin Downey, 1 of Holmes’ lawyers, mentioned that unlike other defendants in company fraud cases, the Theranos founder did not convey greed by cashing out shares or shelling out cash on “yachts and planes.” Alternatively, the cash was “used to establish health-related technologies.”

Federal prosecutor Jeffrey Schenk pointed out that Holmes did gain fame, admiration, and a way of life from the fraud, even if she did not make fiscal gains. “These however are rewards she’s obtaining,” he reported.

Friday’s sentencing hearing caps off Holmes’ spectacular downfall. The moment hailed as a tech field icon for her company’s claims to check for a assortment of problems with just a number of drops of blood, she is now the unusual tech founder to be convicted and encounter jail time for her company’s missteps.

Holmes, now 38, began Theranos in 2003 at the age of 19 and soon thereafter dropped out of Stanford College to go after the business complete-time. Immediately after a 10 years less than the radar, Holmes commenced courting the push with claims that Theranos experienced invented technology that could correctly and reliably exam for a vary of conditions making use of just a handful of drops of blood taken from a finger prick.

Theranos elevated $945 million from an extraordinary listing of investors, including media mogul Rupert Murdoch, Oracle founder Larry Ellison, Walmart’s Walton spouse and children and the billionaire relatives of previous Secretary of Education Betsy DeVos. At its peak, Theranos was valued at $9 billion, making Holmes a billionaire on paper. She was lauded on magazine covers, regularly donning a signature black turtleneck that invited comparisons to late Apple CEO Steve Work opportunities. (She has not worn that search in the courtroom.)

The corporation started to unravel soon after a Wall Road Journal investigation in 2015 identified the corporation had only at any time performed about a dozen of the hundreds of checks it available working with its proprietary blood testing product, and with questionable precision. In its place, Theranos was relying on 3rd-bash created products from traditional blood testing companies.

In 2016, Theranos voided two several years of blood check final results. In 2018, Holmes and Theranos settled “massive fraud” costs with the Securities and Exchange Commission, but did not admit to or deny any of the allegations as part of the offer. Theranos dissolved quickly right after.

In her trial, Holmes alleged she was in the midst of a 10 years-very long abusive romance with her then-boyfriend and Theranos COO Ramesh “Sunny” Balwani though working the organization. Balwani, she alleged, tried using to regulate practically each component of her lifetime, which includes disciplining her having, her voice and her image, and isolating her from other folks. (Balwani’s lawyers denied her promises.)

In July, Balwani was located guilty on all 12 fees in a separate trial and faces the same possible most prison time as her. Balwani is scheduled to be sentenced on December 7.

“The results of Holmes and Balwani’s fraudulent perform were far-achieving and serious,” federal prosecutors wrote in a November court submitting pertaining to Holmes’ sentencing. “Dozens of investors missing about $700 million and many sufferers gained unreliable or wholly inaccurate medical info from Theranos’ flawed tests, putting people patients’ health at critical hazard.”

Additional than 100 men and women wrote letters in support of Holmes to Davila, inquiring for leniency in her sentencing. The list involves Holmes’ husband or wife, Billy Evans, lots of users of Holmes’ and Evans’ households, early Theranos investor Tim Draper, and Sen. Cory Booker. Booker described meeting her at a supper several years just before she was billed and bonding around the fact that they ended up both of those vegans with almost nothing to consume but a bag of almonds, which they shared.

“I however believe that she retains onto the hope that she can make contributions to the life of others, and that she can, regardless of mistakes, make the entire world a much better place,” Booker wrote, noting that he proceeds to take into account her a close friend.

Ahead of the hearing, there were being also questions over how Holmes’ sentencing could be complicated by developments in her life after stepping down from Theranos. Holmes and her partner, Evans, who achieved in 2017, have a youthful son. Holmes is also expecting, as confirmed by recent court docket filings and her most recent court docket overall look in mid-October.

Mark MacDougall, a white-collar defense law firm and former federal prosecutor, informed CNN Business ahead of the listening to that the simple fact that Holmes has a youthful youngster could affect how she is sentenced.

“I really don’t know how it simply cannot, just because judges are human,” he stated.

MacDougall also reported he does not see what a extended jail sentence accomplishes. “Elizabeth Holmes is under no circumstances heading to run a huge corporation all over again,” he claimed. “She’s never ever likely to be in a placement to have a thing like this occur all over again.”

Are Financial Literacy Programs Actually Helping Kids Learn About Money?

Are Financial Literacy Programs Actually Helping Kids Learn About Money?

When universities are proper to target on instructing young ones the fundamentals of looking through, producing, math and science, the symptoms we desperately need to have to train personalized finance before in lifestyle are in all places. After all, typical savings costs are definitely paltry across the board, and various studies (such as this a person) present most People in america usually are not investing sufficient (or often plenty of) to retire on their personal terms.

Credit score card debt is also a significant problem, as are college student loans, and the surging costs of month-to-month car or truck payments. By giving personal finance education in educational institutions, states and municipalities can prepare young ones to make smart monetary conclusions when it issues most.

Some states have even passed laws requiring finance education and learning in schools, and a number of famous people are presenting their own courses. For instance, Philadelphia 76ers superstar James Harden announced he’ll use his nonprofit — referred to as the Effects 13 Foundation — to enhance economic literacy costs amongst youthful grownups.

With all this in head, we have to question if these plans are really helpful when it arrives to supporting youngsters understand about cash. We should also be worried that some of these packages are essentially becoming developed as direct generations for wealth management corporations.

There are a large amount of robust thoughts when it arrives to children finding out about income in university, and exactly who must instruct these programs if they’re supplied in the first location. I attained out to various professionals to get their just take on economical literacy packages in faculties, and here’s what they reported.

Fiscal Literacy Programs Teach Necessary Life Classes

Debbie Pierce, who serves as the President and CEO of Economic Literacy Colorado, states that the lifestyle competencies taught in personalized finance classes will in the long run be applied by all learners all over their lives, no matter if they know it or not. For example, everybody will eventually have expenditures to shell out and budgets to manage, and anyone will eventually hope to retire just one day.

“If university is to put together college students for daily life, why is not individual finance an critical course?” she asks.

Pierce provides that pupils who do not study about individual finance in college have a slender likelihood of becoming taught economic necessities at property. In the end, this leaves also a lot of students slipping by way of the cracks and obtaining to understand in the “School of Tricky Knocks,” she suggests.

Sad to say, there are frequently difficulties when it will come to getting instructors for the courses. Pierce states the greatest obstacle in Colorado is not possessing more than enough lecturers to teach the necessary classes in a lot of school districts, “much considerably less the elective classes.”

She provides that this is primarily correct in rural districts, which make up 75{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Colorado university districts.

Economical Instruction Is Crucial For Our Changing Entire world

Dr. Jaime Peters of Maryville College factors out that so a lot of of the financial lessons from the very last 100 a long time no longer utilize. As an instance, Dr. Peters claims that persons are now in demand of their very own 401(k) programs, whereas workers yrs ago had pensions to rely on. On prime of that, dollar expenditures have been changed with debit and credit history playing cards, and immediate deposits and computerized payments make it simpler to spend and much more difficult to observe our total investing.

“It is no for a longer period what is in your wallet – it really is what is in your application,” she says.

With this in brain, the way engineering has transformed our financial method has made monetary literacy into a “vital everyday living skill,” she says.

We are working with cash differently, yet kids nevertheless need to have to understand economical basic principles such as “spending oneself very first” and dwelling below your usually means. Without financial education and learning in schools, children may perhaps never learn these classes at all.

Financial Literacy Applications Are Not Great

That mentioned, Dr. Peters states that economical literacy programs undergo from the very same fate as so many other well-intentioned programs.

“It is excellent content at the erroneous time,” she states.

For instance, large school learners are not in the sector for credit playing cards or home loans. And even though university pupils might have careers and automobile payments, “they are much from needing to know the ins and outs of how to pick the suitable health insurance.”

Nonetheless, it is really possible that classes realized about finance in college can stick with learners for yrs right up until they need them. So, learners who go as a result of fiscal plans could not know precisely how to navigate finance as an grownup, but they may well acquire a fundamental knowing and be far more self-confident in asking questions, claims Dr. Peters.

Fiscal advisor Josh St. Laurent of Wealth In You adds that sometimes the length of the plan is an challenge far too, and that 50 percent-day financial literacy workshops are usually not more than enough.

“A couple of several hours of charts and graphs is insufficient to affect behavioral change in students,” he suggests, incorporating that there requirements to be a actual environment ingredient in which they can examination ideas with their have money and by their have actual-planet lens.

Fiscal therapist Lindsay Bryan-Podvin, who is the author of The Monetary Panic Solution, adds that some university-dependent plans put too a great deal emphasis on strategies, definitions, and regulations, and not more than enough on taking care of money in authentic everyday living, together with the feelings and funds stories that arrive into perform.

She adds that this is equivalent to overall health schooling in the United States. There’s more emphasis on what well being is, but our health and fitness results are not that excellent.

“You can train a person that fruits and vegetables and daily walks are good for them, but if they dwell in a food stuff desert the place it truly is unsafe to go for walks, it will not do considerably good,” she claims.

Some Conflicts Of Fascination Exist

Some could possibly also be weary of money companies producing programs for educational facilities, and for great reason. Just after all, a financial advisory business could conveniently tailor in-college financial education in a way that it creates potential customers for them in the long term, or at least introduces youthful folks to their manufacturer early on.

As an instance, MassMutual delivers FutureSmart — a countrywide initiative that teaches economic lessons to middle and superior university students, as perfectly as households and educators. They stage to results in a research from Journal of Economical Counseling and Arranging as some of the core motives monetary instruction in universities is necessary, including the simple fact that 90{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of college students who took a one-time FutureSmart course “experienced expertise achieve.”

Probable for conflicts or not, it does appear like a purely natural match for economical companies to generate economical literacy programs — at least, as extensive as they are not designed to push specific money solutions. For example, FutureSmart curriculum consists of details on “how to accomplish significant objectives around preserving income, budgeting, education, and career preparing.”

These lessons can be useful for any college student who is suitable to participate, no matter of which enterprise is assisting fork out for the method.

Base Line

Whilst fiscal literacy classes provided in educational facilities could not be perfect, most professionals seem to be to concur they’re much better than practically nothing. And for some students, the lessons on budgeting or conserving they find out in university may well be the only monetary instruction they at any time receive.

In the long run, that is why some states are pushing to make fiscal literacy mandatory, and why more states will probably comply with their lead. No matter of how imperfect these plans are, or who pays for their generation, all of society added benefits when young men and women get the chance to discover financial fundamentals they may possibly not understand at residence.

Does Your Business Need a Refresh? Experts Share Their Top Tips

Does Your Business Need a Refresh? Experts Share Their Top Tips

If you’ve been working your business enterprise for a although, you in all probability have plenty of properly-founded procedures in area. Though these can enhance efficiency, they can also make things a minor stagnant. If your small business could use a refresh this year, read on for suggestions from users of the on the web smaller enterprise local community.


Freshen Up Your Business

It’s effortless for business owners to get caught in a rut when operating on day-to-working day functions. But just about every period, it aids to do some refreshing to aid your brand stand out. Ivan Widjaya gives swift suggestions for refreshing your business this year.

Develop an Unfailing Model Id

Your brand should be the two potent and uncomplicated for consumers to acknowledge. This will take tons of intentional style get the job done upfront, and any time you choose to refresh your organization. Master additional about brand id layout in this 300 Brain submit by Asha Rajput.

Decide on a Model Colour Palette That Suits Your Small business

Shade absolutely isn’t the only model layout element that matters to businesses — but it is an essential just one. So how do you choose shades that basically go well with your organization? Get insights in this Ignite article by Poulomi Basu.

Make the Most of WordPress 6. Features

Your site is just one of the most important factors of your organization. So the platform you host and run it from can make a big effects. WordPress is one particular of the top rated site resources, and it a short while ago acquired an update with some new attributes. See how to make the most of them in this Running a blog Unplugged write-up by Jasmeet Singh.

Choose Your Franchise Business enterprise to the Subsequent Level

Enterprise progress is not just reserved for impartial startups. Franchisees also want to be innovative and issue-solve to get to the up coming level. Joel Libava shares tips for accomplishing just that in this Franchise Direct post. And the BizSugar group chimed in with their possess thoughts below.

Determine Your Advertising ROI

If you want to increase your business, you first have to have to understand what’s working and what is not. When it will come to advertising, this requires calculating the ROI of your recent approaches. Whether or not you function with an company or not, the ideas in this Statusbrew put up by Abi Ramamoorthy may perhaps be useful.

Attain A lot more with a Goal-Placing Planner

Regardless of whether your objective is to refresh your brand name or increase in other approaches, you need a very clear prepare. Composing points down is a person of the most successful approaches to get clear on what you have to have to do. Moss Clement of Moss Media elaborates on this strategy in this article.

Evaluate the Greatest Resources for E-mail Automation

E-mail advertising is continue to pretty potent for modest firms. But the resources you signed up for when you 1st started your business may perhaps no lengthier go well with your demands. See a entire checklist that compares the top selections in this Blogging Wizard put up by Adam Connell. Then head to the BizSugar group to see feedback from other smaller business proprietors.

Get Previous Written content Advertising and marketing Struggles

It is ordinary to battle with numerous marketing strategies periodically – which include material internet marketing. But when you recognize these struggles, it is typically time to reevaluate and refresh your present system. In this Pixel Productions post, Mark Bingham details what to do when you struggle with written content internet marketing.

Improve Your Social Media Engagement

Engagement is king on social media. Not only does it signify that likely customers are interacting with your model, but it can also boost your visibility thanks to algorithms. To stage up your recent engagement prices, examine the guidelines in this Sked Social weblog by Kyra Goodman. Then head more than to BizSugar to see what users are stating.

If you’d like to propose your most loved modest company content to be regarded as for an forthcoming group roundup, please mail your news guidelines to: sbtips@gmail.com.

Image: Envato Elements


How you can get a $500 flat, no-interest loan at Wells Fargo

How you can get a 0 flat, no-interest loan at Wells Fargo

How

Wells Fargo announced a new short-term, small-dollar loan for customers. The $250-$500 loans could help lower-income customers avoid riskier ways of getting short-term cash, one group says.

NYT

Wells Fargo has launched a new kind of loan that offers customers short-term cash for a flat fee — adding to a slowly growing list of cheaper, less risky financing options for cash-strapped customers.

The bank announced the new product, dubbed “Flex Loan,” on Wednesday. It’s a $250 or $500 digital-only loan that customers can apply for on their smartphone, and comes with a flat fee of $12 or $20, respectively. Borrowers pay their amount back in four monthly installments, with no interest.

It’s already available in select markets, and launching in all states in the next four to six weeks, bank spokesman Josh Dunn told The Charlotte Observer Thursday. Flex loans are available only to Wells Fargo customers — the bank uses factors like account management practices, tenure and balances to determine eligibility, rather than using an independent credit bureau.

The loan is meant to be a quick and simple way for customers to directly access funds when they most need them, the bank said in a news release, without applications, hidden fees, late charges or interest.

The Flex Loan is similar to other small, short-term loans that U.S. Bank or Charlotte-based Bank of America offer, sometimes marketed as a cheaper alternative to overdraft fees.

Such loans also function as a good alternative to riskier methods of obtaining short-term cash, said Alex Horowitz, a lead consumer researcher at The Pew Charitable Trusts. He’s been tracking the ways these types of small loans can help lower-income bank customers avoid turning to more harmful options, like payday lenders charging triple-digit interest rates.

“Consumers have turned to (options like) payday lenders, because they haven’t been able to borrow small amounts from their bank,” Horowitz said. “But (these loans) are faster, they cost at least 15 times less, and they’re more affordable. So that’s a win for consumers.”

CLT_BuildingMugs1_4.JPG
Wells Fargo, one of Charlotte’s largest banks, isn’t the only bank to offer small-dollar, short-term loans to customers. Bank of America and U.S. Bank have similar programs. Arthur H. Trickett-Wile atrickett-wile@charlotteobserver

A payday loan alternative

Horowitz primarily looks at how small-dollar loans like Wells Fargo’s new product contrast with payday loans, which are short-term high-interest loans that many consumers take out in hopes of paying off with their next paycheck.

But those two-week loans often create more problems than they solve, Horowitz said. Sky-high interest rates — some as high as 400{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} — can leave borrowers drowning in debt for months.

“We know that when payday loan customers are in distress, they don’t focus on price or affordability. They focus on speed, ease of access and certainty of approval,” he said.

Compared to those kinds of loans, Wells Fargo’s small-dollar offering costs about 15 times less, he added.

Payday lending is outlawed in North Carolina, and about half the states, but there still are a number of other risky, high-interest financing options out there, Horowitz said. Major banks’ small-dollar loans could help low-income customers avoid pawn shops or taking out other small loans with five times the interest rate.

“All states have pawn shops. All states have rent-to-own stores,” he said. “Some customers overdraft their checking account repeatedly as a way to borrow small amounts of money. These new loans are a more affordable option than that.”

CLT_ALS_Wells_001.JPG
Wells Fargo is based in San Francisco but has its largest employment base in Charlotte, with some 27,000 workers here. Alex Slitz alslitz@charlotteobserver.com

Other banks offering small loans

Wells isn’t the only local bank to offer a small-dollar, low-cost loan.

In 2020, Bank of America launched a similar product called “Balance Assist.” It allows customers to borrow up to $500 for a $5 flat fee, paid in three monthly installments.

Other banks with small-dollar loan programs include Ohio-based Huntington Bank and Minneapolis-based U.S. Bank, which has a handful of branches in Charlotte.

The loans are relatively low risk products for the banks, Horowitz said. “The bank is lending to known customers,” he said. “There’s a track record here. Even customers with low credit scores are successful in repaying when they can do so in affordable installments at fair prices.”

Plus, the loans’ tiny size means they’re still a small liability for banks – compared to something like a mortgage, Horowitz noted, which is nearly 100,000 times larger

He’s also confident that customers will make use of these types of loans: when Pew surveyed current payday loan borrowers, eight in 10 said they’d switch to using small loans at their bank.

Dialing back on overdraft fees

Bank of America and Wells Fargo also have marketed the loans as a more consumer-friendly alternative to overdraft fees.

Bank of America, Wells Fargo and other banks have started offering more options for lower-income customers after their practice of charging overdraft fees drew sharp criticism from lawmakers, especially during the pandemic.

Critics argued the fees were boosting banks’ profits at the expense of customers who could least afford it. In response, several banks ditched the fees, reduced them or offered options like overdraft-free checking accounts or small loans.

Horowitz hopes to see additional banks offer similar products. The more banks that offer short-term, small loans, the better chance their customers will have of avoiding the worst, he said.

“It can help them avoid other bad options: getting their utilities disconnected or having their car repossessed or being evicted,” Horowitz said. “If an affordable small loan from a bank can help someone avoid those harmful outcomes, that’s a win for consumers too.”

Related stories from Charlotte Observer

Profile Image of Hannah Lang

Hannah Lang covers banking, finance and economic equity for The Charlotte Observer. Her work has appeared in The Wall Street Journal, the Triangle Business Journal and the Greensboro News & Record. She studied business journalism at the University of North Carolina at Chapel Hill and grew up in the same town as her alma mater.

Is Paysign (PAYS) Stock Outpacing Its Business Services Peers This Year?

Is Paysign (PAYS) Stock Outpacing Its Business Services Peers This Year?

The Business Providers group has a good deal of wonderful stocks, but traders should really often be hunting for firms that are outperforming their friends. Has Paysign, Inc. (PAYS) been one of individuals stocks this 12 months? Let’s get a closer seem at the stock’s 12 months-to-day general performance to come across out.

Paysign, Inc. is a single of 333 personal shares in the Business enterprise Services sector. Collectively, these providers sit at #9 in the Zacks Sector Rank. The Zacks Sector Rank gauges the strength of our 16 personal sector groups by measuring the normal Zacks Rank of the unique stocks in just the groups.

The Zacks Rank emphasizes earnings estimates and estimate revisions to uncover stocks with improving upon earnings outlooks. This procedure has a lengthy document of results, and these shares have a tendency to be on track to defeat the market place more than the following a single to a few months. Paysign, Inc. is at this time sporting a Zacks Rank of #2 (Get).

In excess of the past 90 times, the Zacks Consensus Estimate for PAYS’ complete-yr earnings has moved 33.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} greater. This reveals that analyst sentiment has enhanced and the firm’s earnings outlook is more powerful.

Centered on the most up-to-date available info, PAYS has gained about 68.1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} so much this calendar year. At the very same time, Company Solutions stocks have shed an regular of 28.6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. This displays that Paysign, Inc. is outperforming its peers so far this 12 months.

ShotSpotter (SSTI) is a different Small business Expert services inventory that has outperformed the sector so much this calendar year. Because the commencing of the year, the inventory has returned 16.2{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

For ShotSpotter, the consensus EPS estimate for the present-day year has improved 216.7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} about the past three months. The inventory at this time has a Zacks Rank #2 (Purchase).

Breaking matters down far more, Paysign, Inc. is a member of the Monetary Transaction Providers market, which includes 38 individual companies and at present sits at #152 in the Zacks Industry Rank. On average, shares in this group have lost 12.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} this calendar year, meaning that PAYS is doing superior in terms of calendar year-to-date returns.

ShotSpotter, even so, belongs to the Technologies Providers industry. At the moment, this 189-inventory marketplace is rated #131. The market has moved -48{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} so significantly this 12 months.

Buyers with an interest in Business Companies stocks should carry on to track Paysign, Inc. and ShotSpotter. These shares will be hunting to go on their good effectiveness.

Want the newest recommendations from Zacks Investment decision Research? These days, you can download 7 Finest Shares for the Following 30 Days. Simply click to get this totally free report
 
Paysign, Inc. (PAYS) : Free of charge Inventory Assessment Report
 
ShotSpotter (SSTI) : Cost-free Stock Assessment Report
 
To examine this short article on Zacks.com click on here.
 
Zacks Investment decision Study