Native Economic and Financial Education Empowerment (NEFEE)

Native Economic and Financial Education Empowerment (NEFEE)

The Native Economic and Economic Training Empowerment (NEFEE) system is a Federal Reserve Method exertion led by the St. Louis Fed to attain a historically underserved population with economic and economical education and learning. We guidance the prosperity of Native nations by offering economic and monetary education in partnership with Native partners and other Federal Reserve banking institutions who give economic and financial education and learning programming.

Supporting economic and economic very well-remaining

The Native Economic and Monetary Education Empowerment program brings together the public service mission of the Federal Reserve, its dedication to serving underserved populations, and its skills in financial education. Considering the fact that 2018, we have provided economic and personalized finance schooling for tribal nations and Indigenous communities and corporations through the country.

We think financial and own finance know-how will help foster resilient and balanced individuals, households and communities. We regard the special problems that tribal nations confront as sovereign governments to increase the economic effectively-currently being of their persons.

Our core do the job includes partnering with tribal nations to present economic and monetary training programming to their associates and citizens. We provide in-person and digital programming for Native educators build economics and individual finance curricula for use in classrooms and youth packages and conduct investigate to measure the efficacy of our courses.

Strengthening access to economic and private finance instruction

We are devoted to expanding alternatives for associates of Indigenous communities to develop financial capabilities, particularly for Indigenous youth. Investing in education for youth can have sizeable returns. Not only can it profit particular person younger men and women and their people, it can also assistance develop youth to be potential leaders and contributors to their communities by making ready them to make vital financial choices.

We believe that higher obtain to financial and economical education and learning aids progress a additional inclusive financial system for all.

We have comprehensive practical experience in training economics, personalized finance, curricula enhancement and conducting outreach to underserved communities. We deliver large-high-quality assets and experienced advancement to increase instruction. Our resources and qualified improvement programming are all cost-free.

Empowering just one generation right after an additional

In its function with tribal nations and Indigenous communities and corporations, NEFEE incorporates personal finance and financial instruction into a broad array of packages across generations, like courses for:

  • Early childhood schooling
  • Secondary schooling
  • Reservation schools
  • Youth work
  • College readiness
  • Larger education and learning
  • Workforce growth
  • Housing
  • Social expert services
  • Elder services

Honoring culture and language

We accept the importance of language and culture in instruction and worth prospects to spotlight them to far better engage Native learners and foster a much more inclusive understanding natural environment. We partner with tribal nations to include their Indigenous language and society within just curricula in a variety of formats.

Get in touch with us for additional info

Megan Cruz potential customers the NEFEE outreach effort.

megan.cruz@stls.frb.org
Megan Cruz

Central Financial institution Network for Indigenous Inclusion

The Federal Reserve Board declared on Oct. 13, 2021, that it joined the Central Lender Network for Indigenous Inclusion, which fosters ongoing dialogue, research and education and learning to increase consciousness of financial and monetary problems and chances for Indigenous economies.

The Board’s participation is supported by the Native Economic and Economical Education and learning Empowerment (NEFEE) system at the Federal Reserve Lender of St. Louis and the Center for Indian Place Enhancement at the Federal Reserve of Minneapolis. Together with Indigenous partners, the network is a collaboration with Te Pūtea Matua (the Reserve Bank of New Zealand), the Financial institution of Canada and the Reserve Bank of Australia.

Welcoming Remarks by Chair Powell at the Reservation Economic Summit 2022

Welcoming Remarks by Chair Powell at the Reservation Economic Summit 2022

Accessible Keys for Movie

[Space Bar] toggles participate in/pause

[Right/Left Arrows] seeks the online video forwards and back (5 sec )

[Up/Down Arrows] increase/lessen quantity

[M] toggles mute on/off

[F] toggles fullscreen on/off (Except IE 11)

The [Tab] critical may possibly be utilized in mixture with the [Enter/Return] critical to navigate and activate manage buttons, these as caption on/off.

Superior early morning, and welcome. It is a wonderful enjoyment to welcome all the attendees to RES 2022.

The Nationwide Heart for American Indian Organization Advancement has been a sturdy and steady lover to the Federal Reserve, collaborating with us on modest organization COVID surveys, serving on the Leadership Council for the Minneapolis Fed’s Middle for Indian Country Development, and moderating our policy webinar sequence on tribal enterprise diversification, just to identify a handful of.

Have confidence in is earned and produced via interactions. This is especially vital in Indian Country. The Federal Reserve has created an enduring and sturdy bond with the Nationwide Centre, and we benefit that partnership.

We are excited to be taking part in this year’s convention, studying together with you. There is undoubtedly a lot more investigate and engagement to be carried out on the precise and exclusive financial needs of tribal nations and Indigenous communities. RES 2022 is a great assembly floor for this sort of collaboration.

The very best perception and evaluation arrive from persons who dwell and do the job in communities and have an inside of check out of the struggles and opportunities within just. The Federal Reserve Program has built a precedence of engaging with leaders and stakeholders on prospects most suitable to tribal financial prosperity. For example, enter from tribal stakeholders has been a must have to informing the essential operate of modernizing the Community Reinvestment Act, which was integrated into the recently released proposal that we are wanting ahead to receiving opinions on. We also price the rising illustration of tribal voices on our boards of directors and advisory councils at Reserve Financial institutions, aiding us to much better comprehend financial circumstances in Indian Nation.

Lots of of you are aware of the Middle for Indian Nation Development (CICD), our countrywide institute dedicated to helping tribes achieve their whole economic opportunity. We are fired up to be increasing its capacity to conduct financial research and information investigation to assist the long-expression economic prosperity of Indian Country, in partnership with Indian Place. We look ahead to CICD’s ongoing collaboration with tribal communities on study and data.

Moreover, an preliminary St. Louis Fed partnership with the Osage Nation, to supply youth monetary training, has led to partnerships with tribal governments across the country that provide personalized finance education, generally in their Native languages. Tribal leaders nationwide have also joined latest listening periods to focus on the impacts of inflation. Identical classes were held on our pandemic response amenities, which were adapted following hearing their input.

Other Federal Reserve partnerships with Indian State include initiatives on access to credit rating Native local community enhancement monetary establishments economical instruction applications customized to early childhood, secondary, and bigger training workforce enhancement housing social products and services and elder programs.

And as section of our ongoing exertion to deepen our comprehending of tribal economies, previous calendar year, the Federal Reserve Board announced that we had joined the Central Financial institution Network for Indigenous Inclusion, along with the Reserve Financial institution of New Zealand, the Lender of Canada, and the Reserve Bank of Australia. This is part of our dedication to learning best methods and expanding our international partnerships with central banking institutions that are in the same way invested in supporting Indigenous folks and communities.

The Federal Reserve is effective for all of us, and our investigation and assessment will have to mirror the distinct requires and instances of all of our communities. I am grateful for our partnership with the National Center for American Indian Business Development, and I want to thank you, as properly as all our colleagues, advisors, and stakeholders who enable us perform toward a stable and inclusive financial system for all.

Thank you.

Bellco Credit Union and Economic Literacy Colorado Celebrate Financial Literacy Month with New “FUNancial $marts” Educational Book for Middle Grade Students

Bellco Credit Union and Economic Literacy Colorado Celebrate Financial Literacy Month with New “FUNancial $marts” Educational Book for Middle Grade Students

Booklet Delivers Tweens/Teens with the Principles of Taking care of Dollars

DENVER, April 26, 2022 /PRNewswire/  Economic Literacy Colorado (EconLitCO) and Bellco Credit score Union are celebrating Economic Literacy Month by launching a new “FUNancial $marts” instructional exercise reserve for students in grades 6-8 that teaches them the principles of managing revenue. The booklet is becoming distributed through Bellco branches, as well as by way of supplemental local community partnerships.

“FUNancial $marts” for center schoolers features things to do about genuine world money situations, making good decisions about buys, and means to comparison shop. An electronic variation is also out there for obtain at this website link.

“Developing short- and long-term fiscal routines and abilities direct to better economical very well-getting. And making certain that young folks in our group have the important lifestyle abilities they require to succeed is a major precedence for Bellco,” stated John Rivera, senior vice president and main retail officer at Bellco Credit history Union. “We are proud to lover with Financial Literacy Colorado for the 3rd calendar year and assist their initiatives to equip academics with the information and facts and products they want to carry financial empowerment to their lecture rooms.” 

“Individual finance and elementary economics are vital capabilities that each pupil will use all through their life. We had wonderful success with the K-5 “FUNancial $marts” action book  and are excited for the new ebook geared towards center college students,” mentioned Debbie Pierce, president and CEO of EconLitCO. “We encourage Coloradans to challenge them selves and their kids by expanding recognition and education and learning all-around economics and financial literacy, awareness that is crucial to getting prosperous users of our no cost company technique.”

April was dubbed Monetary Literacy Thirty day period in 2004 with hopes of elevating community awareness of the importance of knowledge own finance and the effects affiliated with very little to no financial education. In 2019 Bellco teamed up EconLitCO to create “FUNancial $marts” for elementary college students. The elementary action e book incorporates collaborative classes of counting income, budgeting, and generating a company. With the enable of a trainer, guardian, or relatives member, FUNancial $marts can equip younger men and women with know-how to make educated decisions and get ready them to deal with economical and financial issues in their future. An electronic edition of the K-5 e-book is also offered for obtain on the Bellco internet site.

EconLitCO has quite a few methods obtainable which includes distant mastering for mom and dad and learners, personalized finance literacy, information and routines, and much more. To accessibility these methods and upcoming classes, check out ELC’s web page at econlitco.org.

About Bellco

Bellco is just one of Colorado’s biggest fiscal institutions, with more than $6 billion in property and 26 branches in Colorado. Founded in 1936, Bellco features a full selection of economic items and providers including home fairness loans, automobile financial loans and checking accounts. Currently, Bellco has more than 350,000 associates who reward from the advantages of a credit score union, such as reduced interest rates on financial loans, higher yields on personal savings and access to thousands of ATMs nationwide. Hook up with Bellco on Fb and Twitter. Bellco is federally insured by NCUA and is an Equivalent Housing Financial institution.

About Economic Literacy Colorado

Economic Literacy Colorado empowers Colorado college students to realize a lifetime of economic understanding and economic protection by providing financial and personal economical education to academics and their students as a result of packages and college-accredited qualified growth. To study additional, please take a look at www.econlitco.org and stick to Economic Literacy Colorado on Facebook, Twitter and LinkedIn.

Media get in touch with: Amy Moynihan
[email protected]

Resource Bellco

Financial education in Minnesota schools could help reduce economic disparities

Financial education in Minnesota schools could help reduce economic disparities

Hodan Hassan life in a person of the most numerous places in Minnesota.

Her Minneapolis neighborhood consists of East Africans, Native Us residents, Black individuals, white men and women and people from other ethnic and racial backgrounds.

Hassan immigrated from Somalia far more than two many years back. She’s a psychological wellbeing clinician and a self-explained social justice advocate who also signifies the location in the Minnesota Home as a DFL condition consultant.

Hassan problems that a lot of of her youthful constituents and other students all over Minnesota are not obtaining ample information in faculty about how to deal with revenue.

“I completed significant faculty with no figuring out nearly anything about private funds,” reported Hassan, 40, who mentioned she learned the tricky way.

A woman smiles for a photo in a restaurant setting.

Rep. Hodan Hassan, DFL-Minneapolis, would like a private finance training course to be a graduation prerequisite for Minnesota high schoolers.

Mark Zdechlik | MPR Information

“I went to college and acquired myself into a whole lot of credit card debt, and I considered I was the only particular person that was battling with handling individual funds,” Hassan stated. “Then I talked to some of my pals who are possibly immigrants or from communities of coloration, and I understood that numerous of us ended up battling with this since funds is not a thing that family members with decreased socio-economics converse about.”

There is no prerequisite in Minnesota that learners take a stand-by yourself system on own finance. Hassan is pushing laws that would have to have all college students to get this sort of a course ahead of graduating.

In Minnesota, communities of colour persistently lag the greater part white inhabitants in income, work, home possession and other measures of prosperity. There are likely numerous explanations for that, but Hassan and many others believe that educating students about economic literacy might enable get started to adjust it.  

Even nevertheless you can find no mandate, several Minnesota schools offer some personalized finance education. But as opposed to English, science, math, and social scientific tests there are no benchmarks as to what need to be taught.

Some colleges, which includes Woodbury Significant College, supply a course as an elective credit history.

Greg Waugh enthusiastically teaches the class, which he said is one particular of the most well-liked electives at Woodbury Superior School.

“When you have an emergency fund in spot, all of the other stresses in your existence have a tendency to be more negligible,” Waugh stated to his learners. “Everything is just significantly less mainly because you’ve got acquired that dollars again there as a protection blanket to you — recognizing if everything goes improper, you have obtained something to slide back on.”

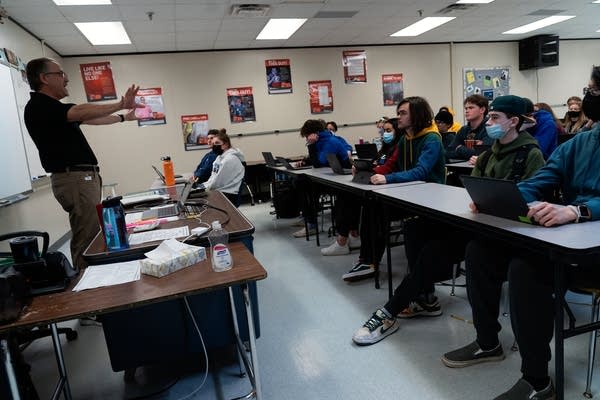
Students listen as a teacher speaks to them in class.

Greg Waugh, left, teaches economic literacy to Woodbury Superior Faculty students in the hope of instructing them how to stay away from the pitfalls of personal debt.

Judy Griesedieck for MPR News

Waugh mentioned his passion for individual finance education is rooted in his own issues. Ahead of becoming a instructor Waugh was a large-earnings salesperson paying out much more than he attained. He finished up divorced, laid off and broke.  

“I think if pupils understand at a young age, if they’re just sensible with the income that they have and the cash that they have, whether or not they go to college or university or regardless of whether they never, they can be wonderful,” Waugh explained. “They can build wealth and they can be delighted and do the items they want to in everyday living.”

Lessons like Waugh’s are turning out to be a lot more well-known throughout the nation, according to Billy Hensley, the president of the Countrywide Endowment for Financial Education and learning

“People are truly waking up to the simple fact that our economical landscape is considerably extra intricate,” Hensley claimed. “You know, we went from a culture exactly where a bulk of personnel experienced accessibility to pensions and so forth. And now we all have to be the CFO of our retirement as perfectly as the CFO of our fiscal life.” 

Breaking the cycle

Firms have CFOs — Chief Economical Officers — but most of us are on our have when it arrives to controlling the value of wellbeing care, using credit history cards, performing taxes, acquiring a household or a car or truck, preparing for retirement and even obtaining plenty of income on hand to obtain groceries.

John Pelletier, who runs the Center for Economical Literacy at Champlain University in Vermont, tracks and grades the way own finance skills are taught in large universities throughout the country.

He applauds Minnesota’s go toward becoming a member of extra than 10 other states which have imposed personal finance substantial college graduation mandates. Which is almost 2 times as lots of as five several years ago, Pelletier pointed out.

Like Hassan, Pelletier talks about own finance instruction in the context of fairness and the cycle of poverty.

“And if you want to split that cycle, I believe you have acquired to get this information to people who I feel want it the most,” Pelletier stated. “Who are people who are the poorest? And as the details displays, minorities are likely, on typical, to be in that weak category. And so they are struggling.”

Supporters of mandating own finance training for higher university pupils generally position to research carried out by Montana Condition University economics professor Carly Urban.

By comparing states, Urban has demonstrated when adolescents are taught own economic administration expertise, they change their cash management habits for the superior.

“So their credit score scores are better following they’re necessary to acquire economical literacy classes in large school,” Urban explained. “Also, they’re a lot less most likely to be delinquent on any of their outstanding debt, which once again, is a superior thing. And then a really exciting locating, in my intellect, is that for students who go on to submit-secondary schooling, they are borrowing smarter.”

Students listen as a teacher speaks to them in class.

Senior Kenna Smutny listens intently in the course of a significant school class taught by Greg Waugh. “Preserving is a operate of self-discipline, not about how considerably money you make”, Waugh tells them.

Judy Griesedieck for MPR Information

‘It’s an issue of this era’

Republicans and Democrats are progressively in unusual arrangement when it will come to imposing economical literacy demands for significant faculty graduates.

Last month Florida Gov. Ron DeSantis signed a invoice mandating individual finance schooling as a graduation necessity after it passed each residences of the Florida Legislature unanimously.

“It’s an embarrassment if our substantial educational facilities and even our center educational facilities will not recognize that individual finance is really significant to the college students,” reported Minnesota Rep. Sondra Erickson, R-Princeton. Even though Erickson supports personal finance schooling, she was one of two Republicans to vote in opposition to the monthly bill in the Property Instruction Committee. 

“It’s best if we depart it up to the locals as an alternative of mandating it,” Erickson stated. “I definitely honor that area management and feel that our districts can make that selection. If we leave this up to districts, they may well do a superior job.”

Hodan Hassan countered that without the need of a statewide mandate, a lot of younger folks are heading to continue lacking out on critical individual finance abilities.

“It’s a social justice issue. It truly is an equity situation,” Hassan said. “It’s an difficulty of this era.” 

You make MPR Information probable. Personal donations are driving the clarity in coverage from our reporters across the state, tales that join us, and conversations that deliver perspectives. Assistance guarantee MPR remains a resource that provides Minnesotans alongside one another.

Visa and the Council for Economic Education team up to support student financial literacy

Visa and the Council for Economic Education team up to support student financial literacy

Visa announced in late March that it is co-founding a coalition of local community leaders, non-profits, and company partners termed FinEd 50 in partnership with the Council for Economic Education (CEE). The goal of FinEd 50 is to enhance access to excellent money schooling for learners in the US.

According to the CEE’s 2022 study, which calculated the economic and personalized finance education taught in US educational institutions, only 27 states mandate a personalized finance class for students, and individuals programs change in top quality. 

“The united states is failing our children when we will not deliver them with options to review significant financial and personal finance concepts before they go away superior school for university, for jobs, and for their futures,” mentioned Nan J. Morrison, president and CEO of CEE, in the push release. “Whilst we are encouraged by some progress in our most recent Survey, all youthful people across the state want more and ought to have much better.”

In accordance to the council, money education is an vital aspect of younger people’s education. Utilizing digital channels and classroom lessons to aid economic literacy will established them up to properly price range themselves and place them to make excellent economic choices. This looks especially critical for school-sure college students as they prepare to consider on student loans.

The Nationwide Economic Educators Council (NFEC) recently discovered the results of their checks that measure monetary literacy across quite a few age groups. The College student Mortgage Test identified that, of the 8,904 higher education students and college-bound learners that participated, there was a failure charge of 66{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and an regular score of 59{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Also: Absolutely everyone from Gen Z to Boomers could use extra monetary training: NFEC analyze

The test’s concerns cover a variety of university student financial loan-connected subjects, like what is actually the best student financial loan type to select, what is forbearance and deferment, and what are the implications of defaulting on the bank loan, between other folks. Thinking about the concerns questioned, the effects develop into even far more worrisome.

“For numerous graduates, acquiring the desire of earning a higher education degree will come with pupil loan personal debt that can derail their finances. Present-day youth are persistently encouraged to go to school, but in no way acquire a economic training. As a result, they make the major financial investment of their lifetime to day with minimal or no knowledge about how to assess student loan decisions, and no system to pay back the money they borrow,” Vince Shorb, NFEC CEO, claimed on the exam final result page.

With the development of the FinEd 50, Visa and the CEE hope to modify these effects. In accordance to the press launch, the coalition has four principal targets: 

  1. Produce condition-degree action to assure each individual student has entry to equitable individual finance courses
  2. Be certain curriculums adhere to the Nationwide Requirements for Personal Financial Education and learning
  3. Deliver educators with specialist enhancement by means of “innovating funding mechanisms” 
  4. Give a resource to observe access and guarantee software equity

“The state of economic schooling available to learners in the US varies substantially. Wherever college students dwell really should not impression irrespective of whether they have access to knowledge that will support them discover how to make knowledgeable fiscal selections in their life,” claimed Worku Gachou, head of North The usa, inclusive affect & sustainability, at Visa in the release.

Business confidence at 10-qtr high as demand, economic activity picks up, shows Business Today-C fore survey

India Inc’s company sentiment rebounded strongly in Q2 of FY22 together with the ebbing affect of the COVID-19 pandemic, in accordance to the most recent Enterprise Now-C fore Business enterprise Self-assurance Index (BCI).
 
On a scale of 100, the index jumped to 49.6 in the July-September quarter (Q2) of FY22 immediately after touching its lowest place at 43.2 in the April-June quarter (Q1) of the recent fiscal year. 
 
The BCI, dependent on The Small business Nowadays-C fore Enterprise Self esteem Survey, even further shows the business sentiment has moved up throughout all businesses — major, medium, tiny and micro — and touched its greatest issue in the very last 10 quarters.

Also Examine: Economic restoration gaining momentum, progress viewed across sectors: Finance Ministry
 
Aroon Purie, Editor-in-Chief, India Today Group, of which Business These days is a section, says the latest study highlights strong optimism amongst businesses.
 
“Small business sentiments ended up falling for several quarters, but the most recent BCI has skyrocketed to break a 10-quarter history. Whilst the study outcomes give clean hope, we have to have to stay notify for close to-time period troubles this sort of as the coal crisis, and increasing commodity charges,” Purie notes.
 
The index even further signifies that as the economy opens up and companies get back again to regular, India Inc’s honchos are experience far better about the condition of the economic climate as well as business. 
 
The increase in July-September BCI is a immediate end result of an uptick in the economic action in excess of the previous quarter. The unlocking of just about all companies after the second COVID-19 wave, adopted by the pickup in need, has improved the outlook of organization leaders, in accordance to the survey.

Also Examine: Indian economy poised to attain double-digit advancement in FY22: PHDCCI
 
The BCI is dependent on a survey done with 500 CEOs and CFOs of companies across big, mid-sized and little organisations throughout 12 metropolitan areas — Delhi, Mumbai, Chennai, Hyderabad, Bangalore, Kolkata, Chandigarh, Lucknow, Nagpur, Kochi, Vizag and Bhubaneswar.
 
The study, performed concerning September 28 and October 4 is portion of the October 31 situation of the Business enterprise These days journal, which is on stands now.
 
For the September quarter, the ratings on all five parameters incorporated in the study — all round financial circumstances, monetary scenario, need circumstances, profit margins, and selecting problems — are improved than the earlier research.
 
The outlook for the upcoming quarter — October-December 2021 — is also favourable throughout all parameters, the study suggests.
 
It even further details out that 80 for each cent of company leaders are monetarily well prepared to deal with a possible 3rd COVID-19 wave. A different 45 per cent believe the government’s asset monetisation pipeline would present a sturdy boost to financial activity and employment.  
 
Meanwhile, 63 per cent of respondents do not anticipate the charge of funds or curiosity outgo to raise around the following one yr, when 76 for each cent say the rollback of the moratorium and two-yr mortgage restructuring, delivered by the Reserve Lender of India (RBI) and the governing administration, would boost the economic pressure in the technique.

The Organization Nowadays-C fore Business enterprise Confidence Survey, which captures the mood of company India, has come to be a bellwether of small business and financial sentiment given that its inception in January-March 2011.