Education Department Safeguards Needed to Help Student Loan Borrowers as Servicers Leave Program

Education Department Safeguards Needed to Help Student Loan Borrowers as Servicers Leave Program

The pandemic-connected pause on federal pupil financial loan payments, which began in March 2020, has been important in serving to borrowers throughout a period of economic disruption. Every time the pause finishes, lots of borrowers will have to navigate economic troubles and an generally-bewildering reimbursement program. These complications could be magnified by the departure of 3 federal scholar loan servicers, a change that will drive hundreds of thousands of borrowers to get the job done with new servicers when they make a payment, transform compensation plans, or look for aid when wanted.

Now, the Department of Instruction and servicers must acquire methods to restrict troubles in the account transfer and restart process by improving conversation with borrowers, guaranteeing that staffing at servicers is ample to meet borrowers’ demands, and placing safeguards in spot to secure debtors, particularly these whose financial loans have been transferred to new servicers.

Previous yr, two loan servicers—Granite State (the New Hampshire Larger Training Mortgage Corp.) and FedLoan Servicing (the Pennsylvania Larger Schooling Assistance Company, or PHEAA)—announced that they would not search for to extend their Schooling Section contracts. A third, Navient, declared a system in late September that would shift its servicer portfolio to yet another enterprise.

The servicers cited numerous reasons, such as a want to target on larger instruction initiatives in their respective states, as properly as considerations that the expenditures and complexity of their business enterprise designs had been no for a longer time sustainable. Federal University student Assist officers have instructed that forthcoming alterations to efficiency accountability specifications in servicing contracts also may have motivated servicers’ decisions to leave the market place.

The transfer course of action has by now started for some debtors. In September 2021, the department declared that accounts earlier serviced by Granite State would be transferred to EdFinancial, a federal scholar mortgage servicer headquartered in Tennessee. Officials said that debtors would be transferred in batches, with the adjustments anticipated to be finish by the end of 2021. To assistance, EdFinancial developed a internet site with info about what afflicted debtors can expect in the coming months.

The accounts for FedLoan borrowers are also remaining transferred. The division has announced that a small established of servicers, including the Missouri Higher Schooling Loan Authority (MOHELA), EdFinancial, and Nelnet, will get the accounts. FedLoan has been the sole servicer accountable for administering the federal Community Provider Bank loan Forgiveness (PSLF) program, which has had documented worries in recent yrs as the initial established of borrowers approached the forgiveness threshold.

In December 2021, the office announced that MOHELA would just take more than the PSLF software. Borrowers pursuing these kinds of mortgage forgiveness will continue to be with FedLoan right up until they are transferred sometime in 2022.

Beneath a particular agreement accepted by the office, Navient will transfer its whole federal pupil bank loan servicing operation—including employees—to Maximus, a servicer that beforehand worked only with defaulted borrowers ahead of their accounts were despatched to collections. This transfer is distinctive from the other types for the reason that it requires the shifting of an entire servicing operation in its place of only borrower accounts.

The system has previously led to some confusion amongst debtors, in part for the reason that they gained communications from an entity named “Aidvantage,” the recently made mortgage servicing arm of Maximus, as an alternative of Maximus itself.

Researchers analyzing earlier substantial-scale scholar bank loan account transfers have observed that the variations can produce hurdles to lengthy-time period compensation success. In the early 2010s, the department made a decision not to renew a deal with Affiliated Computer system Products and services (ACS). By 2013, most of ACS’s accounts experienced been transferred to new servicers. As in-depth in reports from the Purchaser Monetary Safety Bureau and much more modern nongovernmental analyses, these transfers developed difficulties for borrowers and servicers alike. Debtors described incorrect equilibrium and payment information though servicers noted lacking or incomplete speak to information for several accounts.

This history underscores how elaborate and puzzling the account transfer course of action can be for debtors and pupil mortgage servicers. Steering clear of borrower confusion will existing a significant problem for each the Department of Training and servicers.

To prepare for opportunity problems, the federal govt should assure that borrower communications are crystal clear and that protections are in area to rectify any mistakes that happen during the procedure. In addition, borrowers should really be shielded from undue penalties. To meet these aims, the section really should:

  • Build mechanisms to help debtors with transferred accounts. Units really should be in a position to establish and quickly take care of complications that come up as section of the transfer approach. If a challenge is discovered, debtors should be granted an automatic forbearance or grace time period when the section and servicer look into the situation. The department also could build a borrower hotline and committed e mail handle for people whose loans are transferred.
  • Make improvements to communication with borrowers. Information about the loan transfers must be apparent, actionable, and well timed. Concepts from behavioral economics can assistance the office focus on info and direction. Info about account transfers should really specify each the new business, and, if relevant, the unique entity that will attain out to debtors about generating payments. References to the Department of Schooling or Federal College student Assist really should look prominently in each and every conversation.
  • Offer further aid to servicers. Mainly because the transfer approach could induce borrower confusion, the division should really perform to increase resources and support for servicing team. It also ought to make sure implementation of not long ago announced accountability expectations to make absolutely sure that servicers are properly prepared for both equally the restart and account transfers, and that they are in a position to plainly connect crucial facts about the two to borrowers.

Travis Plunkett is the senior director of the family members financial steadiness portfolio, Regan Fitzgerald is a manager, and Brian Denten and Jon Remedios are senior associates with The Pew Charitable Trusts’ undertaking on scholar borrower accomplishment.
Thousands will have student loan debt canceled

Thousands will have student loan debt canceled

Countless numbers of people today with scholar bank loan credit card debt will have their personal debt canceled or get a 1-time check as aspect of a multistate settlement with a person of the nation’s largest scholar mortgage servicers.

Navient, the Wilmington-centered corporation, was accused of encouraging borrowers to pause payments by way of forbearance instead than directing them to decrease-price compensation strategies tied to their earnings. Though Navient denies the costs, the settlement ends probes by numerous states into the firm’s practices and will have an impact on hundreds of people today whose financial loans are serviced by Navient.

The loans in query were being generally originated by Sallie Mae involving 2002 and 2014 in advance of Sallie Mae spun off its college student financial loan products and services as Navient in 2014. The arrangement will final result in the cancellation of $1.7 billion in scholar financial loans. Another $95 million will be dispersed in restitution payments really worth about $260.

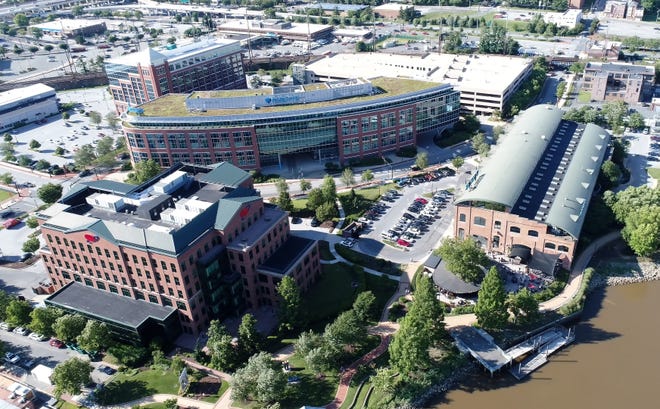
An aerial view of some of the businesses at the Wilmington Riverfront which includes AAA MidAtlantic and Navient.

Prior REPORTING: Delaware-centered Navient enters $1.85 billion settlement in excess of university student bank loan practices

How do I come across out if I will gain?

Individuals who will have private financial loan debt canceled will be notified by Navient no later on than July. They will get a refund for payments created right after June 30, 2021.

Debtors who are qualified for the $260 restitution payment will receive a postcard from a settlement administrator this spring.

Navient plans to cancel some student borrowers’ loan debt. Who qualifies?

Navient plans to cancel some student borrowers’ loan debt. Who qualifies?

Scholar debtors who took out financial loans that ended up serviced by Navient, a single of the most significant university student loan assortment organizations in the country, had been cautiously celebrating Thursday’s announcement that tens of 1000’s of them would get their loans canceled underneath an arrangement with more than three dozen states.

The overall amount of debt to be canceled, as very well as an accompanying restitution arrangement, is major — a offer well worth about $1.85 billion.

A bipartisan coalition of state lawyers general are calling the resolution “a victory for student bank loan borrowers” in holding Navient accountable, after suing the firm for allegedly deceptive debtors with misleading lending methods and featuring dangerous subprime financial loans. For its element, Navient is denying it violated shopper security laws or triggered debtors hurt, insisting it is settling the arrangement “to avoid the more load, expenditure, time and distraction to prevail in court.”

But for the normal Navient buyer hoping for instant relief, they may well be remaining disappointed, reported Mike Pierce, govt director of the Student Borrower Security Centre, a customer advocacy team.

“Yesterday was a incredibly huge offer for selected individuals that have seriously been forgotten in our countrywide conversation in the university student debt crisis,” Pierce claimed. “This will be daily life-modifying for a specific team of individuals folks. But for every person else, the fight continues.”

Who qualifies for financial debt cancellation?

About 66,000 pupil debtors with Navient financial loans may see their money owed forgiven.

These are debtors with non-public loans — exclusively, subprime scholar loans taken out through Navient’s predecessor company, Sallie Mae, between 2002 and 2014. (Navient was formed in 2014 following Sallie Mae break up into two small business entities.)

In addition, those debtors must have had additional than seven consecutive months of delinquent payments prior to June 30, 2021.

College student borrowers who don’t have subprime financial loans might nonetheless qualify if their non-public financial loans had been manufactured between 2002 and 2014 and they attended a for-profit college that was later the subject of point out or federal regulation enforcement actions. All those educational institutions consist of Corinthian Colleges, DeVry College and ITT Educational Companies. A full checklist can be uncovered on a web page for the arrangement.

Who qualifies for a restitution payment?

About 350,000 federal university student financial loan debtors whom Navient positioned into a extended-phrase forbearance system would be suitable for a payment — about $260 for every borrower.

Condition attorneys general say those forbearance preparations experienced pushed university student borrowers further more into credit card debt simply because even though all those debtors had been able to pause or lower their payments briefly, their loans still continued to accrue fascination.

Specific situations use to get the restitution, these kinds of as obtaining at the very least 1 federal personal loan that was suitable for profits-pushed repayment and the borrower not possessing enrolled in income-pushed compensation prior to the forbearance interval.​

Debtors whose federal financial loans had been lately transferred to another servicer, Aidvantage, may possibly even now be suitable for restitution.

Which states were involved in the settlement?

Qualifying residents of the following states will be protected beneath the restitution settlement: Arizona, California, Colorado, Connecticut, Delaware, Florida, Ga, Hawaii, Illinois, Indiana, Iowa, Kentucky, Louisiana, Maine, Maryland, Massachusetts, Minnesota, Missouri, Nebraska, Nevada, New Jersey, New Mexico, New York, North Carolina, Ohio, Oregon, Pennsylvania, Tennessee, Virginia, Washington and Wisconsin. Washington, D.C., is also provided.

In addition, borrowers who qualify for financial debt cancellation will have to also reside in a single of the aforementioned states or in the following states: Arkansas, Kansas, Michigan, Rhode Island, South Carolina, Vermont and West Virginia.

What steps should really borrowers consider?

If a borrower qualifies for either credit card debt cancellation or a restitution payment, they will be contacted instantly.

A settlement administrator is expected to send people debtors a postcard in the mail this spring, and checks would go out in mid-2022.

For these borrowers who are established to get their private loans forgiven, they would be contacted in crafting by July 2022. 

The settlement amongst Navient and the states is nonetheless awaiting closing court docket approval.

In the meantime, ought to borrowers hold paying out off their financial loans?

Pierce suggests borrowers with personal loans to continue to keep paying or, if they can, talk to an attorney about their situation.

All those with federal pupils loans are nevertheless benefiting from a moratorium on this sort of payments by May possibly 1, soon after the Biden administration prolonged the pause very last thirty day period.

But there is long lasting good news for people whose debt is forgiven, together with underneath this most up-to-date settlement arrangement with Navient, Pierce claimed.

University student financial loan forgiveness is tax-absolutely free as component of the White House’s coronavirus stimulus package signed into law very last 12 months. Previously, any student financial loan financial debt canceled by the federal government was taxable.

Navient lawsuit settlement: 400,000-plus student loan borrows will get debt relief

Navient lawsuit settlement: 400,000-plus student loan borrows will get debt relief

The offer will settle litigation brought by quite a few state lawyers typical that claimed that Navient, a single of the most significant college student loan servicing corporations in the US, engaged in unfair techniques and manufactured predatory financial loans to pupils who have been unlikely to be able to pay them again.

About 350,000 federal pupil mortgage borrowers whom Navient put in long-expression forbearance — which authorized them to briefly quit generating payments — will acquire about $260 each, totaling $95 million in restitution.

What Biden is missing on for-profit college debt

In addition, Navient have to totally cancel the remaining balances of non-public financial loans borrowed by about 66,000 students, totaling $1.7 billion. These financial loans ended up mostly created involving 2002 and 2010.

“Navient knew that people today relied on their financial loans to make a greater lifetime for by themselves and for their little ones and instead of supporting them, they ran a multibillion dollar rip-off,” said Pennsylvania Lawyer Basic Josh Shapiro at a push convention Thursday. He co-led the litigation with attorneys typical from Washington, Illinois, Massachusetts, and California.

The point out attorneys standard claimed that Navient steered federal student financial loan borrowers into forbearance fairly than directing them to enroll in small-cost repayment strategies. As a result, some of these debtors fell deeper into personal debt as fascination accrued.

The lawsuit also alleges that Navient created personal financial loans to pupils attending for-earnings colleges and colleges with reduced graduation fees, even while it realized that a higher proportion of all those borrowers would be not able to repay the loans.

Navient denied violating any legislation in the settlement.

“The firm’s conclusion to solve these issues, which were being dependent on unfounded promises, enables us to keep away from the added burden, price, time and distraction to prevail in courtroom,” Navient’s main legal officer Mark Heleen explained in a assertion.

Till lately, Navient had a contract with the US Department of Training to services federal university student financial loans, but the business made the decision to conclude that contract late final year. Previously this month, it transferred its federal university student bank loan portfolio to a servicer identified as Aidvantage. Navient proceeds to originate private student loans.

The settlement addresses borrowers who are living in 38 states and Washington, DC. These who qualify for reduction underneath the settlement don’t want to consider any action and can hope to quickly get notification from Navient later this calendar year just after the court docket approves the agreement. Federal mortgage borrowers can update or create an on line account with the Department of Education to guarantee the agency has their present-day address.

Crushing student loan debt prompts parents to postpone their retirement

Crushing student loan debt prompts parents to postpone their retirement

Patricia Rizzo, 62, owes the federal authorities far more than $126,000. But what began as an expense in her daughter’s potential is affecting her have prospective customers.

A solitary mom, she earns around $40,000 a 12 months doing work at a drug rehabilitation clinic in New Jersey. She hopes to soon total a drug counseling certification that might raise her salary but acknowledges she’s far from zeroing out her harmony.

“What I’m on the lookout at suitable now is paying it more than 20 a long time, which will make me 82,” Rizzo explained.

She joins a increasing list of parents 60 and older who are delaying their retirement mainly because of Guardian Furthermore financial loans, a method that begun in the early 1980s to aid mother and father pay for their kid’s school educations. A recent NerdWallet study uncovered that for up to 26 per cent of mom and dad or guardians with Mother or father Plus, also recognized as Immediate Furthermore, bank loan credit card debt will not retire as to begin with planned. 

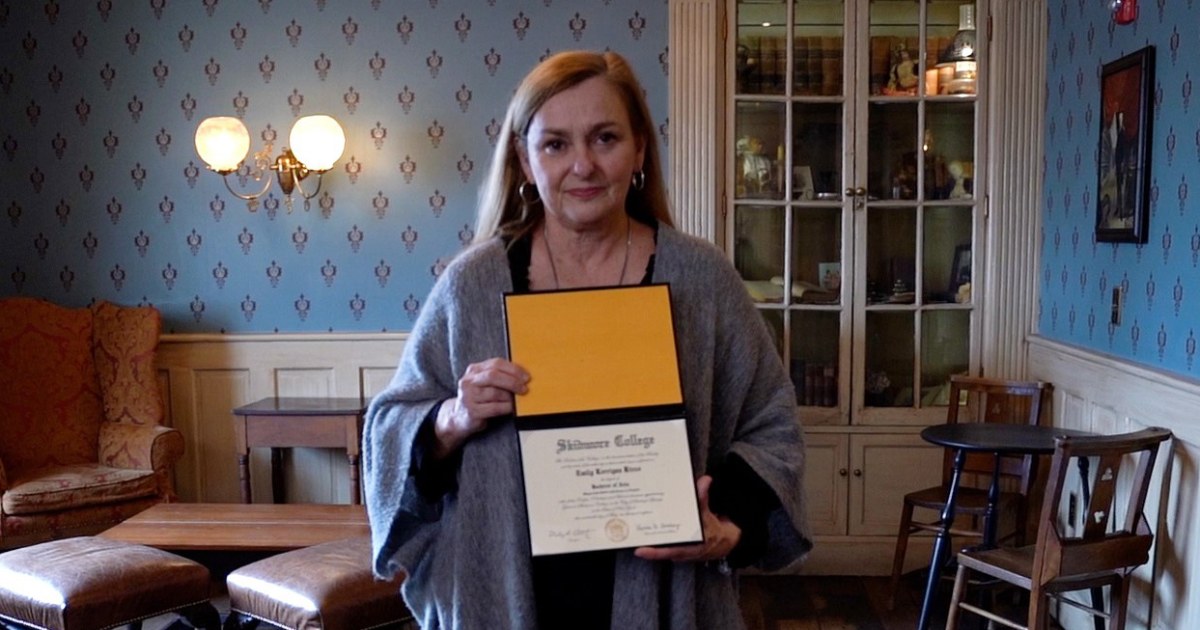
Rizzo claimed she took out 7 Mum or dad Plus loans to fork out for her daughter’s 8 semesters at Skidmore University in New York.

Patricia Rizzo with her daughter’s Skidmore College or university diploma.Information Now

She said delivering a quality training for her daughter was so significant that she moved to the affluent New Jersey city of Ridgewood so Emily, now 26, could go to higher-rated public faculties. Rizzo inspired her daughter to attend the greatest faculty she could, irrespective of charge.

“I felt like for school, I did not want to shortchange my kids,” claimed Rizzo, who also has a son, including that she attended workshops at her daughter’s high college to master about school money assist possibilities.

What commenced as a loan program for center-revenue family members has developed into a extensive-achieving application with couple limitations, mentioned Rachel Fishman, deputy director for exploration in education and learning plan at New The united states, a Washington think tank. 

“You can see parents quickly getting out tens of 1000’s of bucks in these loans for every year,” she stated. “And then at the close of an undergraduate vocation, they can very easily accumulate more than $100,000.”

Fishman reported she’s observing far more reduce- and center-income people get in in excess of their heads.

“What’s extremely unique is this is not a co-signed bank loan,” she explained. “This is a financial loan a father or mother can take out in their have identify the student has no obligation to pay this bank loan back.”

To qualify for a Mum or dad Additionally mortgage, borrowers have to go through a credit history check, but primarily there’s no cap on the amount of money they can borrow, and moms and dads or guardians can get out as a great deal as the complete price of attendance.  

“Just mainly because a mother or father is awarded the mortgage, doesn’t suggest that the federal federal government thinks that guardian can actually pay back the loan back,” Fishman mentioned. “All they’ve performed is see whether or not the mother or father has a damaging credit rating record.”   

The fascination rates for Father or mother As well as financial loans are set dependent on the calendar year they ended up taken out, but quite a few families borrow much more than they can afford to pay for, she stated.

From 2005 to 2015, the common total of scholar mortgage debt for debtors 60 and more mature doubled, in accordance to the Consumer Economic Safety Bureau. Most of that debt is for their small children or grandchildren.

In Rizzo’s situation, the curiosity on her 7 loans differs from 6 to 7 per cent. She has not started creating payments because of increasing cost of dwelling costs, other money owed and the pandemic. She reported she intends to pay but hopes some aid will materialize.

Just after several extensions, the Biden administration paused scholar financial loan payments right up until May well 1 which, in component, freezes desire charges at zero.

Traditionally, endeavours to decrease the scale of eligibility for Dad or mum In addition loans have been fulfilled with swift pushback.  

Some critics and gurus say doing away with the plan particularly or student credit card debt normally would price the governing administration billions or even trillions of dollars. An Obama administration hard work to reduce the number of qualified Father or mother Moreover debtors sparked backlash from traditionally Black schools and universities, which claimed it affected enrollment. The shift prompted threats of lawsuits and significantly criticism. 

Emily, Patricia Rizzo’s daughter. Courtesy Patricia Rizzo

The effect of Father or mother Additionally loans on debtors of different backgrounds is tough to quantify, gurus mentioned, but the truth is it leaves lots of moms and dads and guardians in a large amount of financial debt. Though officers discussion whether or not to terminate college student debt both partially or fully, a financial loan can finish without reimbursement in quite a few methods.

They involve a discharge, which commonly occurs when a borrower dies, is completely disabled or the college the place the loans were being gained closes and forgiveness or cancellation, which are usually linked to general public assistance work opportunities or trainer loan forgiveness applications.

Due to the fact university student mortgage cancellation remains up in the air, Fishman encourages all those in personal debt to prepare, plan and reach out for assist, which include exploring the likelihood of bank loan consolidation.

“Always be very careful when it comes to refinancing any federal financial loan,” she explained. “A scholar is unable to refinance a Parent Moreover personal loan into a federal consolidation personal loan, so they would have to transform to the non-public marketplace for that type of consolidation.”

Rizzo said her daughter, a 2018 graduate who is now a reporter, is keen to assist fork out off the financial loans, but the mom isn’t as well worried about it.

“I can’t say I regret it for the reason that my daughter has accomplished so a lot appropriate now,’ she stated. “I necessarily mean she just received the greatest instruction.”

Biden’s student loan relief efforts haven’t changed a DeVos decision on for-profit colleges so far

Biden’s student loan relief efforts haven’t changed a DeVos decision on for-profit colleges so far

The rule was repealed by previous Schooling Secretary Betsy DeVos, who was afterwards sued over the conclusion. The Biden administration asked a decide late final yr to maintain the repeal in put even though it undertakes a monthslong course of action to create a new edition.

It really is a go that has surprised some scholar financial loan borrower advocates.

“If the Biden administration is major about guarding college students, it tends to make no feeling that they’re continuing to fight them in court,” claimed Aaron Ament, president of the National Pupil Authorized Protection Network, which filed the lawsuit in 2020.

“They can aid right now, all they have to do is halt defending Betsy DeVos’ unlawful decisions,” included Ament, who formerly served as an lawyer for the US Section of Training under the Obama administration.

For-revenue schools have helped fuel America’s college student debt difficulties. About 11{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of for-gain school students default, when compared with 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of pupils who attend general public faculties and about 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} who go to personal, nonprofit schools, in accordance to the newest facts from the Division of Schooling.

Several for-profits’ programs don’t direct to increased-paying out positions, leaving some students struggling to pay out off their credit card debt. The Section of Instruction has identified that several for-profit faculties defrauded their students and, as a consequence, it has forgiven the financial debt of hundreds of those debtors — a transfer that delivers debt reduction but also expenses taxpayers income.

Known as “gainful work,” the rule aimed to identify low-doing for-financial gain faculties and certificate systems at nonprofit colleges — indicating people whose graduates had substantial college student loan payments relative to their profits. Those people that fell quick of the government’s benchmarks would reduce obtain to federal funding. As a outcome, their learners would be blocked from borrowing federal college student loans and obtaining other forms of federal financial assist.

DeVos repealed the rule in 2019, arguing that it failed to account for factors that could influence a graduate’s earnings other than software good quality. She also criticized the rule for keeping for-gain colleges to a larger standard than nonprofit institutions.

Biden administration needs to rewrite the rule

The Division of Instruction intends to put a new rule in put that sets standards all over gainful employment. In purchase to do so, it truly is beginning a formal rule-making approach as soon as up coming week. The procedure, acknowledged as negotiated rule-building, features a collection of meetings followed by a public remark period of time that generally will take months.

“We are fully commited to restoring a strong gainful employment rule as quickly as feasible,” mentioned Education and learning Division Under Secretary James Kvaal in a statement sent to CNN.

“While we respect and value outside opinions on the finest route to that objective, our judgment is that focusing on the regulatory procedure will develop the ideal, most long lasting rule to guard students,” added Kvaal, who performed a significant purpose in crafting the first gainful employment rule.

But although the division goes by way of the rule-making system, the scholar protections furnished by the prior gainful employment regulation will not be in area, permitting persons to potentially enroll in risky faculty packages in the meantime.

In a courtroom document, Kvaal argued that, from an operations standpoint, it would very likely consider at the very least a calendar year, if not more time, to completely put into practice the previous rule. It is unclear if that could take place ahead of a new rule requires effect, he wrote.

If the former rule is reinstated, the section anticipates it would have to combat new lawsuits, in accordance to court docket documents.

Focusing on for-revenue faculties

Other steps taken by the Biden administration have recommended it intends to target the for-revenue college sector. The Federal Trade Fee, for instance, despatched 70 for-income colleges a letter in Oct, placing them on notice that the agency ideas to crack down on any wrong promises they make about their graduates’ career and earnings potential clients.
Plus, a Biden-backed system to develop Pell grants — a form of federal assist awarded to learners with excellent economical require — would make for-gain college pupils ineligible for the money. The approach was incorporated in the Democrats’ Create Back again Improved legislation, which has stalled in the Senate.

“I do assume it can be a precedence for them, but I assume they could do far more. It was a minimal stunning that they didn’t put gainful work back into result,” mentioned Carolyn Rapidly, an attorney and a senior fellow at The Century Basis, in which she operates on increased education coverage.

“The timeline for obtaining a new rule in position is rather prolonged. It seems to make sense to have the old rule in area in the meantime to make confident students usually are not enrolling in courses that aren’t heading to meet up with the standards,” she stated.

How the rule was intended to function

The gainful employment rule essential for-income schools and vocation certificate programs at nonprofit schools to article personal debt-to-earnings ratios, proving that their pupils could locate superior-paying careers on graduating. If the regular ratio did not meet up with governing administration requirements for two out of three consecutive years, the school’s federal funding would be revoked.

Rankings had been published in 2017, discovering additional than 800 programs that unsuccessful to meet up with the department’s expectations. But DeVos revoked the rule ahead of any of the institutions shed federal funding.

The rule still had some influence by disclosing packages whose pupils are saddled with financial debt they won’t be able to pay for. A graduate theater program at Harvard University, for case in point, froze enrollment soon after acquiring a failing quality in the government’s report.

Canceling personal debt vs. tackling faculty affordability

To day, the Biden administration has canceled about $2.8 billion in scholar loan credit card debt owed by students who ended up defrauded by their for-income schools, in accordance to the Section of Education and learning. It did so by reversing a DeVos plan that confined the total of reduction because of to defrauded borrowers and by analyzing that 115,000 former pupils of ITT Complex Institute, a now-defunct for-financial gain, had been eligible for automated forgiveness.

But people steps give aid only just after a person has been defrauded. The gainful employment rule attempts to protect against the trouble from occurring in the initially area, defending college students from using out financial debt that they will not be ready to find the money for to fork out back.

“In its place of cleansing up challenges on the back finish, they could clean up matters on the entrance conclusion, way too, and save a good deal of individuals from heartache,” Quickly mentioned.