PORTLAND, Ore. (KOIN) — On Sept. 13, a previous West Linn dentist pleaded guilty to wire fraud and aggravated identity theft in federal court docket for thieving almost $11.5 million in cash allocated for COVID-19 reduction.
Salwan Adjaj submitted many fraudulent personal loan applications to the Small Small business Administration from September 2020 till at the very least Could 2021, according to federal prosecutors, and stole cash from the Economic Effects Disaster Personal loan and Paycheck Defense System that had been approved by the Coronavirus Assist, Aid, and Economic Protection Act that sought to help tiny corporations impacted by the pandemic.
Adjaj faked certain facts to pose as numerous firms in need of reduction, such as names, employer identification figures, business start out dates and places, prosecutors reported. Whilst most of these apps were despatched beneath other people’s names, he often recorded his personalized address as the business’s mailing tackle, authorities reported. Each software was allegedly submitted from the IP handle at Adjaj’s spot of operate.
SBA turned down most of his EIDL applications, so Adjaj allegedly pivoted his focus to the PPP program and the Restaurant Revitalization Fund which offers financial relief to companies in the meals and drink marketplace. In May well 2021, he submitted purposes on behalf of fictitious eating places that he claimed were being located in Florida, prosecutors stated.
Adjaj was formally billed by a felony grievance with wire fraud and aggravated identification theft on Oct. 14, 2021. Two months later on on Dec. 14, he was arrested due to an alleged pretrial launch violation. The up coming working day, he received an buy stating that he would be detained pending further court proceedings.
In addition, Adjaj pleaded responsible to illegally distributing 1000’s of managed substances in a independent prison situation on July 13. The former dentist confessed to making use of his occupation to obtain the substances, prosecutors reported.
He could be sentenced a maximum of 22 decades in prison, receive a $250,000 great and three years’ supervised release for his COVID-19 relief fraud situation. For his drug-similar offenses, Adjaj faces a highest sentence of 10 several years in prison, a $500,000 fine and 3 a long time of supervised launch.
U.S. District Courtroom Choose Michael W. Mosman will sentence Adjaj for equally federal cases on Dec. 6. As mentioned in his plea agreement, Adjaj will compensate for his crimes from the SBA and target loan companies with no less than $10.5 million.
China has doled out tens of billions of bucks in secretive “emergency loans” to nations around the world at possibility of economic crises in latest years, turning Beijing into a formidable competitor of the western-led IMF.
The bailouts symbolize a pivot from the big infrastructure loans China has extended more than nearly a ten years as component of its $838bn Belt and Street Initiative, a programme that noticed it eclipse the Entire world Bank as the world’s greatest financer of general public performs.
A few of the most significant recipients of China’s rescue lending have been Pakistan, Sri Lanka and Argentina, which jointly have obtained as much as $32.83bn considering that 2017, according to facts compiled by AidData, a exploration lab at William & Mary, a college in the US.
Other nations obtaining rescue lending from Chinese condition institutions included Kenya, Venezuela, Ecuador, Angola, Laos, Suriname, Belarus, Egypt, Mongolia and Ukraine, in accordance to AidData, which did not deliver particulars for these international locations.
These credit score is aimed at enabling nations to continue to keep up payments on overseas personal debt and to go on obtaining imports, warding off balance of payments (BoP) distress that can produce into full-blown storms this kind of as the 1997 Asian disaster and the Latin American disaster of the 1980s. The IMF’s austere prescriptions in the aftermath of the Asian crisis had been deeply unpopular, reinforcing a backlash against it that persists to this working day.
Compared with the IMF, which announces the particulars of its credit rating traces, credit card debt reduction and restructuring programmes to debtor international locations, China operates largely in secret. China’s monetary institutions publish scant information of the credit history it problems and Beijing does not predicate its lending on credit card debt restructuring or economic reforms in receiver nations, analysts reported. In most cases, the goal of China’s unexpected emergency lending is to prevent defaults on infrastructure loans extended under the Belt and Street Initiative, analysts said.
“Beijing has tried to keep these nations afloat by offering crisis bank loan soon after crisis financial loan with out asking its borrowers to restore economic coverage discipline or pursue personal debt reduction by way of a co-ordinated restructuring method with all significant collectors,” mentioned Bradley Parks, govt director of AidData.
The AidData investigate lab maintains the world’s most extensive database on China’s global funding pursuits mainly by compiling info from nations that get Chinese financial loans. The info established captures countless numbers of loans from more than 300 Chinese federal government institutions and point out-owned entities across 165 small- and middle-earnings countries.
Parks extra that China’s method typically “postpones the day of reckoning”.
“When Beijing acts as an alternative loan provider of final resort and bails out a distressed sovereign without having necessitating financial plan discipline or pursuing a co-ordinated debt rescheduling with big collectors, it correctly kicks the can down the street and leaves it to other people to fix the underlying solvency issue,” Parks claimed.
A research of the particular person loans provided by Chinese economic establishments given that 2017 to Pakistan, a crucial participant in the Belt and Highway Initiative, reveals a drip-feed of help in the type of loans from state-owned financial institutions and Safe and sound, the agency that controls Beijing’s $3tn stash of international exchange reserves.
The phrases on these loans are considerably from concessionary, frequently building in a margin of about 3 for each cent earlier mentioned benchmark funding expenses. In addition to these loans, the People’s Bank of China, the central bank, has a forex swap arrangement with its Pakistan counterpart that will allow Islamabad to draw down funds when it needs them, the AidData data exhibit. The PBoC has declined to remark.
Commentators claimed China’s rescue lending risked prolonging and exacerbating personal debt distress and the crises that typically abide by in debtor nations. “I see these as a big impediment to disaster resolution,” said Gabriel Sterne, head of EM macro at Oxford Economics and a former senior economist at the IMF.
As Sri Lanka’s present-day economic meltdown demonstrates, Beijing’s guidance is occasionally insufficient, analysts claimed. “The suspicion is that countries seek out the mortgage to keep away from going to the IMF, which requires distressing reform,” Sterne included. “There may possibly be circumstances in which the gamble for redemption functions, but commonly — as in the Sri Lankan scenario — it just tends to make the adjustment far more agonizing when it basically takes place.”
Sean Cairncross, previous chief executive of the Millennium Obstacle Corporation, a US federal government overseas support agency that offers grant funding on issue of democratic governance and financial transparency, said China’s financial loans had been furnished in pursuit of extensive-time period aims in competition with rival powers.
“This isn’t about any unique loan or country . . . They want to have the ear of governments where uncooked components are situated, or substantial markets, or strategic ports, or the place there is obtain to shipping and delivery lanes,” he mentioned. “It is a way to slender the strategic selections for the US and for the west, in phrases of access and impact globally.”
Finding online installment loans can be incredibly challenging for Americans without picture-perfect credit histories and could also be quite frustrating. This is especially the case when you need cash urgently. Mentioned below are 5 installment loan providers to help you find the one best suited to your financial needs.
3. Big Buck Loans – Installment loans for unemployed individuals can be explored here
4. Heart Paydays – suitable for online installment loans with instant decision
5.Green Dollar Loans – For same day installment loans
1.Viva Payday Loans – Suitable for all kinds of installment loans online
ET Spotlight
The application process for online installment loans on the Viva Payday Loans webpage is simple to complete, taking most applicants no more than a few minutes. The platform boasts an impressive $100 to $5,000 loan range and offers applicants 3 to 24 months to repay their online installment loans. The interest rates on Viva Payday Loans are quite reasonable, starting as low as 5.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.
Eligibility requirements
Earn $1,000+ per month
Be of legal age (18+)
Have a good income-to-expense ratio
Pros
The entire application process can be done online
Applicants with bad credit accepted
Customizable loan terms
Cons
Interest can be quite high.
2.Low Credit Finance – Most suited for installment loans for bad credit
ET Spotlight
Bad credit holders could perhaps opt for Low Credit Finance. While Low Credit Finance does accept applicants with poor credit histories, there is no guarantee for approval. Applicants can apply for installment loans for bad credit of up to $5,000 and choose a repayment period between 3 and 24 months.
Eligibility requirements
Monthly income of $1,000+
Minimum of 18 years old
Pass an affordability assessment
Pros
Loans up to $5,000
Repayment period up to 24 months
Applicants with any credit history welcome
Cons
Interest rates can be as high as 35.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}
3.Big Buck Loans – Online installment loans for unemployed individuals
ET Spotlight
Big Buck Loans makes it possible for individuals who are self-employed, unemployed, or receiving benefits to apply for online installment loans with instant approval with the same amount of ease as any other applicant. Through Big Buck Loans, applicants can borrow between $100 and $5,000 without being traditionally employed.
Eligibility requirements
Earn $1,000 per month minimum
18+ years old
Active US bank account
Pros
Instantaneous approvals
Easy to apply for
Options for everyone
Cons
Interest rates can reach up to 35.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}
4.Heart Paydays – Suitable for online installment loans with instant approvals
ET Spotlight
Heart Paydays is a good fit for applicants who need cash now. The platform offers applicants personal installment loans between $100 and $5,000, with a repayment period of up to 24 months. Interest rates on the site range between 5.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and 35,99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, and once an applicant submits their application, they will get an answer in less than two minutes.
Eligibility requirements
$250+ weekly income
Must be over 18
US bank account and mobile number
Pros
Same-day payouts
Applicants with poor FICO scores accepted
Loans can be adjusted to suit your needs
Cons
5.Green Dollar Loans – For quick same-day installment loans
ET Spotlight
With Green Dollar Loans, there’s no time to worry about whether or not your application will be successful, as you’ll have a decision within two minutes. Applicants can borrow up to $5,000 per guaranteed installment loan for bad credit and repay it over two years. If an applicant is successful, they’ll receive their money within 24 hours.
Eligibility requirements
Over 18 years old
Earn $1,000 or more each month
US citizen or permanent resident
Pros
Quick online application process
Payouts within 24 hours
Options for bad credit borrowers
Cons
Interest can reach 35,99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}
What are installment loans and how do they work?
Personal installment loans are small loans, typically repaid over a short period, usually 3 to 24 months. The loan model for guaranteed installment loans for bad credit is quite simple, with applicants applying online in five minutes or less and then repaying the loan with interest fees attached.
How to apply for installment loans in quick steps?
You need to follow these four steps to apply for guaranteed decision on installment loans for bad credit:
Step 1: Choose your loan amount
You can choose to borrow $100 and $5,000 and select a repayment period of 3 to 24 months.
Step 2: Complete the application form
You will be prompted to add your personal information to the application form to complete it.
Step 3: Wait for a decision
After submitting your application, you will know in two minutes or less whether or not a lender can assist you.
Step 4: Get your loan
You will be sent a contract by the lender to sign and send back to receive your loan. You will be paid within 24 hours.
Installment loans features and factors to consider
Personal installment loans interest rates
An interest rate of 5.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 35.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} will be added to your guaranteed installment loans for bad credit and will be included as part of your monthly installment.
Loan amounts and repayment terms of personal installment loans
Applicants can borrow between $100 and $5,000 with each personal installment loan and can select a repayment period of 3 to 24 months to suit their needs.
The reputation of personal installment loans lenders
The loan-finders mentioned above work with well-reputed, trustworthy, and reliable personal installment loans lenders.
How to choose the top installment loans providers?
All the providers should offer the following:
Interest rates no more than 35.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}
Easy application that can be completed entirely online
Payouts within 24 hours or less
Customizable loan terms
Conclusion
Viva Payday Loans is a top pick for guaranteed installment loans for bad credit direct lenders providers, as they offer their service free of charge and allow applicants to choose their own loan amounts and repayment periods.
FAQ’s
What is the cost of getting guaranteed installment loans for bad credit from direct lenders?
Applying for guaranteed installment loans for bad credit from direct lenders through loan-finders such as Viva Payday Loans is completely free of charge, and you won’t encounter any unexpected hidden fees along the way.
What will happen if I don’t pay my only guaranteed installment loans for bad credit or no credit check on time?
If you default on your installments or make late payments for only guaranteed installment loans for bad credit or no credit check, you can expect a few negative points to be added to your credit score. You may also be charged a penalty or late fee by the lender.
How long do I need to wait between no credit check installment loans?
You will need to wait a minimum of 24 hours after paying off your first no credit check installment loans before you can apply for a second one.
Disclaimer – The above content is non-editorial, and TIL hereby disclaims any and all warranties, expressed or implied, relating to it, and does not guarantee, vouch for or necessarily endorse any of the content. The loan websites mentioned are loan-matching services, not direct lenders, therefore, do not have direct involvement in the acceptance of your loan request. Requesting a loan with the websites does not guarantee any acceptance of a loan. This article does not provide financial advice. Please seek help from a financial advisor if you need financial assistance. Loans available to U.S residents only.
(RNS) — I test to steer clear of mentioning I’m a pastor when I satisfy new individuals mainly because the conversations straight away get unusual. I knowledgeable 1 these types of awkward turn whilst on trip with my loved ones and sharing a pool with a woman in her 70s executing h2o aerobics. Right after learning about my career she started lamenting the absence of her grandchildren in church ahead of pivoting to her hope of a political applicant reclaiming America for God.
The want for our more youthful family members customers to share our religion convictions and beliefs is typical. Sadly, the drive for our convictions and beliefs to control modern society is also predictably standard.
In Luke’s account of the announcement and beginning of John the Baptist, the angel Gabriel told John’s father, Zechariah, the information currently being supplied as a result of John would “turn the hearts of the fathers towards their youngsters.” When John commenced preaching and getting ready people today to behold Jesus he informed individuals with two coats to give to the types who had none and to do the identical with their food. He referred to this function as a way of “producing fruit in preserving with repentance.” The Very first Nations Version of the New Testament states, “When the persons read these phrases, they began to have hope.”
I simply cannot say I was shocked when I read the backlash toward the news of very last week’s announcement of the forgiveness of university student personal loan credit card debt.
I was raised in a custom that praised the virtue of neighbors caring for neighbors — and thought they could do so in approaches the federal federal government couldn’t maybe replicate. It was in that spirit that the church wherever I provide introduced an initiative in 2020 called the Equitable Therapeutic Reparations Initiative. The aim of the function was to pay out off student personal loan credit card debt for Black therapists in buy to chip away at disparities that exist in mental health obtain and care as perfectly as an increasing prosperity hole amongst Black and white People in america.
I had lately heard Jemar Tisby lecture on his e book “The Shade of Compromise: The Truth About the American Church’s Complicity in Racism.” Through the lecture he elaborated on some of the realities that challenge Black illustration and accessibility to mental well being treatment and the want for mend in techniques perpetuating all those problems. He also advised fiscal reparations as a way for dominant society American churches to repent for the inequities their establishments served generate and maintain.
Putting these concepts with each other, we designed our initiative and in excess of the previous two a long time extra than 100 people today from 12 states (and a single good Canadian) have specified a lot more than $84,000 to the payment of personal loan debt for Black therapists. Our small, small price range church has also fully commited to giving month to month to the restore of these damaged techniques and has offered $18,000 to the initiative —putting the total at just in excess of $100,000. One particular therapist’s personal loan personal debt was fully paid and we’re on the way to shelling out off another’s. We are also nearing the start of a Black-led foundation that will continue on and increase this do the job.
Just one unpredicted fruit of this hard work was that more youthful folks — quite a few who experienced remaining the church or Christianity entirely — ended up loaded with hope at the believed of a church moving in fiscal repentance towards a more equitable culture. Hearts of grandparents, fathers and mothers were being waking up to the tricky realities of a younger generation of students. Numerous persons in their 20s and 30s told me it was the 1st time they felt good about giving money to a church. Fruit grew for the reason that of repentance.
If your explanation for opposition to past week’s debt reduction method is due to the fact it is coming from the federal governing administration, I’d like to provide this method as a way for you to enter into the get the job done of proclaiming a kingdom the place there is no debt and everyone is well prepared to flourish. If you feel the most effective way for this to transpire is for neighbors to care for neighbors, why not have your church start shelling out off financial loan debt for neighbors who have been crushed by predatory lending and unsustainable expenditures of continuing schooling?
I never know if my young children will believe that what I think about Jesus, but I’m convinced that if they do it will have more to do with institutional repentance than institutional certainty. I imagine that was the key component John the Baptist was supplying to individuals who collected all around him and began to have hope.
The woman in the pool with me that day certainly needed her young children and grandchildren to experience a God who knew them and cherished them. She ached for them to need that adore, but the programs she had invested time and cash into weren’t persuasive them toward her eyesight for their world.
Jesus spoke these words when rebuking people who thought of on their own small children of the mild who sought security and ease and comfort in their cash and possessions: “The children of this planet are more shrewd in dealing with their have technology than are the small children of the light-weight.” Previous week, the United States governing administration offered a additional hopeful gospel proclamation to these beneath the body weight of financial debt than has been supplied by a great deal of what is called the church.
For as long as I can remember I have listened to older Christians connect with for revival. For them, revival intended all those who don’t imagine coming into agreement with us and our establishments. I have nevertheless to see this sort of an celebration consider place, but I speculate … what if all the dollars aimed at territorial enlargement and church planting was aimed as a substitute at financial debt reduction and racial justice?
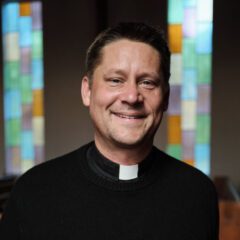
The Rev. Danny Bryant. Courtesy photograph
Could this sort of an act fill persons with hope and put together hearts for the just reconciliation provided in the physique of Jesus?
(Danny Bryant serves as the priest of St. Mary of Bethany Parish in Nashville, Tennessee. The sights expressed in this commentary do not essentially mirror those of Faith News Services.)
The White Residence on Thursday identified as out Rep. Marjorie Taylor Greene’s (R-Ga.) criticism of President Biden’s prepare to forgive some student financial loans, noting that the congresswoman had Paycheck Safety System loans forgiven.
The Biden administration’s official Twitter account shared a video of Greene knocking the just-announced financial debt cancellation in a Newsmax job interview as “completely unfair.”
“Congresswoman Marjorie Taylor Greene had $183,504 in PPP loans forgiven,” the White Residence wrote, referring to the Paycheck Safety Application (PPP), a lifeline extended to help compact organizations remain afloat during the COVID-19 pandemic.
The Hill has attained out to Greene’s business office for comment.
The Biden administration is forgiving up to $10,000 in federal university student financial loan personal debt for Americans earning considerably less than $125,000 for each 12 months, and up to $20,000 for Pell Grant recipients earning less than $125,000 per 12 months.
Biden also declared however yet another extension of a freeze on federal university student personal loan repayments and curiosity accrual, just ahead of the Aug. 31 expiration date established when the deadline was very last pushed again.
“For our federal government just to say, you know, ‘Ok, very well your debt is fully forgiven,’ … it’s entirely unfair,” Greene stated in the Newsmax interview, which aired Wednesday.
Taxpayers “should not have to shell out off the fantastic significant pupil personal loan debt for some higher education college student that piled up substantial debt likely to some Ivy league faculty,” Greene argued. “That’s not honest.”
Biden responded on Wednesday to reporters’ issues about no matter whether the personal debt forgiveness is unfair to individuals who have previously paid off or selected not to get out loans, taking a swing at tax cuts on the abundant.
“Is it honest to men and women who, in truth, do not very own multibillion-greenback businesses, if they see a single of these men getting all the tax cuts? Is that honest? What do you think?” Biden explained soon after his remarks saying the system.
The credit card debt aid move has garnered praise from Democrats, when Republicans have criticized the economics.
The White Household Twitter account has developed a thread down below its reaction to Greene’s criticism, with comparable responses to other Congressional critics of the student mortgage debt announcement. The congressmen whose PPP mortgage amounts were being discovered involve Reps. Vern Buchanan (R-Fla.), Markwayne Mullin (R-Okla.), Kevin Hern (R-Okla.), Mike Kelly (R-Pa.) and Matt Gaetz (R-Fla.).
Cars and buses in Sydney, Australia, on Monday, Might 25, 2020. Authorities in the country are looking to set up a Countrywide Electric Auto Strategy.
Brendon Thorne | Bloomberg | Getty Visuals
An Australian financial institution programs to cease giving financial loans for new diesel and gasoline cars as the region tries to really encourage the use of electric motor vehicles and catch up with other created nations.
In a assertion Friday, Financial institution Australia explained it would scrap loans for new fossil gasoline vehicles from 2025. Sasha Courville, its main impression officer, reported that day had been picked “because the change to electric automobiles desires to take place speedily.”
The bank, Courville added, considered this could take place “with the correct supporting guidelines in put to deliver a increased vary of more affordable electrical vehicles to Australia.”
Though there will be no far more loans for new combustion engine cars — including hybrids — from 2025, Financial institution Australia will continue on to present them for made use of types.
“We will keep on to provide financial loans for 2nd-hand fossil gas vehicles right until there is a practical and thriving market for electric motor vehicles,” it explained.
On that front, Friday also noticed the Australian federal government provide data about designs to established up a National Electric Auto Method for the state, with a discussion paper on the issue owing to be launched for consultation.
Read a lot more about electrical vehicles from CNBC Professional
In an announcement, the federal government explained Australia was “substantially powering the pack when it arrives to electrical vehicles.”
It added that, at just 2{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, the country’s uptake of new lower-emission vehicles was “virtually 5 times reduced than the international average — nationwide leadership is essential to make sure we don’t proceed to be left behind.”
“In this context, we feel that now is the time to have an orderly and practical discussion about whether or not car gasoline efficiency benchmarks could assist increase the source of electric motor vehicles into the Australian market, to deal with the expense-of-dwelling impacts of inefficient cars, and to reduce emissions from the transport sector.”
Client-owned Lender Australia traces its roots back again to 1957. According to its Statutory Fiscal Report for 2021, it claimed whole property experienced developed to 8.5 billion Australian bucks ($5.9 billion), with revenue immediately after tax coming in at 40.7 million Australian pounds.
It is not exceptional in its tactic toward vehicles powered utilizing fossil fuels. In 2020, Denmark’s Merkur Cooperative Bank claimed it would halt financing for new diesel and gasoline vehicles.
All of this arrives as big European economies are laying out ideas to transfer away from highway-centered autos that use diesel and gasoline.
The U.K. needs to cease the sale of new diesel and gasoline cars and trucks and vans by 2030. It will demand, from 2035, all new vehicles and vans to have zero-tailpipe emissions. The European Union — which the U.K. remaining on Jan. 31, 2020 — is pursuing related targets.
In accordance to the Intercontinental Energy Agency, electric automobile revenue hit 6.6 million in 2021. In the 1st quarter of 2022, EV revenue arrived to 2 million, a 75{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} maximize when compared to the initially a few months of 2021.