

Majority of Paycheck Protection Program loans have been forgiven, SBA data shows : NPR

Majority of Paycheck Protection Program loans have been forgiven, SBA data shows : NPR

An NPR analysis of data released Jan. 8 by the Small Business Administration shows the vast majority of Paycheck Protection Program loans have been forgiven, despite rampant fraud in the program.

Getty Images/Mark Harris for NPR


hide caption

toggle caption

Getty Images/Mark Harris for NPR


An NPR analysis of data released Jan. 8 by the Small Business Administration shows the vast majority of Paycheck Protection Program loans have been forgiven, despite rampant fraud in the program.

Getty Images/Mark Harris for NPR

When the Paycheck Protection Program launched during the pandemic shutdowns of spring 2020, it immediately became a chaotic free-for-all.

Called PPP for short, the program offered simple-to-get, potentially forgivable government loans to small businesses. Yet billions of dollars went to companies owned by wealthy celebrities, including Tom Brady and Khloe Kardashian, and companies that thrived during COVID, like many manufacturing and construction firms.

Government officials acknowledge that the program was rife with fraud and did not weed out undeserving applicants. But there was a way to remedy those early errors: Deny forgiveness. That could have thwarted scam artists and forced businesses that prospered to repay the money.

Yet nearly three years after the rollout of PPP, the vast majority of loans have been forgiven.

An NPR analysis of data released on Jan. 8 by the Small Business Administration found that 92{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the loans issued have been granted full or partial forgiveness. That includes loans to companies with mega-rich owners.

“The PPP program seems to have resulted in billions of dollars of fraudulent loans that have ultimately turned into grants,” said Samuel Kruger, an assistant professor of finance at the University of Texas at Austin who co-authored a paper estimating that $64 billion of the nearly $800 billion in loans issued show signs of fraud, such as suspiciously high payrolls and multiple businesses listed at the same home address.

The SBA disputes those findings, but its own inspector general has estimated that at least 70,000 loans are potentially fraudulent. An unknown additional number of loans went to companies that didn’t need PPP funding to survive the pandemic.

And although the Justice Department and other federal agencies have up to 10 years to prosecute pandemic fraud, the SBA’s inspector general has called that pursuit a “pay-and-chase” situation unlikely to recover much money.

NPR dissected the decision-making behind the Paycheck Protection Program that led to it being widely seen as a massive government giveaway. We spoke with numerous bankers, economists and government officials under former President Donald Trump and President Biden — since the program spanned both administrations — to find out why loan forgiveness was so lenient, especially after the highly publicized misuse of the program. Their responses involved copious finger-pointing, blame-shifting and buck-passing, making accountability elusive.

“There are very few things you could do to actually disqualify yourself”

During the COVID shutdowns in March 2020, an employee visits a closed Converse shoe store in Phoenix.

Matt York/AP


hide caption

toggle caption

Matt York/AP


During the COVID shutdowns in March 2020, an employee visits a closed Converse shoe store in Phoenix.

Matt York/AP

In the frenzied early days of COVID, as PPP was created in great haste to keep businesses from potentially collapsing, the loans were simple to get: Companies simply had to pledge that the economic threat of the pandemic made the funding necessary. But what it would take later to qualify for forgiveness was hazy.

“It was entirely unclear at the beginning,” said Eric Lichatin, a commercial loan officer at Centreville Bank in Rhode Island, which was inundated by calls from customers wanting PPP loans. “The SBA really rushed to get this program out there, which I think they should be commended for … but a lot of the details were very unclear to businesses and banks.”

As the program evolved, its rules became increasingly complicated, and even experts struggled to make sense of them. At one point, the SBA published a list of frequently asked questions on loan forgiveness that was 11 pages long. One consulting firm issued a client advisory with the headline “Fast and furious: The rules for the PPP … continue to emerge at a brisk pace, often updating previous guidance.”

That confusion posed a dilemma for many companies: Should they take the money if they might have to pay it back?

Some banking professionals, including Lichatin, advised their customers to accept the funding, put it in a separate account, and wait to use it until the rules became more clear.

“Then, if you don’t need the money, you can always just pay back the loan,” Lichatin explained. “But you do have it as a safety net available to you in case your business does take a massive hit.”

That recommendation proved wise, because Congress weakened PPP forgiveness criteria over time.

For example, the Paycheck Protection Program Flexibility Act, signed into law by President Trump in June 2020, gave some borrowers full forgiveness even if they didn’t fully restore their workforce: A company could offer a laid-off employee a job, and even if the employee turned it down, the company was still credited with maintaining worker head count.

President Donald Trump speaks to reporters while signing the Paycheck Protection Program Flexibility Act on June 5, 2020.

Mandel Ngan/AFP via Getty Images


hide caption

toggle caption

Mandel Ngan/AFP via Getty Images


President Donald Trump speaks to reporters while signing the Paycheck Protection Program Flexibility Act on June 5, 2020.

Mandel Ngan/AFP via Getty Images

Congress also expanded the ways the loan money could be spent. Originally, it was primarily meant to keep workers on the payroll. Eventually, businesses could use it for non-payroll costs, including property damage from looting and vandalism.

The rules became so lenient that anyone who received $150,000 or less — which accounts for more than 90{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of all borrowers — could get the full loan amount forgiven just by promising they had used the money correctly. No supporting documentation needed.

Some of these changes were called safe harbors, and “given the way the safe harbors are written, there are very few things you could do to actually disqualify yourself [from loan forgiveness] other than out-and-out fraud,” said David Autor, an economics professor at the Massachusetts Institute of Technology who has studied PPP.

In his view, the Paycheck Protection Program made almost any use of the loan money legal — and therefore eligible for forgiveness — and gave the SBA little ability to police bad actors.

“I’d like to make this as easy as possible”

Congress made PPP forgiveness rules increasingly lax because that’s what businesses lobbied their elected representatives for.

At a Senate Small Business Committee hearing in June 2020, Utah Sen. Mitt Romney said some of his constituents were “beginning to be concerned about whether or not they’re going to be qualified for forgiveness” and expressed hope “that we’re not sticklers, that we instead are looking to help people get forgiveness.”

At the same hearing, Louisiana Sen. John N. Kennedy told then-Treasury Secretary Steven Mnuchin that “small businesswomen and small businessmen think that the federal government is going to double-cross them on the forgiveness of these loans. You need to be mindful of that.”

In response, Mnuchin offered assurances that “the majority of this money is going to be forgiven in the next few months, and that’s our intent,” adding that “I’d like to make this as easy as possible.”

He made those remarks despite acknowledging that some well-resourced loan recipients, such as the Los Angeles Lakers, should not have applied for the funding, which they later returned.

The Los Angeles Lakers received PPP funding, but returned the money after being criticized for applying to the program.

Harry How/Getty Images


hide caption

toggle caption

Harry How/Getty Images
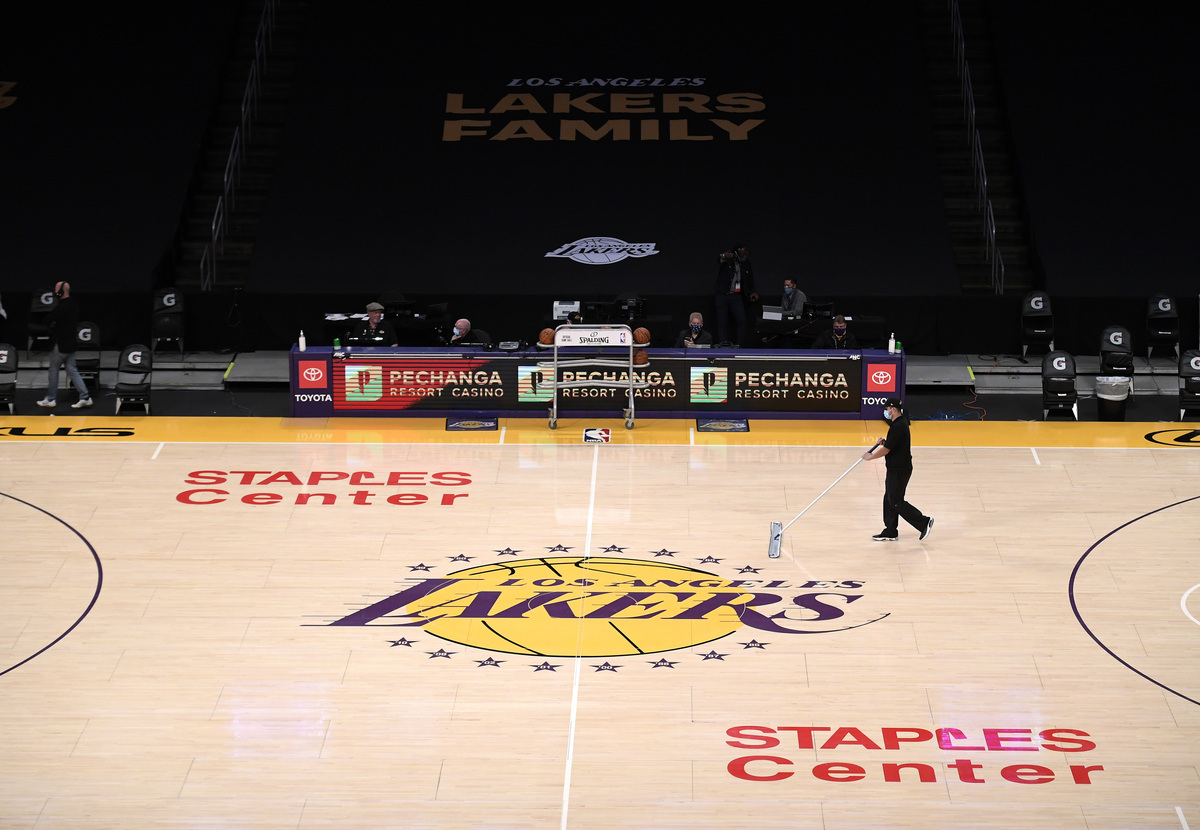

The Los Angeles Lakers received PPP funding, but returned the money after being criticized for applying to the program.

Harry How/Getty Images

“We thought that people would self-select appropriately,” Mnuchin told the committee, “and unfortunately there were a number of companies that were high-profile that took the loans.”

The following month, at a July 2020 House oversight hearing on government pandemic relief, Mnuchin again conceded that the Paycheck Protection Program was being abused, due in part to having been launched at breakneck speed.

“I’m concerned about fraud and want to make sure that the oversight committees are comfortable that this money was used appropriately,” Mnuchin added. “But we made the judgment it was more important to get it up-and-running quickly [and] that sending money to people four months later wasn’t going to help small businesses.”

At that hearing, Mnuchin pledged that government officials would be stricter with PPP loan forgiveness than with loan approvals.

“We are going to have a very robust process to review loans before loans are forgiven.” he said, noting that “in the forgiveness process, people will be required to provide much more data.”

“Eight hundred billion dollars. Here it is. Don’t pay it back.”

But the review process has been anything but robust.

The SBA has closely scrutinized just a tiny portion of PPP loans for fraud and forgiveness eligibility. The agency said it used computer models to review all 11.4 million loans, but that auditors have manually reviewed only about 215,000, or roughly 2{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the total, according to Patrick Kelley, associate administrator for the SBA’s Office of Capital Access.

Of these hands-on reviews, about 21,000 were denied forgiveness, or approximately 0.2{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of all loans, he said. Meanwhile, the University of Texas researchers who studied PPP fraud estimate that the enforcement rate of chasing scam artists is “well under 0.1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in all cases.”

So when Autor hears companies praise the Paycheck Protection Program, he’s skeptical.

“It’s not that the program did no good,” he said, “but how could they not love it? I mean, what could be better: $800 billion. Here it is. Don’t pay it back.”

Bert Talerman, president of Cape Cod Five Cents Savings Bank, which processed roughly 3,700 PPP loans totaling about $315 million, has a more forgiving view.

“In some cases, there are some folks who probably didn’t need the money,” he said. “At the same time, those were crazy times,” he added, noting that PPP was created amid enormous societal fear and an unprecedented economic shutdown.

When COVID-19 was new and business closures were increasing, it was reasonable for many companies to believe a government loan may be necessary to survive the pandemic, he noted.

The number of jobs saved by PPP is difficult to quantify, with estimates ranging from as few as 1.5 million to as many as 18.6 million. But ultimately, Talerman said, “I would still say that in terms of an awful lot of small businesses, PPP saved the day.”

“They wanted it to be forgiven quickly”

The Small Business Administration’s Patrick Kelley speaks during a Senate COVID oversight hearing on Aug. 2, 2022.

Mariam Zuhaib/AP


hide caption

toggle caption

Mariam Zuhaib/AP


The Small Business Administration’s Patrick Kelley speaks during a Senate COVID oversight hearing on Aug. 2, 2022.

Mariam Zuhaib/AP

Kelley, the SBA official, said it frustrates him when the SBA is criticized for its handling of the program because the agency took its guidance from Congress, which voted repeatedly to issue more loans and make them easier to forgive — even when it became obvious there was widespread fraud.

“I believe that Congress very clearly wanted this money to go out the door quickly, and they wanted it to be forgiven quickly,” he said.

Kelley also noted that Congress did not give the SBA authority to ask businesses whether, in retrospect, they truly required government assistance.

Saying to a company, “You know, it turns out that you probably didn’t need that loan; can you please give the money back?” was not an option for the agency, he said. As a result, for companies that flourished during the pandemic, a PPP loan sometimes became profit on top of profit.

Still, Kelley said he considers the Paycheck Protection Program a mighty feat that did more good than harm.

“It’s an easy sentiment, in my opinion, to say, ‘Well, there goes the government again. Why didn’t they do it right?’ But to me, it ignores the awesomeness of what did get done right,” he said. “I’ve met many, many, many, many, many more people who are thankful for the relief that we chose to do as a society together.”

But when pressed on why the government wasn’t more stringent in both approving loans and forgiving them, and why it is now scrambling to recover money that has already been paid out, Kelley said, “These are excellent questions for Secretary Mnuchin from the Trump administration.”

“My personal opinion? … That’s a totally different interview”

Michael Faulkender, a Treasury official under President Trump, speaks at a Senate Finance Committee hearing in 2018.

Al Drago/Bloomberg via Getty Images


hide caption

toggle caption

Al Drago/Bloomberg via Getty Images


Michael Faulkender, a Treasury official under President Trump, speaks at a Senate Finance Committee hearing in 2018.

Al Drago/Bloomberg via Getty Images

NPR’s request for comment from Mnuchin — who started a new private equity fund after leaving the Trump White House — was returned by Michael Faulkender, who served as an assistant Treasury secretary under Mnuchin and is a finance professor at the University of Maryland.

In an interview, Faulkender said the government always intended the vast majority of PPP loans to be forgiven and deliberately made speed the priority when launching the program, despite the risk of fraud. For example, about $3.6 billion in loans mistakenly went to people on the Treasury’s “Do Not Pay” list, according to the SBA’s inspector general.

Still, “because PPP got up and running, because all of those small businesses were able to maintain people on payroll, we did not realize the catastrophe that could have taken place had we failed,” Faulkender said. “What would bread lines during a pandemic have looked like? Do we want to know? I didn’t. And so we were going to get that program up and running.”

Echoing Kelley, Faulkender said the SBA’s responsibility was to implement the PPP legislation enacted by Congress, not to question congressional decision-making. And he said he believes the program rescued many people from unemployment.

“So from that perspective, I’m very proud of the work that we did at Treasury,” he said. “My personal opinion as an academic economist who evaluates the program? That’s a totally different interview.”

Elaborating, Faulkender said that, over time, Congress changed the purpose of PPP in a way that strayed from its original goal.

“At the front end, the program was very much let’s save employment. Later on, the program seemed to morph into let’s provide assistance to small businesses,” he said. “Whether or not we needed to morph that into a lot of small business grants, I can understand why that would be questionable.”

“You just want to tell these people, ‘Do your job!'”

So who are the small percentage of borrowers with unforgiven PPP loans?

According to NPR’s analysis of SBA data, the majority belong to one-person businesses — companies the Paycheck Protection Program most intended to help — and people whose loans were processed by financial technology companies, or fintechs, a nebulous term broadly defined as businesses that use technology to automate financial services.

Those two categories of borrowers are interrelated, because one-person companies were more likely to get their loans through fintechs than through traditional banks, which were criticized for neglecting smaller PPP applicants in favor of larger banking clients.

NPR found that the smallest businesses — sole proprietors like barbers, janitors and hairdressers — hold the highest rate of unforgiven loans, at 13{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. By contrast, only 3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of all businesses with at least 10 employees have unforgiven loans.

And in December, a lengthy congressional report accused several fintechs of hastily approving PPP loans to collect lucrative loan-processing fees, while ignoring obvious signs of borrower fraud. Meanwhile, a class-action lawsuit against the fintech Kabbage, which recently declared bankruptcy, alleges it was quick to approve PPP loans but dropped the ball when it came to forgiving them. Other fintechs appear to have a backlog of forgiveness requests, too.

In fact, according to an NPR analysis, about three-quarters of all unforgiven PPP loans involve fintechs.

Cape Cod landscaper Candy Crawford, a sole proprietor, became ensnared in that fintech muddle.

Candy Crawford, of Handy Candy landscaping, in a client’s garden in Provincetown, Mass. She received a $1,022 PPP loan through PayPal that was later sold to another company. It took her more than two years to get it forgiven.

Kayana Szymczak for NPR


hide caption

toggle caption

Kayana Szymczak for NPR


Candy Crawford, of Handy Candy landscaping, in a client’s garden in Provincetown, Mass. She received a $1,022 PPP loan through PayPal that was later sold to another company. It took her more than two years to get it forgiven.

Kayana Szymczak for NPR

In spring 2020, her tiny landscaping company, Handy Candy, got a PPP loan of $1,022 through PayPal. She later learned that her loan had been sold to another company, and it ultimately took her more than two years to get it forgiven.

“The amount of energy and time I spent! You just want to tell these people, ‘Do your job!'” Crawford said. “But you have to be nice because you’re at their mercy.”

Other small-business owners interviewed by NPR listed a variety of reasons for having unforgiven PPP loans, including getting bad advice from accountants, misunderstanding the program’s rules, and mistakenly thinking forgiveness was automatic.

Some borrowers also pointed out that when you’re a busy small company with no support staff, you can’t delegate work. That’s the case for Katy Escher, who co-owns an Eastham, Mass., shop called ARTichoke and got an $8,275 PPP loan through Square. Since running into complications with her forgiveness application, she’s struggled to get answers.

Katy Escher co-owns ARTichoke in Eastham, Mass., which received an $8,275 PPP loan through Square that remains unforgiven.

Kayana Szymczak for NPR


hide caption

toggle caption

Kayana Szymczak for NPR


Katy Escher co-owns ARTichoke in Eastham, Mass., which received an $8,275 PPP loan through Square that remains unforgiven.

Kayana Szymczak for NPR

“I can’t get ahold of the SBA, and then when I talk to a human being on Square, they tell us to contact the SBA,” Escher said, “so we’re just in teeter-totter land here.”

For now, ARTichoke’s forgiveness request remains in limbo.

“We wear many hats, and sometimes you have to choose which hat you have to wear based on the season or the time,” she added. “I wish that we had someone to say, ‘Hey, we need to figure this out,’ but we don’t.”

In the meantime, after the release of last month’s congressional report, the SBA announced that it has suspended fintechs Blueacorn and Womply from working with the agency “in any capacity.” The SBA also said it has “launched a full investigation” of several other fintechs.

“All of these small businesses … they were just torturing them,” said Nancy Kelly, owner of a small Boston accounting firm that got a $60,000 PPP loan through Kabbage, and who described the forgiveness process as a prolonged ordeal. “If I had known the difficulty, I would have just lived without the loan.”

“A very costly thing to do”

If another financial crisis comes, will the government be better financially prepared?

David Autor, the MIT economist, has his doubts. He argues that even if Congress and the SBA had tried to administer the Paycheck Protection Program more efficiently, the antiquated state of many U.S. government technological systems would have made that difficult.

In the case of PPP, that meant the Treasury and SBA were unable to precisely target companies that most needed pandemic-related financial assistance — something many European countries were able to do through “short-time work” programs, which, aided by government access to payroll data, helped companies reduce hours rather than resort to layoffs.

ARTichoke’s PPP loan forgiveness request remains in limbo.

Kayana Szymczak for NPR


hide caption

toggle caption

Kayana Szymczak for NPR


ARTichoke’s PPP loan forgiveness request remains in limbo.

Kayana Szymczak for NPR

Instead, the U.S. government blindly gushed a massive amount of money into its economy and hoped for the best, Autor said.

“It’s as if you came home from work one day, walked into your kitchen, and noticed, ‘Oh my God, there’s a small fire by the stove — I need to put this out.’ But you don’t have a fire extinguisher,” he said. “So you go outside, connect a huge hose to a fire hydrant, and come in and douse your entire house with water. Well, that would certainly put out the fire, but it would be a very costly thing to do.”

In that sense, he said, the Paycheck Protection Program prioritized speed over accuracy at a very high price — and continues to do so by forgiving the majority of loans, including many flagged as suspicious.

That infuriates Beba Touloupis, who with her husband co-owns Ted’s Restaurant in Birmingham, Ala., which serves cafeteria-style Southern cooking. When COVID shutdowns left them able to sell only takeout orders, they watched their business plummet from more than 200 people a day to as few as 10. A $45,000 PPP loan kept some of their workers on the payroll, but so far the loan remains unforgiven.

So Touloupis was shocked when a longtime customer told her he received a PPP loan that he said wasn’t necessary for his company’s survival, yet was forgiven.

“He had the nerve to tell me that he got money and he didn’t need it,” Touloupis said. “And that was, like, three times the amount of money I got — maybe four. And I looked at him and thought, ‘I don’t ever want to see you in my restaurant again.'”

She said she is disgusted that while the pandemic was devastating for many restaurants, hotels and other hospitality businesses, other companies thrived during COVID yet got their PPP loans forgiven.

“While I’m here, trying to keep these doors open and keep my employees working,” she added. “It’s wrong. It is so wrong.”

Roy Thurston owns the Blue Heron Gallery in Wellfleet, Mass., which received $14,000 in PPP loans, all forgiven. He questions why businesses like TB12, a sports nutrition company co-founded by NFL quarterback Tom Brady, were also eligible for the program.

Kayana Szymczak for NPR


hide caption

toggle caption

Kayana Szymczak for NPR


Roy Thurston owns the Blue Heron Gallery in Wellfleet, Mass., which received $14,000 in PPP loans, all forgiven. He questions why businesses like TB12, a sports nutrition company co-founded by NFL quarterback Tom Brady, were also eligible for the program.

Kayana Szymczak for NPR

Roy Thurston, owner of the Blue Heron Gallery in Wellfleet, Mass., a seasonal Cape Cod business that opened about a month later than usual in 2020 due to COVID shutdowns, shares Touloupis’ frustration.

Thurston received about $14,000 in PPP loans, all forgiven, and questions why businesses like TB12, a sports nutrition company co-founded by NFL quarterback Tom Brady, were also eligible. TB12 got a PPP loan for about $960,000, also forgiven — even though, Thurston notes, Brady bought a yacht in 2021 with an estimated price tag of $6 million.

“What bothers me is the people that took money that should have known better than to take money,” Thurston said. “It should have been for people who really needed it.”

The Blue Heron Gallery, a seasonal Cape Cod business, opened about a month later than usual in 2020 due to COVID shutdowns.

Kayana Szymczak for NPR


hide caption

toggle caption

Kayana Szymczak for NPR


The Blue Heron Gallery, a seasonal Cape Cod business, opened about a month later than usual in 2020 due to COVID shutdowns.

Kayana Szymczak for NPR

In the meantime, the Paycheck Protection Program has contributed to the country’s $31 trillion federal debt, an amount that eventually could lead to higher taxes and fewer government services.

“Basically,” said MIT’s Autor, “we’ve just put a huge debt on our children to pay people in the present.”

This story was edited by Meg Anderson and Barrie Hardymon. Sierra Lyons contributed to the reporting. Art direction and photo editing by Emily Bogle.

Delinquent student loans can reduce Social Security by $2,500 a year

Delinquent student loans can reduce Social Security by $2,500 a year

A Social Safety Administration business office in San Francisco.

Getty Photos

If you are delinquent on federal student financial loans and obtain Social Protection positive aspects, your every month checks could be diminished.

A pandemic pause has place all garnishments on maintain for now.

But when collections are in impact, the reduction in yearly Social Safety added benefits is about $2,500 on common, based on 2019 facts, in accordance to new investigation from the Center for Retirement Exploration at Boston School.

That usually quantities to 4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of family earnings, a major sum that could pay out off the average person’s credit rating card equilibrium, the research discovered.

Extra from Personalized Finance:
63{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of People in america are dwelling paycheck to paycheck
‘Risky behaviors’ are triggering credit score scores to stage off
4 strategies can enable you continue to be out of financial debt this vacation year

The variety of Social Stability beneficiaries who locate them selves in this scenario is smaller, primarily based on delinquency prices. Considerably less than 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of beneficiaries now have college student mortgage credit card debt.

But those people balances are predicted to be “significantly” greater for future beneficiaries, who are also anticipated to have increased delinquency prices, according to the analysis.

“Amongst young cohorts, the share of people today keeping student financial loans are considerably larger,” claimed Siyan Liu, investigation economist at the Centre for Retirement Analysis.

“If that carries on on into retirement, then a considerably bigger proportion of them, if they have hassle earning payments, could be facing profit upsets,” she explained.

Social Safety added benefits are normally topic to partial withholdings after prolonged federal college student financial loan delinquencies.

The Social Protection withholding amount for scholar mortgage debtors is typically possibly 15{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the overall every month profit or the amount by which the reward exceeds $750 for every thirty day period — whichever is less.

“It has been a real problem for persons who are on a mounted revenue and have no other help,” claimed Adam Minsky, a Boston-dependent law firm specializing in university student bank loan legislation.

“That 15{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} actually can make the distinction concerning currently being equipped to pay for rent or food or medication,” Minsky stated.

Social Safety profit withholding usually happens after 425 days of delinquency has handed and a bank loan holder fails to restart reimbursement.

The income withheld is utilized to the federal financial loan balances.

How a lot funds is at stake

About 2.7 million individuals ages 62 and up owed more than $107.3 billion in federal loans as of September, according to the U.S. Department of Schooling.

The common annual Social Security profit at danger thanks to university student financial loan delinquency is envisioned to boost to $2,594 for future beneficiaries — these at this time ages 35 to 61 — up from $2,299 for present beneficiaries ages 62 and up, centered on 2019 details, according to the Middle for Retirement Analysis.

Even so, the share of family income at risk is envisioned to decline to 4.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for long term beneficiaries, down from 6.1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for current beneficiaries.

Present day Social Safety beneficiaries who are driving on federal college student financial loans are not topic to gain withholdings, as those collections have been suspended as element of the federal college student mortgage payment pause that has been in influence because March 2020, Minsky pointed out.

“No just one is possessing their Social Stability checks garnished suitable now,” Minsky reported.

President Joe Biden’s Fresh Get started initiative is slated to give borrowers a complete 12 months just after the payment pause finishes to consider to get out of default in advance of collections on benefits resume, he mentioned.

How coverage may possibly influence money owed

The approach would also have a dramatic impression on delinquency rates, as delinquent debtors could have their full balances forgiven.

While Black borrowers stand to see the most significant reduce in delinquency fees, Hispanic borrowers would see the biggest relative decrease, the investigate identified.

Mainly because Biden’s strategy would reduce both of those financial debt and delinquency for long run retirees, it would also shrink racial inequality, the Middle for Retirement Analysis explained.

Some Democratic lawmakers are also eyeing a different way of offering aid.

Biden administrations stops taking applications for student loan debt forgiveness

In December, four Dwelling Democrats introduced a bill, the College student Personal loan Relief for Medicare and Social Stability Recipients Act, that would eradicate scholar financial loan personal debt balances held for far more than 20 yrs by Medicare and Social Protection disability insurance beneficiaries.

It stays to be seen no matter whether the proposal may possibly acquire traction on Capitol Hill.

“We should reduce as considerably university student credit card debt as we can for anyone, but primarily for those people who have expended decades of their life functioning to shell out it off,” Rep. Adam Schiff, D-Calif., reported in a assertion. “This invoice would guarantee that rather of triaging their positive aspects, seniors and disabled people can emphasis much more on their health, their families, and flourishing in their most effective many years.”

New law links your student loans with retirement savings

New law links your student loans with retirement savings

Tucked inside the $1.7 trillion authorities paying out monthly bill established to be signed by President Biden this 7 days are a host of important retirement reforms, which includes a collection of provisions that professionals say is nothing at all small of a redefinition of the private retirement system alone.

The significantly-achieving new legislation has ideas that backlink people’s efforts to preserve for the long run with more urgent requirements, especially struggles to spend off college student financial loans and put money aside for an emergency.

The adjustments for 2023 will “stretch and increase the retirement procedure to figure out that people’s economic lives are interwoven and complicated,” explained Timothy Flacke, the co-founder of a nonprofit termed Commonwealth that labored with Congress and the personal sector on the unexpected emergency savings provisions.

He and others have pushed for the provisions, specially those all-around crisis financial savings, as a way to give lower-earnings Us citizens much more assist in the coming years and head off what a lot of fret is a burgeoning retirement cost savings crisis in the U.S.

“We will need to discover a way to stability today’s requires with tomorrow’s requirements,” reported Chantel Sheaks, a vice president focused on retirement coverage at the U.S. Chamber of Commerce. “Regrettably, I feel what we have been performing in this area is only hunting at 1 or the other.”

U.S. President Joe Biden speaks to the media before receiving a briefing about winter storm systems moving through the U.S., at the Oval Office at the White House in Washington, U.S., December 22, 2022. REUTERS/Leah Millis

President Biden us set to sign the $1.7 trillion governing administration funding monthly bill into regulation this 7 days. (REUTERS/Leah Millis)

A connection in between retirement saving and college student financial loans repayments

Of interest to persons holding college student financial loans is Portion 110 of the monthly bill that treats student financial loans as deferrals for the intent of retirement personal savings.

What that means in exercise is, starting in 2024, if the company chooses to deliver the reward, a employee could publish a test for their month to month pupil bank loan monthly bill, but in the process also generate a “match” for their 401(k), 403(b), or Straightforward IRA account

Proponents of the new law say it will assistance younger folks stay away from lacking out on many years of conserving and the compound interest that builds up when men and women start out early. A 2019 review from Bankrate located that 29{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of college graduates with college student financial loans delayed retirement cost savings. An additional study, from the Employee Advantage Investigation Institute, identified that keeping college student personal loan credit card debt is a crucial issue in how a lot homes have been able to help you save.

This thought of enabling simultaneous college student personal loan payments and retirement personal savings has bounced all-around Washington for decades and has gradually obtained bipartisan guidance. Sen. Ron Wyden of Oregon place ahead a bill in 2019 with Republicans like Rep. Fred Keller (R-PA) also championing the exertion more than the several years.

WASHINGTON, DC - JULY 27: A sign asking President Biden to Cancel Student Debt is seen posted on Pennsylvania Ave near the white house staff entrance during a demonstration demanding that President Biden cancel student loan debt in August on July 27, 2022 at the Executive Offices in Washington, DC. (Photo by Jemal Countess/Getty Images for We, The 45 Million)

A indication inquiring President Biden to terminate student personal debt is posted near the White Dwelling. (Jemal Countess/Getty Images for We, The 45 Million)

New rule to get ‘workers into unexpected emergency savings’

Also in the invoice (Sections 115 and 127) are similar ideas that will hyperlink retirement and crisis preserving.

The Federal Reserve has carefully tracked the large share of People who have to scramble to deal with a hypothetical cost of $400 for one thing like an unpredicted auto restore. As of 2022, the Fed found that this common situation would characterize a hardship for just about a third of American households.

The new law aims to be a hedge against that by allowing for employers to give their non-highly compensated workforce an option of putting dollars into a “sidecar account” together with their retirement account. Staff members would be equipped to conserve up to $2,500 that could be accessed at any time for any rationale.

The monthly bill also would allow for employers to present a savings match — comparable to the college student loan provision — if they so decide on. That provision was created by Sens. Cory Booker (D-NJ) and Todd Younger (R-IN).

WASHINGTON, DC - JULY 19: Sen. Todd Young (R-IN) (L) talks Sen. Cory Booker (D-NJ) just outside the Senate Chamber at the U.S. Capitol on July 19, 2022 in Washington, DC. Young, a key United States Innovation and Competition Act supporter who is working to insert commerce and national security provisions into the bill, said that fellow Republicans are now pushing to grow the Chips for America Act, which is designed to strengthen the U.S. semiconductor industry and reduce dependence on Chinese and Taiwanese manufacturers.

Sen. Todd Youthful (R-IN) (L) talks Sen. Cory Booker (D-NJ) just outside the Senate Chamber in July. (Chip Somodevilla/Getty Visuals)

The critical stage, in accordance to numerous specialists, is that the provision includes the option of automated enrollment, so employees would start putting apart for emergencies by default. Lawmakers had also hoped to contain a further provision letting employers to automatically enroll employees into an unexpected emergency cost savings account even if a retirement program wasn’t available, but it was not prepared in time for passage this year.

An additional component of the bill will make it less complicated for men and women to access their present retirement designs for emergencies with no shelling out the onerous tax penalties that often appear with withdrawing early.

That effort and hard work, championed by Sens. James Lankford (R-Okay) and Michael Bennet (D-CO), supplies an “exception for specified distributions utilised for crisis charges,” according to a summary of the legislation. Contributors would be capable to acquire out up to $1,000 a yr penalty-totally free and would be essential to shell out back the funds down the street.

“Not obtaining crisis discounts can have both limited- and extended-time period impacts,” reported Jeff Cimini, a senior vice president at Voya, including that his business has observed that personnel with an unexpected emergency price savings backstop lead to their very long-expression retirement prepare about 50{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} more than they would normally.

‘You really don’t transform massive techniques that serve tens of billions of individuals overnight’

“The pathway now is prepare suppliers, file keepers, the vendor group stepping up to turn the chance in the legislation into serious attributes that they can supply their shoppers,” claimed Flacke, introducing that he is optimistic primarily based on the opinions he is getting that these provisions will conclude up assisting tens of thousands and thousands of folks in the several years ahead.

“You really don’t change massive programs that serve tens of billions of individuals right away, but the development traces glance favourable,” he claimed.

Devin Miller, the founder of a company that gives emergency cost savings accounts termed SecureSave, lately likened it to the early times of wellness discounts accounts, or HSAs.

“Once workforce know about this notion, it is typically one of their top rated options that an employer could supply,” he explained.

Even now, all sides concur that the provisions are just a first step that lawmakers hope to create on in the years ahead to provide additional much-reaching modifications that will influence a lot more Americans. For example, this year’s retirement invoice will not tackle the challenge of Social Safety, which could run low on funds as early as 2034.

And when it comes to the personal retirement program, Tim Shaw of the Aspen Institute points to the challenges in advance. He released a assertion last 7 days hailing the invoice, but rapidly additional “come January, it’s time to get back again to operate as 57 million U.S. staff nevertheless absence accessibility to office retirement plans.”

Ben Werschkul is a Washington correspondent for Yahoo Finance.

Read through the most current money and organization information from Yahoo Finance

Follow Yahoo Finance on Twitter, Facebook, Instagram, Flipboard, LinkedIn, YouTube, and reddit.

George Santos’ Massive Campaign Loans May Not Be Legal

George Santos’ Massive Campaign Loans May Not Be Legal

Fork out Filth is a weekly foray into the pigpen of political funding. Subscribe right here to get it in your inbox every Thursday.

Even as Rep.-elect George Santos (R-NY) embarks on his apology tour, admitting he lied to voters for decades about some of the most basic points of his existence, there is been a single secret that Santos has been significantly less than obvious about: wherever his purported tens of millions came from.

The Everyday Beast now has at minimum element of the answer—the identities of 4 Santos company purchasers. And when this new revelation may possibly put Santos in even much more scorching drinking water, what Santos did with his newfound riches could be even a lot more damning.

Santos has already admitted utilizing money from his corporation, the Devolder Corporation, to fund his campaign—a shift marketing campaign finance experts say could add up to an unlawful $700,000 corporate contribution.

That is because, while candidates for federal business might give unlimited amounts of their very own income to their marketing campaign, they are not able to expressly faucet company accounts to do so.

Santos verified to The Day by day Beast on Wednesday that he withdrew cash from the organization to underwrite his marketing campaign. He made the same claim in an interview on Monday, telling WABC radio host and Santos donor John Catsimatidis that the put together $700,000 in loans—scattered in different increments across a time period of extra than a year—“was the funds I paid out myself as a result of the Devolder Firm.” (Santos’ most new money disclosure exhibits a $750,000 salary from the Devolder Corporation, along with dividends valued in between $1 million and $5 million.)

Jordan Libowitz, communications director of authorities watchdog Citizens for Duty and Ethics in Washington, instructed The Every day Beast that the authorities imposes stringent policies on how candidates can help their strategies.

“You can fund a campaign with your individual revenue to whichever extent you’d like, but the deal is it has to be your funds,” Libowitz explained. “Two main troubles listed here. A single, if it is the company’s cash, it’s not his cash. If it had been Santos individually executing organization as the company—that is, if it had been his bank accounts—that’s okay. But this is an real company, and you simply cannot make a corporation to run revenue through to your marketing campaign.”

The explanation, he discussed, is that these kinds of a scheme hides the origin of the funds.

“We know in previous filings he did not have pretty substantially income at all, so it raises a massive question of what the origins of this $700,000 are,” Libowitz claimed.

“If I wished to illegally fund a marketing campaign and disguise it, what I would do is run the dollars as a result of a dummy company, then to a dim income team that supports the campaign. But if I was not that up on issues, or a very little lazy, I could possibly … set up the dummy corporation, say it’s in the title of the applicant, then have the candidate shell out himself the income and give it to the campaign,” Libowitz said. “This isn’t to say that this is plainly an unlawful pass-as a result of donation plan, mainly because we do not know the whole picture yet—but if it were being just one, this is what it would look like.”

Brendan Fischer, deputy executive director of federal government watchdog Documented, mentioned that corporate contributions to campaigns and management PACs are expressly prohibited—Santos built loans to both—with “knowing and willful” violations carrying attainable legal fees.

“Santos may be in a tough area either way you slice it,” Fischer informed The Daily Beast.

Speculating on the choices, Fischer reported, “One idea is that the Devolder Group was a shell that functioned to allow for rich donors to secretly bankroll Santos’s 2022 operate for Congress. If that [were] the circumstance, it could implicate not just Santos but any one who used it to knowingly evade disclosure specifications and contribution limits. But even if the Devolder Corporation [is] a legitimate organization, then Santos could however have violated the legislation if he diverted corporate resources to his marketing campaign.”

Simply transferring funds from Devolder’s account to Santos’ possess account would not magically rework the resources into Santos’ private belongings, Fischer described.

“A prospect may possibly lend own funds to his campaign, but they may perhaps not do so working with company resources. A bank loan is taken care of as a contribution, and firms are barred from making contributions,” he mentioned.

Santos was concurrently functioning for federal office—a demanding undertaking for any candidate—while spinning up the Devolder Corporation as a worthwhile money solutions corporation. Fischer speculated that investigators could “follow the paper trail to verify Santos’ description of using company resources to fund his campaign—for instance, by matching dates of withdrawals to the dates he designed the loans.”

Santos has mentioned he worked in the “funds introduction” company, wherever he would link wealthy people today looking to promote items like a boat or aircraft with other rich people today seeking to buy a boat or airplane.

Santos, who in 2020 noted keeping no belongings and a income of $55,000 from a vice president placement at a money enterprise termed LinkBridge, seems to have all of a sudden appear into significant wealth, professing a web well worth of as much as $11.5 million on his 2022 fiscal disclosure. Pretty much all of it arrived by the recently formed Devolder Business, which the 34-yr-previous claims paid out him amongst $1 million and $5 million in dividends along with one more $750,000 in salary.

In a discussion with The Daily Beast on Wednesday, Santos argued the money he moved from the Devolder Corporation to his marketing campaign was legally loaned from his very own individual resources, mainly because he was the company’s sole owner.

But the corporation is not legally indistinguishable from Santos—it is registered with the condition of Florida as an impartial LLC, and it has its own accounts independent from him individually.

Informed of the principles, Santos promised he would “immediately” search into the subject and rectify something that required to be dealt with. That may well be an monumental undertaking, specified the total of firm cash Santos seems to have put into his political endeavours.

That money, it turns out, arrived from some wealthy sources who also had financial stakes in Santos’ political bid.

The Daily Beast has verified 4 Devolder Group purchasers: the New York-dependent Tantillo Vehicle Group, two organizations tied to the influential Ruiz household in south Florida, and yet another agency affiliated with Extensive Island coverage magnate James C. Metzger. Santos acknowledged all 4 of these clientele on Wednesday.

Members of the Tantillo and Ruiz family members, along with Metzger, also all come about to be Santos campaign donors. And some of them have additional stakes in the Extensive Island political scene, like important donations to prime Santos ally Rep. Lee Zeldin (R-NY), who shed his bid for governor this year.

3 customers of the Tantillo relatives gave $44,800 to Santos’ political endeavours, in accordance to Federal Election Commission information. 3 users of the Ruiz spouse and children, who look on the incorporation files, have supplied $17,300. Metzger gave $23,700. (The donations contain huge items to the Devolder Santos Victory Committee—and in Metzger’s circumstance, Devolder Santos Nassau Victory Committee—joint fundraising groups that break up income concerning the congressman’s marketing campaign and his management PAC.)

None of the donors gave to Santos prior to 2022.

As The New York Occasions described in its very first post past week dismantling several of the fresh-faced Republican’s lies, none of the companies appeared on the monetary disclosure Santos submitted this calendar year. That failing, the Moments claimed, could operate afoul of Property ethics guidelines.

Santos told The Everyday Beast he was in the system of amending his disclosure to be completely clear, and he explained he would file the disclosure upcoming week.

Questioned if he could validate the comprehensive slate of clientele that would show up on that amendment, Santos replied that “under legal advisement, I can’t do that for the very simple fact of what was lacking, and what discrepancies have been accomplished there to fill in the blanks.”

He included that he had “nothing to hide” and was “doing my best” to “come clean” and atone for the lies he fed voters. He emphasised that he also wished to glimpse out for his clients’ most effective passions, and didn’t want them “burdened” by the political gauntlet he’s at this time running via, as the media commences to unravel his untrue statements, along with other strategies that did not floor in both of his two congressional strategies.

But public data already reveal a terrific deal. Florida company filings display two Devolder LLC, were being designed about two weeks aside in January 2022. Their management is made up of kinfolk of billionaire Miami attorney John Ruiz, a own harm and class action law firm who parlayed his Medicare payor restoration business enterprise into a multibillion-greenback IPO that flopped this summer season.

In September 2021, Alex Ruiz, then 22, grew to become CEO of Cigarette Racing, a renowned luxurious powerboat company which his loved ones took above in the study course of making their multibillion-dollar exclusive purpose acquisition corporation (SPAC).

A several months later, the Ruiz kids established the entities that would keep the Devolder Firm. Mayra Ruiz instructed The Day-to-day Beast they employed the Devolder Organization in “early” 2022, but did not reply to stick to-ups. Notably, in an interview with Semafor on Wednesday, Santos named yacht profits as just one of the tasks the Devolder Corporation dealt with for its customers.

On March 31, Mayra Ruiz contributed $10,800 to Santos’ joint fundraising committee.

Other campaign finance filings reveal the extent to which Santos’ business enterprise customers were entangled not only with his campaign but with Zeldin’s—and with the community political infrastructure that supported them each.

For instance, the Tantillo Car Team controls a cluster of new and employed motor vehicle plenty in Extensive Island, quite a few in Zeldin’s Residence district. Patriarch Raymond Tantillo gave $50,000 to Zeldin’s gubernatorial campaign, “Zeldin for New York,” with the Tantillo Car Group pitching in a different $5,000. Catherine Tantillo also donated $50,000 to Zeldin’s in the long run unsuccessful Albany bid in March 2022.

Metzger, CEO of insurance coverage company The Whitmore Group—is an additional major New York GOP donor. In the 2022 election, he contributed $60,000 to Zeldin for New York, state data demonstrate, together with $155,000 to the Nassau County Republican Social gathering, on Santos’ property turf. The regional device lent Santos considerable aid through the campaign, equally forming joint fundraising committees with his operation and spending for his lawn symptoms, while Nassau County Republican Get together management has due to the fact expressed disaffection with Santos.

“Congressman-elect George Santos has damaged the community trust by earning significant misstatements concerning his track record, experience and training, amongst other concerns,” Nassau County Republican Party Chairman Joseph Cairo said in a press release this 7 days.

The Devolder Business contracted with Whitmore’s mother or father business, Acrisure, an agreement the congressman-elect in a dialogue Wednesday clarified was not with Whitmore Group specially, however he mentioned he did not know how to spell Acrisure.

“That’s a great concern,” Santos informed The Every day Beast. (Acrisure acquired the legal rights to Acrisure Stadium, household of the Pittsburgh Steelers.)

And the website extends past even the Devolder Organization’s buyers. Concurrent with Santos’ second, effective congressional bid, his sister ran a political motion committee termed Rise NY PAC. The group’s internet site is currently down and was past archived in August this calendar year. Whilst it professed to also have functions in California and Colorado, there is no document of it raising or shelling out cash outside the Empire Condition.

The elements filed in New York show that Rise NY PAC compensated all around $25,000 to the Santos sibling, who he claims life with him in Long Island. Rise NY PAC also paid about $50,000 to a gentleman named Harry Brar—the head of Nassau County Asian Affairs, who was arrested in September for allegedly choking a 10-12 months-old boy and assaulting his mother.

Increase NY PAC poured cash into the Zeldin- and Santos-boosting Nassau County Republican Social gathering, as perfectly as into a city GOP committee that in convert gave heavily to the county organization. The PAC also counted among the its contributors the financier Andrew Intrater, cousin and dollars-supervisor to the sanctioned Russian oligarch Viktor Vekselberg, who contributed a merged $80,000 to the PAC, for every condition documents. Intrater and his spouse had been also two of the most significant donors to the two Zeldin and Santos.

Santos has arrive under expanding pressure and scrutiny given that the Instances claimed earlier this month that he experienced fabricated quite a few facts of his career, such as his supposed possession of a college or university diploma and stints at prominent economic establishments. This story followed an posting by The Every day Beast this previous April, which uncovered his operate for an alleged multi-million-dollar Ponzi plan. A number of of his coworkers from the accused expenditure rip-off, none of whom have been charged with a crime, fashioned a political consulting team with the Devolder Business following the scandal broke.

The Each day Beast subsequently learned that Santos, who has manufactured his gay id a central part of his political brand, experienced been married to a lady for several years—almost appropriate up to the launch of his first congressional campaign in 2019. The Forward also located that Santos’ claims of Jewish roots were being also devoid of basis, one thing the politician later on confessed, even as he bizarrely claimed that family members lore allowed him to determine as “Jew-ish.”

He has also insisted he will be seated in the upcoming Congress, inspite of calls for him to resign.

Facing climate change, Asia farmers turn to risky microfinance loans

Facing climate change, Asia farmers turn to risky microfinance loans

The “microfinance” field — prolonged touted as a way to assist poor, rural communities in developing countries — is pushing tens of countless numbers of farming households into financial debt traps as they try to adapt to a transforming weather, according to a report.

The examine, conducted by researchers at a group of U.K. universities, appeared at a vary of situation research in Cambodia, where it identified straightforward-obtain financial loans had brought on an “overindebtedness unexpected emergency” that was undermining borrowers’ prolonged-time period skill to cope with their new setting.

Modern microfinance institutions (MFIs), which are frequently compact, domestically operate companies with a wide range of funding resources such as global investors, banks and advancement companies, emerged in the 1970s and grew fast in the early 2000s. They ended up promoted as a way to present economic products and services, usually smaller performing funds loans but also savings accounts and insurance policy, to the traditionally unbanked — these types of as women and folks on really lower incomes.

In Cambodia, close to 61{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of individuals are living in rural areas, and 77{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of rural homes count on agriculture, fisheries, and forestry for their livelihoods, according to improvement agency USAID.

Several have observed these standard livelihoods influenced by a mix of local weather modify, over-advancement and illegal logging and fishing, with rising droughts, wildfires and unpredictable rainfall patterns triggering crop losses and hurt to the ecosystem of Cambodia’s crucial Tonle Sap lake.

The establishment of hundreds of MFI branches because the early 2010s, which can be observed advertising and marketing expert services together roadsides all around the place of 17 million men and women, has frequently harmed alternatively than aided these afflicted, the report revealed in September located.

In its study of close to 1,800 borrowers, about 50 percent cited feeding their spouse and children as their main determination.

But the authors say the financial loans are increasingly becoming taken up to provider present credit card debt from a blend of formal and informal resources, relatively than getting place toward local weather-adaptive investments. The loans are also observing farmers put property which include their land up as collateral, even when the loans are substantial-fascination and have limited compensation home windows.

A Maxima Microfinance department in Kandal Province, Cambodia, in July 2018. The institution of hundreds of nearby MFI branches given that the early 2010s has frequently harmed somewhat than served people afflicted, a report observed.

Taylor Weidman | Bloomberg | Getty Visuals

NGOs estimate around 167,000 Cambodians have offered their land to pay back microfinance loans above the previous 5 years.

The amount of microfinance indebtedness in Cambodia at the finish of 2021 was $4,213 for each capita, additional than double gross domestic product for each capita. All around 2.6 million people today have taken out microloans.

“The financial debt load created by the nexus amongst weather change and microfinance makes tremendous issues for several people and communities causing bodily and emotional stress,” stated Ian Fry, United Nations distinctive rapporteur on human rights within local weather alter, who also acknowledged microfinance experienced been promoted by the U.N., Earth Financial institution and other intercontinental businesses.

Some oversight of the market does exist. MFIs are necessary to sign-up with the Countrywide Bank of Cambodia, the country’s central bank, which in December 2021 stopped issuing new licenses and advised establishments to boost the “high quality, effectiveness and affordability” of their solutions. In 2017, it capped microloan curiosity fees at 18{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} annually.

The Cambodia Microfinance Affiliation, a trade overall body, maintains that MFI loans have an general optimistic influence in growing cash flow and land ownership, and has issued lending suggestions to “lower the risk of excessive credit card debt” for shoppers. It has also strike again at critiques of the industry by NGOs and in previous experiences. The NBC and CMA did not answer to requests for comment.

Sounding the alarm

The challenges surrounding microfinancing establishments in Cambodia — and all-around the environment, from South Africa to India to Mexico — have been highlighted by NGOs and journalists for approximately a 10 years.

Microfinance establishments globally had an believed gross personal loan portfolio of $124 billion in 2019.

In some situations it has been observed to have positive consequences. A 2016 reserve printed by the Entire world Bank argued microfinance loans had diminished poverty and amplified incomes in Bangladesh, and banking huge HSBC nonetheless promotes its funding of microfinance in the region.

But the Planet Financial institution, an early and longstanding advocate of microfinance, has also been warning for a long time of challenges which includes overindebtedness and the increasing commercialization of the marketplace.

Farmer in rice discipline. Kep. Cambodia. (Photograph by: Pascal Deloche/Godong/Common Illustrations or photos Group by means of Getty Photos)

Godong | Common Photos Group | Getty Photographs

In the 30 yrs of advocacy carried out by Cambodian human legal rights NGO Licadho, land-grabbing has been a single of the most prolific complications it addresses on the ground, its director, Naly Pilorge, instructed CNBC by mobile phone.

That is in part a legacy of the murderous Khmer Rouge routine, which banned personal land possession when it ran the place from 1975 to 1979 and left survivors without land deeds in the tumultuous yrs that followed.

“We begun noticing that in rural communities, workers had been shedding their land because of one more trouble even when they experienced secured their land titles — they have been getting rid of it to MFIs,” Pilorge said. “How can a farmer farm without having land?”

Individuals ended up getting forced to migrate and look for different operate, Licadho observed, which was difficult in the Cambodian economy, where by agriculture makes up all-around a fifth of GDP, and the greatest employer is the garment manufacturing facility sector, which has been strike tricky by the Covid-19 pandemic and EU sanctions.

Cambodia was badly affected by the pandemic, with earnings from tourism plunging from its all-time higher of $4.9 billion in 2019 to just above $184 million in 2021, according to federal government figures.

Licadho has carried out 4 study initiatives into issues encompassing microfinance to spotlight its risks, which includes one particular in 2021.

Motorists ride previous a Sonatra Microfinance Establishment Plc branch in Phnom Penh, Cambodia, on Friday, July 31, 2018.

Bloomberg | Bloomberg | Getty Images

“The numbers did not make sense. In a place perceived as producing, that struggled with tourism due to Covid, the MFI sector was still escalating at 30{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} every single 12 months, and the typical loan went from all-around $3,000 to $4,000,” Pilorge claimed.

“Some of the men and women getting available these amounts have by no means witnessed $500 in funds, enable alone $4,000, so when a person will come and features it in exchange for their land as collateral it is tempting.” Cambodia employs both equally the Cambodian riel and the U.S. dollar.

Loan kinds are intricate to the normal human being, she additional, but “a considerable part are offered to ethnic minorities who neither compose nor read Khmer. Men and women are signing with a thumb print.”

In the money Phnom Penh, she extra, she frequently meets men and women functioning seven times a 7 days to pay off spiraling MFI loans.

The 2022 report extra its guidance to prior calls for the establishment of debt aid and interest suspension systems. That should really be in tandem with initiatives to cancel and restructure the national credit card debt of nations around the world in developing countries, it explained.

Global obligation

It also said the global enhancement community ought to redirect aid absent from microfinance establishments and into much more focused initiatives, and argued there requirements to be much more “strong taxation and regulation of earnings, dividends, and capital gains created by the foreign owners of Cambodian microfinance institutions.”

The U.N.’s Ian Fry termed on the intercontinental finance group to “get potent heed of the suggestions discovered in this report and very seriously rethink their tactic to microfinance.”

Pilorge also took aim at global governments, funding establishments and buyers who are unsuccessful to reduce money staying funneled towards predatory activities.

“All these international investors, Asian, European, People in america and so on, even now perceive MFIs as a constructive point because of the original concept. It appears to be like superior, you get a significant return, most people thinks they are aiding very poor individuals. But there have been pink flags on each individual degree for 15 many years and they have been disregarded,” she explained.

“Traders are satisfied, they get the interest, the brokers get a foundation wage and fee, and the people who endure are the poorest.”

Bankman-Fried, FTX execs received billions in hidden loans, ex-Alameda CEO says

Bankman-Fried, FTX execs received billions in hidden loans, ex-Alameda CEO says

NEW YORK, Dec 23 (Reuters) – Sam Bankman-Fried and other FTX executives received billions of dollars in top secret financial loans from the crypto mogul’s Alameda Analysis, the hedge fund’s former chief instructed a decide when she pleaded guilty to her purpose in the exchange’s collapse.

Caroline Ellison, former main govt of Alameda Study, reported she agreed with Bankman-Fried to disguise from FTX’s investors, loan providers and prospects that the hedge fund could borrow endless sums from the exchange, in accordance a transcript of her Dec. 19 plea hearing that was unsealed on Friday.

“We geared up selected quarterly harmony sheets that concealed the extent of Alameda’s borrowing and the billions of dollars in financial loans that Alameda experienced built to FTX executives and to connected parties,” Ellison told U.S. District Choose Ronnie Abrams in Manhattan federal court, in accordance to the transcript.

Ellison and FTX co-founder Gary Wang the two pleaded guilty and are cooperating with prosecutors as portion of their plea agreements. Their sworn statements provide a preview of how two of Bankman-Fried’s previous associates could testify at trial versus him as prosecution witnesses.

In a different plea listening to, also on Dec. 19, Wang said he was directed to make changes to FTX’s code to give Alameda special privileges on the trading system, although being informed that others were telling investors and customers that Alameda experienced no such privileges.

Wang did not specify who gave him those directions.

Nicolas Roos, a prosecutor, said in court docket on Thursday that Bankman-Fried’s demo would incorporate proof from “numerous cooperating witnesses.” Roos reported Bankman-Fried carried out a “fraud of epic proportions” that led to the reduction of billions of pounds of client and investor money.

Bankman-Fried has acknowledged hazard-administration failures at FTX but explained he does not feel he has felony legal responsibility. He has not however entered a plea.

Bankman-Fried established FTX in 2019 and rode a growth in the values of bitcoin and other electronic belongings to come to be a billionaire quite a few instances over as very well as an influential donor to U.S. political strategies.

A flurry of buyer withdrawals in early November amid issues about commingling of FTX money with Alameda prompted FTX to declare individual bankruptcy on Nov. 11.

Bankman-Fried, 30, was produced on Thursday on $250 million bond. His spokesperson declined to remark on Ellison and Wang’s statements.

Lawyers for Wang and Ellison declined to comment.

Ellison advised the court that when investors in June 2022 recalled financial loans they had made to Alameda, she agreed with other individuals to borrow billions of pounds in FTX customer cash to repay them, knowledge that buyers had been not informed of the arrangement.

“I am truly sorry for what I did,” Ellison explained, incorporating that she is helping to recover purchaser property.

Wang also stated he realized what he was carrying out was mistaken.

The transcript of Ellison’s listening to was to begin with sealed out of worry that the disclosure of her cooperation could thwart prosecutors’ efforts to extradite Bankman-Fried from the Bahamas, in which he lived and exactly where FTX was based mostly, courtroom data confirmed.

Bankman-Fried was arrested in the capital Nassau on Dec. 12 and arrived in the United States on Wednesday after consenting to extradition.

A magistrate decide ordered him confined to his parents’ California dwelling right until demo.

On Friday evening, Abrams recused herself from the situation, expressing in a court buy that the regulation firm Davis Polk & Wardwell LLP, wherever her husband is a husband or wife, advised FTX in 2021.

The agency also represented events that could be adverse to FTX and Bankman-Fried in other proceedings, the judge said, and whilst her partner experienced no involvement in these issues, which “had been confidential and their compound is unknown to the Court docket,” she was recusing herself to keep away from a achievable conflict.

Reporting by Luc Cohen in New York Writing by Tom Hals in Wilmington, Del. Enhancing by Noeleen Walder, Matthew Lewis and Daniel Wallis

Our Criteria: The Thomson Reuters Have faith in Principles.