You may owe taxes for federal student loan forgiveness in these states

You may owe taxes for federal student loan forgiveness in these states

Marko Geber | DigitalVision | Getty Photographs

If you’re a single of the hundreds of thousands of Individuals anticipating pupil loan forgiveness, you won’t owe federal taxes. But that does not mean you’re off the hook at the state level.

Indiana is the newest to verify forgiveness will set off condition money taxes, and some debtors might owe county levies on prime of condition profits tax.

“As this legislation is obviously described, there is no need to have for extra administrative policies,” a spokesperson with Indiana’s Section of Revenue explained. “Any legislative alter have to appear from the Normal Assembly.”

A lot more from Individual Finance:
How to conserve 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} on airfare — if you you should not thoughts using some hazards
GOP could bring a lawful problem to scholar mortgage forgiveness
How marketplace overall health enrollees can claim a share of $603 million in rebates

A provision from the American Rescue Strategy of 2021 tends to make student bank loan forgiveness federally tax-totally free by means of 2025, and point out revenue taxes rely on no matter if and when you can find state conformity with federal tax laws.

Very last 7 days, Mississippi’s Department of Revenue verified with CNBC that student bank loan forgiveness will be taxable, and the North Carolina Department of Earnings shared the similar in a information launch.

Of study course, with condition laws in flux, it is really continue to attainable these tax procedures, between others, may well change.

Taxation is feasible in other states

In addition to Indiana, Mississippi and North Carolina, point out-degree taxation also may perhaps be feasible in Arkansas, California, Minnesota and Wisconsin, according to a preliminary investigation from the Tax Foundation.  

The group in the beginning approximated that 13 states may well tax college student loan forgiveness and has revised projections with updates.
Republicans weigh plans to fight Biden's student loan forgiveness

It now initiatives seven states — Arkansas, California, Indiana, Minnesota, Mississippi, North Carolina and Wisconsin — may perhaps tax college student personal loan forgiveness.

Taxing forgiveness is not probably in Massachusetts, but the state hasn’t shared an formal dedication.

Now, here is a breakdown of the position in pending states.

Arkansas: Most likely taxable 

While the Arkansas Division of Finance and Administration hasn’t issued a formal final decision, a determination might get there in the coming days, a spokesperson explained to CNBC.

Nonetheless, the point out will not conform to the federal code “in any major way,” according to the Tax Foundation, producing forgiven student credit card debt probable to be taxable without having point out action.

California: Potentially taxable

California may well also tax college student personal loan forgiveness, depending on how the Office of Education administers the plan, a spokesperson from the state’s Franchise Tax Board explained to CNBC.

Massachusetts: Very likely not taxable  

When the Massachusetts Division of Revenue has not created a ultimate perseverance, condition Rep. Steve Owens, a Democrat, said in a tweet that scholar loan forgiveness will never be taxable.

What is actually more, the state has already issued direction on conforming to the American Rescue Plan’s exclusion, Owens explained in a different tweet.  

Mississippi: Taxable 

The Mississippi Section of Earnings has confirmed with CNBC that college student bank loan forgiveness will be taxable at the point out stage.

North Carolina: Taxable 

University student bank loan forgiveness is “now regarded taxable revenue,” according to a news launch from the North Carolina Division of Profits. Having said that, the office is monitoring laws modifications from the state’s Common Assembly.

Wisconsin: Perhaps taxable

With the condition tax law conforming in advance of the American Rescue Strategy Act, it is really possible Wisconsin may perhaps tax student loan forgiveness, according to the Tax Foundation.

Tax-absolutely free forgiveness will call for a statutory transform and motion from the condition legislature, a spokesperson for the Wisconsin Section of Revenue advised CNBC.

“We will unquestionably tackle this discrepancy with federal legislation in our upcoming biennial spending budget request in an work to make certain Wisconsin taxpayers you should not encounter penalties and improved taxes for getting their financial loans forgiven,” they said. 

Will Ohio tax canceled student loan debt?

Will Ohio tax canceled student loan debt?

COLUMBUS, Ohio (WCMH) — Ohioans with lately canceled federal university student financial loans won’t see their credit card debt be taxed, at the very least for now.

Following President Joe Biden announced up to $20,000 in college student financial debt relief for up to 43 million debtors in August, states including Indiana stated North Carolina mentioned they would take into account canceled student financial loans as taxable income. Latest Ohio law, having said that, bars the state from taxing “this kind of money windfall,” in accordance to a spokesperson for Gov. Mike DeWine.

“I never assume there would be any desire in the Senate to tax something like that,” explained Condition Sen. Steve Huffman (R-Tipp Town), who is backing a monthly bill to repeal the state’s own cash flow tax.

Forgiven student financial loans will not be matter to a federal revenue tax, both, simply because the American Rescue Approach Act of 2021 produced pupil financial loan personal debt tax-cost-free right up until 2025, according to a simple fact sheet from the White Dwelling.

Who qualifies underneath Biden’s credit card debt reduction approach?

Less than Biden’s personal debt cancelation plan, the Section of Schooling is anticipated to shell out an estimated $500 billion for up to 43 million borrowers across the U.S.

  • $10,000 in personal debt relief to non-Pell Grant recipients
  • $20,000 in personal debt aid to Pell Grant recipients
  • Debtors ought to make considerably less than $125,000 in personal earnings, or $250,000 for married partners, to qualify

Though Biden contends the strategy will battle “the economic harms of the pandemic,” Logan Kolas, financial coverage analyst at The Buckeye Institute in Columbus mentioned he has a quantity of reservations with canceling college student credit card debt.

No. 1, it is highly-priced, Kolas explained. The $500 billion approximated price tag tag, according to the Committee for a Dependable Federal Budget, “would wholly wipe out” the outcomes of Biden’s Inflation Reduction Act over 10 many years, Kolas reported.

Canceling credit card debt could generate impacted debtors and future students to take on riskier financial debt in the future, he mentioned, and dishing out dollars to graduates who will probable generate much larger salaries than their non-higher education-educated friends raises the issue of fairness.

“You’re inquiring individuals who under no circumstances went to higher education … to subsidize individuals people today who are envisioned to make a lot more money in the long run,” Kolas claimed.

But Piet van Lier, a senior researcher at Coverage Issues Ohio, referred to as Biden’s credit card debt cancelation a earn for Ohio — where 15{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the populace, or 1.7 million individuals, have university student loans — and for these bogged down by financial debt payments who or else could be stimulating the economic system.

The common borrower in Ohio owes $34,923 of college student mortgage credit card debt, according to the Ohio Section of Instruction. Black and brown borrowers, who van Lier explained on regular get for a longer time to fork out off their debt in total, will particularly advantage from Biden’s plan.

“It will aid a ton of people get earlier the stress of personal debt that’s holding them back again and keeping our overall economy back, as people debtors have to fork out into a financial debt assistance as opposed to a house or their kid’s instruction,” van Lier said.

How could taxing university student financial loan personal debt effect Ohio?

Failing to take into consideration scholar financial loan financial debt as taxable revenue, Kolas reported, suggests fewer revenue gains for Ohio, which produced approximately $11 billion from the state income tax in 2021, according to the Ohio Section of Taxation.

Ohio may well recoup some of the losses from enhanced gross sales tax income — since Ohioans with canceled personal debt will have a lot more funds to invest — but Kolas reported the massive federal paying out demanded less than Biden’s prepare will increase inflation and taxes regardless of regardless of whether canceled personal debt is taxed.

“It’s poorly mistimed plan,” he claimed.

The tax earnings that Ohio would crank out on taxing college student bank loan financial debt tax canceled scholar financial loans would quantity to “nickels and dimes,” van Lier reported, and is not a plan really worth pursuing.

In Indiana, for occasion, the state’s tax amount is 3.23{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, indicating these suitable for $10,000 in relief will fork out $323 in taxes, in accordance to the Linked Press. Pell Grant recipients awarded $20,000 in aid could owe $646.

In its place of imposing an extra tax on debtors who make considerably less than $150,000 a yr, van Lier explained the Buckeye Condition should really reconsider dishing out what Plan Issues Ohio discovered to be just about $10 billion in once-a-year tax breaks that it awards to huge companies.

“Going following persons who have experienced some student loan personal debt canceled is not excellent coverage,” van Lier claimed. “Any positive aspects of bank loan cancelation are likely to be shed for the reason that you’re making an attempt to tax men and women who are currently battling.”

How student loan forgiveness could impact your credit score

How student loan forgiveness could impact your credit score

Chaay_tee | Istock | Getty Photos

University student credit card debt can make it tougher for people today to start out a organization or purchase a residence — and a person reason for that is that creditors acquire into account your present monetary obligations.

Now that President Joe Biden has declared he designs to cancel up to $20,000 for tens of millions of student loan debtors, a lot of men and women will locate on their own with a additional favorable stability sheet and maybe, a boosted credit score.

linked investing news

The housing tech revolution boosted by the pandemic continues even as market cools. How to play it

CNBC Pro
The housing tech revolution boosted by the pandemic carries on even as sector cools. How to enjoy it

Biden said in late August that most federal student loan borrowers will be suitable for some forgiveness: up to $10,000 if they didn’t receive a Pell Grant, which is a kind of help offered to very low-income undergraduate learners, and up to $20,000 if they did. In the meantime, other modern modifications coming for student loan debtors, such as a 2nd possibility for those who experienced defaulted on their loans, may go away them in an even better economic predicament.

A lot more from Individual Finance:
What Biden’s student loan forgiveness implies for your taxes
Do you make far too a lot for student financial loan forgiveness?
Scholar personal loan forgiveness applications could open up in months

Here’s what it all could mean for your credit rating.

Never expect a ‘huge’ effect on your credit history rating

Scholar loan forgiveness will possibly have a modest effects on your credit rating rating, stated Ted Rossman, a senior sector analyst at CreditCards.com.

“I really don’t think it will be large,” Rossman reported.

Which is since scholar loans are viewed as “installment financial loans,” indicating a financial loan you repay about a established period of time of time with often scheduled payments. Those people aren’t weighted to closely into your credit score utilization level, which is how a great deal you are working with of the credit rating out there to you, he spelled out. Your utilization fee can account for up to 30{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of your rating.

Even now, any score improve may support you get more favorable conditions with other loan companies.

President Biden announces student loan debt relief plan

Fewer financial debt may support you qualify to borrow much more

Owing less on your student loans will boost your “credit card debt-to-earnings ratio,” which is the share of your every month money used to shell out your current money owed.

Loan providers search at this ratio when deciding how considerably to permit you borrow. Some use a little something identified as the 28/36 rule, which specifies that no far more than 28{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of your month-to-month gross cash flow go toward housing costs, and no much more than 36{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} go toward complete money owed. (A handful of property finance loan lenders have even greater caps.)

Forgiveness that cuts down or even eliminates your every month college student loan payments could lessen that ratio, “possibly serving to you qualify for a more substantial mortgage loan, vehicle mortgage or credit rating card restrict,” Rossman said.

Credit report variations could take months following applying

Now, the U.S. Section of Education is declaring the application for mortgage cancellation will be accessible by early October, and that borrowers could see the relief in just 6 weeks.

Debtors can then assume to see their lowered or erased personal debt on their credit history reviews within about a few months, Rossman claimed.

Owing less will assist you make much more headway with paying down credit rating card credit card debt, boosting your cost savings and investments.

Ted Rossman

senior business analyst at CreditCards.com

He endorses you check your report regularly for cost-free at AnnualCreditReport.com to make absolutely sure all a few credit score score companies — Experian, Equifax and TransUnion — are exhibiting your correct stability. You can check your credit history report weekly for free of charge through the end of 2022.

Make sure you conserve a file of your lessened debt from your university student mortgage servicer in situation you need to have it as proof.

Borrowers in default have a probability to obvious their document

The Training Division has also lately declared that it will be encouraging some 7 million pupil financial loan borrowers out of their defaulted standing.

As soon as the so-called “Fresh new Get started” software launches, debtors will start off by picking out a repayment system at MyEdDebt.Ed.Gov or by calling the Training Department’s Default Resolution Group at 800-621-3115, stated higher education and learning specialist Mark Kantrowitz.

Spxchrome | E+ | Getty Illustrations or photos

Your loans should then be transferred from the servicer that handles defaulted federal scholar financial loans, Maximus, to a new servicer. After you have a new servicer and are enrolled in a payment strategy, the default ought to be immediately cleared from your record, Kantrowitz explained.

The possibility is non permanent. Debtors will have a 1-yr window to swap into a new reimbursement program, starting up when the Covid-19 suspension of payments concludes. That is at present set to materialize Dec. 31.

New payment programs could assistance borrowers’ credit score, much too

Alongside with President Joe Biden’s announcement very last week on student financial loan forgiveness, he claimed the Training Department was shifting to offer borrowers with undergraduate loans a new cash flow-driven repayment system that could slash their regular monthly costs in half. The strategy could lessen the common once-a-year college student bank loan payment by more than $1,000, in accordance to the White Household.

Kantrowitz claimed this could have “a major impact on home loan underwriting,” considering the fact that the other every month economical obligations you have are a substantial thing to consider for lenders.

The plan isn’t readily available to debtors still but they should really continue to keep examining for updates.

You can also acquire advantage of a decreased or eradicated regular pupil mortgage payment to advance on your other money aims, Rossman said.

“Owing a lot less will help you make a lot more headway with paying down credit history card credit card debt, boosting your financial savings and investments,” he reported.

Don’t want the government forgiving student loans? Then your church should.

Don’t want the government forgiving student loans? Then your church should.

(RNS) — I test to steer clear of mentioning I’m a pastor when I satisfy new individuals mainly because the conversations straight away get unusual. I knowledgeable 1 these types of awkward turn whilst on trip with my loved ones and sharing a pool with a woman in her 70s executing h2o aerobics. Right after learning about my career she started lamenting the absence of her grandchildren in church ahead of pivoting to her hope of a political applicant reclaiming America for God.

The want for our more youthful family members customers to share our religion convictions and beliefs is typical. Sadly, the drive for our convictions and beliefs to control modern society is also predictably standard.

In Luke’s account of the announcement and beginning of John the Baptist, the angel Gabriel told John’s father, Zechariah, the information currently being supplied as a result of John would “turn the hearts of the fathers towards their youngsters.” When John commenced preaching and getting ready people today to behold Jesus he informed individuals with two coats to give to the types who had none and to do the identical with their food. He referred to this function as a way of “producing fruit in preserving with repentance.” The Very first Nations Version of the New Testament states, “When the persons read these phrases, they began to have hope.”

I simply cannot say I was shocked when I read the backlash toward the news of very last week’s announcement of the forgiveness of university student personal loan credit card debt.

I was raised in a custom that praised the virtue of neighbors caring for neighbors — and thought they could do so in approaches the federal federal government couldn’t maybe replicate. It was in that spirit that the church wherever I provide introduced an initiative in 2020 called the Equitable Therapeutic Reparations Initiative. The aim of the function was to pay out off student personal loan credit card debt for Black therapists in buy to chip away at disparities that exist in mental health obtain and care as perfectly as an increasing prosperity hole amongst Black and white People in america.

I had lately heard Jemar Tisby lecture on his e book “The Shade of Compromise: The Truth About the American Church’s Complicity in Racism.” Through the lecture he elaborated on some of the realities that challenge Black illustration and accessibility to mental well being treatment and the want for mend in techniques perpetuating all those problems. He also advised fiscal reparations as a way for dominant society American churches to repent for the inequities their establishments served generate and maintain.

Putting these concepts with each other, we designed our initiative and in excess of the previous two a long time extra than 100 people today from 12 states (and a single good Canadian) have specified a lot more than $84,000 to the payment of personal loan debt for Black therapists. Our small, small price range church has also fully commited to giving month to month to the restore of these damaged techniques and has offered $18,000 to the initiative —putting the total at just in excess of $100,000. One particular therapist’s personal loan personal debt was fully paid and we’re on the way to shelling out off another’s. We are also nearing the start of a Black-led foundation that will continue on and increase this do the job.

Just one unpredicted fruit of this hard work was that more youthful folks — quite a few who experienced remaining the church or Christianity entirely — ended up loaded with hope at the believed of a church moving in fiscal repentance towards a more equitable culture. Hearts of grandparents, fathers and mothers were being waking up to the tricky realities of a younger generation of students. Numerous persons in their 20s and 30s told me it was the 1st time they felt good about giving money to a church. Fruit grew for the reason that of repentance.

If your explanation for opposition to past week’s debt reduction method is due to the fact it is coming from the federal governing administration, I’d like to provide this method as a way for you to enter into the get the job done of proclaiming a kingdom the place there is no debt and everyone is well prepared to flourish. If you feel the most effective way for this to transpire is for neighbors to care for neighbors, why not have your church start shelling out off financial loan debt for neighbors who have been crushed by predatory lending and unsustainable expenditures of continuing schooling?

I never know if my young children will believe that what I think about Jesus, but I’m convinced that if they do it will have more to do with institutional repentance than institutional certainty. I imagine that was the key component John the Baptist was supplying to individuals who collected all around him and began to have hope.

The woman in the pool with me that day certainly needed her young children and grandchildren to experience a God who knew them and cherished them. She ached for them to need that adore, but the programs she had invested time and cash into weren’t persuasive them toward her eyesight for their world.

Jesus spoke these words when rebuking people who thought of on their own small children of the mild who sought security and ease and comfort in their cash and possessions: “The children of this planet are more shrewd in dealing with their have technology than are the small children of the light-weight.” Previous week, the United States governing administration offered a additional hopeful gospel proclamation to these beneath the body weight of financial debt than has been supplied by a great deal of what is called the church.

For as long as I can remember I have listened to older Christians connect with for revival. For them, revival intended all those who don’t imagine coming into agreement with us and our establishments. I have nevertheless to see this sort of an celebration consider place, but I speculate … what if all the dollars aimed at territorial enlargement and church planting was aimed as a substitute at financial debt reduction and racial justice?

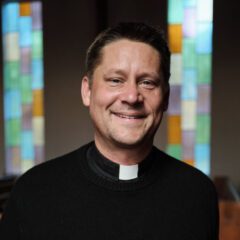
The Rev. Danny Bryant. Courtesy photo

The Rev. Danny Bryant. Courtesy photograph

Could this sort of an act fill persons with hope and put together hearts for the just reconciliation provided in the physique of Jesus?

(Danny Bryant serves as the priest of St. Mary of Bethany Parish in Nashville, Tennessee. The sights expressed in this commentary do not essentially mirror those of Faith News Services.) 

Should You Ask for a Refund on Student Loan Payments?

Should You Ask for a Refund on Student Loan Payments?

Hundreds of 1000’s of debtors manufactured payments on their federal scholar financial loans considering that forbearance commenced in March 2020, having gain of the option to spend down their balances.

Now that the White Home has announced strategies to terminate up to $20,000 in college student bank loan financial debt, some of all those borrowers may perhaps be wondering how to get a refund. The strategy is that a refund of college student mortgage payments could put funds in borrowers’ pockets and optimize the quantity of canceled financial debt — but that may not be the best notion for everybody.

Here’s what you want to know.

Who can request a refund?

A lot more than 40 million borrowers had been permitted to pause their payments, curiosity-totally free, for the duration of the pandemic. The White House states up to 27 million folks may perhaps be qualified for personal debt cancellation.

These who designed payments or paid out off their federally held financial loans for the duration of the interest-cost-free forbearance — by one payment or lump sum — are eligible for refunds. Any payment produced considering the fact that March 13, 2020, is qualified.

Private scholar bank loan payments aren’t bundled. Neither are payments produced on some FFELP or Perkins financial loans.

Who ought to request a refund?

Capable debtors who have loan balances significantly less than their maximum cancellation volume — $10,000, or $20,000 if you recognized a Pell Grant — and have created at least a person payment through the pause could be hurrying to request a refund to be certain they get the most reduction probable.

Nevertheless, only borrowers suffering from monetary hardship need to request a payment refund at this time, suggests Scott Buchanan, executive director of the University student Loan Servicing Alliance.

Buchanan says that because whole specifics of the personal loan cancellation plan have not however been released, borrowers just cannot be positive they’ll in fact reward from receiving a refund on payments made at {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} curiosity.

Just as the cutoff for cancellation-suitable financial loans is set for individuals disbursed before July 2022, Buchanan warns debtors that the Schooling Office may perhaps determine to cancel financial debt centered on a stability at a date in the earlier as very well. In that scenario, any refunded payments will not assist borrowers improve their cancellation amount.

“What I get worried about is people likely using income out, investing it on something and then it doesn’t implement,” Buchanan says.

He advises debtors to signal up for updates with the Training Section for official details on when to request a refund — and irrespective of whether it will even be useful.

How do I request a refund?

Starting up the process for obtaining a refund on payments is rather easy if you have the right information useful. You need to have:

  • Your personal loan servicer’s cell phone range.

  • Your Social Protection selection.

  • Payment confirmation quantities or financial institution payment information.

  • The tackle exactly where you want your refund sent.

You can likely come across payment confirmation quantities on your loan servicer account portal underneath your payment background. Every single payment has a special identification amount that will permit the servicer consultant to implement your refund precisely. You can discover your lender transaction dates or check numbers on your lender account portal.

The initial move is to phone your bank loan servicer. Your bank loan servicer representative could check with for your Social Safety number to pull up your account. Right after they verify your account and identity, permit them know you want to ask for a refund on payments designed for the duration of the curiosity-absolutely free forbearance period.

Count on long keep instances, Buchanan claims.

The consultant will question you which payments, especially, you want refunded. To make this go promptly and effortlessly, be well prepared to deliver them with the relevant payment confirmation figures or transaction quantities.

You will also need to confirm your deal with on file: Refunds could occur via examine or electronically.

Then, the consultant will submit the request on your behalf and provide you with a confirmation.

When will I get my money back?

If you do not get your refund electronically, you will obtain a check out in 6 to 12 weeks. You will also see your financial loan balance raise by your refunded amount of money in that time frame.

Democratic hopefuls steer clear of Biden student loan plan

Democratic hopefuls steer clear of Biden student loan plan

A number of Democratic candidates in tough Senate races are treading diligently when it comes to President Biden’s final decision to terminate scholar financial loans for tens of millions of debtors, with some distancing themselves from the new White House plan that has quickly grew to become a main campaign difficulty. 

The lengthy-awaited transfer to forgive $10,000 in federal student personal debt was geared toward gaining guidance from young folks and functioning Us residents just a few months out from the midterms. But some Democrats in closely watched Senate races that will aid determine regulate of the chamber have criticized Biden’s policy for not currently being focused more than enough and not addressing underlying issues.

“Student bank loan forgiveness is found by some as a cultural war — the elites with levels who are on their route to financial security compared to those who did not attend school and are working their butts off every single day to make finishes satisfy,” said Debra Dixon, previous chief of personnel at the Business office of Preparing, Evaluation and Plan Enhancement at the Section of Training underneath President Obama.

“By supporting the notion frequently, but not wholeheartedly, the senators can attempt not to alienate the beneficiaries of the student bank loan forgiveness or these who do not have college student loans to forgive,” she explained.

Rep. Tim Ryan (D-Ohio), who is joining Biden at an celebration next thirty day period in the Buckeye Condition, stated on Sunday he supports a broader package deal of credit card debt aid and a tax reduce “for all operating people” over the scholar mortgage forgiveness approach.

Sen. Michael Bennet (D-Colo.), who is going through a harder-than-envisioned reelection bid, criticized the university student mortgage forgiveness approach for not becoming targeted more than enough and offering just one-time cancellation as opposed to solving broader troubles.

Meanwhile, other candidates, which include incumbent Sen. Mark Kelly (D-Ariz.) and North Carolina Democrat Cheri Beasley, supported the system. Kelly has a 3-place direct in his race versus GOP challenger Blake Masters, in accordance to a poll released on Tuesday, and Beasley has been tied with Rep. Ted Budd (R-N.C.) in the race for North Carolina’s open up Senate seat.

“In this circumstance, in distinct, I assume Democrats are yelling about the locations we do concur and we obtain ourselves politically whispering about the places that we disagree,” mentioned Democratic strategist Antjuan Seawright. “I assume which is safe. I believe it’s healthier.”

Ivan Zapien, a lobbyist and former Democratic Countrywide Committee official, stated that an election where the president is not on the ballot makes it possible for room for candidates to have their have guidelines that might be diverse from what is coming out of the White Home.

“That’s the theory of the scenario for Democrats. We’re gonna uncover out whether it is effective out or not. But, in theory, that is what Democrats are likely for,” Zapien claimed. “Every district and each and every state is going to take a distinctive strategy, and that’s Alright.”

Biden fulfilled his 2020 presidential marketing campaign promise by forgiving $10,000 in federal college student loans for all debtors. In what is noticed largely as a nod to progressives, he also forgave $20,000 for Pell Grant recipients.

Some progressive candidates want a lot more.

Sen. Raphael Warnock (D-Ga.), who is a bit trailing behind his GOP challenger Herschel Walker in a recent poll, has been urgent Biden for months for forgiveness of $50,000 per borrower. In the meantime, Pennsylvania Democratic Senate candidate John Fetterman, who is joining Biden at an event on Monday, termed the relief only a to start with stage and argued that individuals who did not go to higher education need to be supported much too.

Seawright argued, although, that Democrats who do not align with Biden’s exact forgiveness plan do not essentially disagree about the broader issue it is effective to remedy.

“I don’t obtain into this and that there is some controversy since they really do not agree 100 p.c with all the things the president may have carried out by way of his executive orders,” he reported. “The real truth of the make any difference is they’re in lockstep arrangement that some thing needs to be accomplished and the way we do that is by the elected legislative department and the government branch working together.”

Republicans have aggressively leaned into appealing to operating People who did not go to college when bashing Biden’s coverage. They have referred to as the prepare unfair and pushed that it is being paid for by taxpayers.

The approach also arrives as the U.S. is going through 40-year superior inflation, which was already set to be a top concern for Individuals in the midterms, with the cost of gas and groceries however substantial. 

Blue-collar staff total are a demographic Democrats stress they could reduce to the GOP in the midterms, and Biden is betting the sufficient individuals will guidance the forgiveness approach, especially in minority communities, to ward off these hits from Republicans.

“This is heading to have continued vibration all through the political ecosystem, each downstream and upstream. I believe it’s a serious prospect for Democrats to make the distinction concerning what we have accomplished and what we’ve available and what [Republicans] have not completed and what they have not provided,” Seawright said.

The president mulled his selection on university student loans for far more than a year, with advocates and Democrats pushing for wide-centered forgiveness and the president expressing continuously he would make a decision before long. 

The historical selection to put into practice the most significantly-achieving university student loan forgiveness application ever was sooner or later designed just three months out from November, in the heat of a midterm election that is essential for Democrats searching to keep on to command of the Senate.

“The timing in all probability was affected by politics, but, in one thing like this, I do not feel there’s ever a fantastic time to do it,” Zapien reported. “Obviously, folks that weighed the repercussions and walk through the politics of this, I never imagine anyone’s stunned with the combined reactions. Persons realized what they ended up finding into.”