Meet a Millennial With $250K in Student Debt 13 Years After Graduating

Meet a Millennial With $250K in Student Debt 13 Years After Graduating
  • Janell Tryon owes extra than $250,000 in pupil personal debt. 
  • $100,000 of that is from curiosity, even with 13 many years of payments.
  • She says that accruing desire on her initial financial loans created it unfeasible for her to pay back off her financial debt.

At age 34, Janell Tryon owes $250,000 in student financial debt.

She only took out $150,000 of it — $100,000 for an undergraduate diploma at New York College, and $50,000 for a masters degree in general public overall health.

The relaxation is all curiosity.

“For a long time, I could not deliver myself to glance at the figures and I felt absolutely out of manage,” she explained to Insider. “The only way I could are living with it was by shelling out a specific volume every single thirty day period and not defaulting. I never felt like I could get a manage on it.” 

In the 13 years since she graduated from NYU, Tryon has been building payments on her loans, though emotion unequipped to manage the financial debt load. Soon after graduating, she manufactured $23,000 a year as a manager at a bookstore cafe, and was spending $700 a thirty day period on her loans — the identical total as her rent. Immediately after graduate faculty, she expended five decades performing research for the San Francisco and New York Town wellness departments, talking to citizens about their experiences with habit and homelessness. Now, she’s a complete-time PhD student at the University of Massachusetts Amherst. 

During all this time, her regular payments usually went towards fascination, not the principal amount of the mortgage. It can be a vicious cycle, as the financial loan just keeps gathering additional interest, which will have to be paid out off that thirty day period.

Tryon’s story is similar to that of numerous Us residents, 45 million of whom have college student-bank loan credit card debt — that is 1 in 8, in accordance to a NerdWallet investigation of Could 2021 census data. Those concerning the ages 25 and 34 are the most very likely to keep student-loan financial debt, and millennials owe an normal of $40,000, according to facts from a 2021 Experian examine

Given that March 2020, the debtors who owe the federal authorities have not been necessary to make college student-bank loan payments and have not been billed new interest, but strain is growing for President Joe Biden to cancel some or all of that personal debt. Biden is reportedly gearing up to terminate $10,000 for those people producing under $150,000 per 12 months, The Washington Submit described this week, while the normal borrower owes nearly 3 times that, according to an Experian review. 

“A whole lot of these pupils are coming from family members like mine, who didn’t know how to navigate college student personal debt because it is really its own beast,” Tryon instructed Insider. 

‘It’s a genuinely insidious process’

Like a lot of Americans, Tryon owes a combine of personal and federal credit card debt.

Her federal loans had been managed by Navient ahead of Aidvantage took in excess of their portfolio. Tryon’s non-public credit card debt is managed by banks and other lending teams, and all of her financial loans have a variety of interest costs amongst 4.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and 11.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

In January, Navient — previously regarded as Sallie Mae — settled a lawsuit that claimed the business pushed student-mortgage borrowers into more personal debt in its place of serving to them establish inexpensive compensation ideas. Navient denied any claims of wrongdoing in the agreement, but agreed to cancel $1.7 billion in university student financial loan financial debt for 66,000 debtors out of the $73 billion in college student loans it expert services. 

Tryon’s debt wasn’t eligible. To qualify, borrowers will have to have experienced 7 consecutive months of delinquent payments or have attended for-income educational institutions. 

Tryon identified as the settlement “a major distraction,” from all the persons still trapped with their personal debt. 

She imagined that by likely to university, she would inevitably make enough dollars to preserve up with the credit card debt she took on.

She stated that she expended decades attempting to negotiate a payment system with Navient and at some point went into forbearance, which means that she paused payments on her original bank loan even though only spending curiosity. With this setup, a borrower ordinarily ends up shelling out extra in the extended operate. 

“It was never about ‘how a lot can we make this individual pay back that is realistic for what she makes?'” she mentioned. “It was, ‘how a lot can we reduced the level so that she can make an fascination-based mostly payment, not a basic principle-based mostly payment?'” 

That was 1 of the statements of the Navient lawsuit — in a assertion, Pennsylvania Legal professional Basic Josh Shapiro claimed that the company “engaged in misleading and abusive techniques, focused students who it understood would battle to spend financial loans again, and put an unfair stress on individuals trying to make improvements to their lives by training.” 

Scholar-mortgage skilled Mark Kantrowitz, founder of privatestudentloans.guru, a cost-free web-site about borrowing to shell out for college or university, explained to Insider that he thinks the most significant allegation in the lawsuit is that Navient dispersed financial loans that would lure borrowers in a cycle of credit card debt in buy to financial gain off of interest. 

Sallie Mae distributed “option cost loans” ahead of they were inherited by Navient, loans that “ended up designed recognizing that the vast majority of borrowers would be not able to repay the personal debt,” he reported. 

Navient has earlier denied all claims, and advised Insider that they give many distinct selections for debtors hunting to pay down their financial loans. 

“The company’s conclusion to take care of these issues, which had been based mostly on unfounded claims, permits us to stay clear of the further stress, price, time and distraction to prevail in court docket,” reported Navient’s Chief Legal Officer Mark Heleen. “Navient is and has been regularly centered on helping scholar personal loan debtors fully grasp and decide on the suitable payment options to healthy their wants. In fact, we have pushed up income-driven repayment approach enrollment and driven down default fees, and just about every yr, hundreds of 1000’s of borrowers we help efficiently shell out off their student financial loans.”

In the decades considering the fact that she’s graduated higher education, Tryon suggests that her debt has held her back from preparing for the potential. Since becoming a member of Credit card debt Collective, a union for debtors, she mentioned she’s satisfied other people like her who come to feel misled by loan providers and educational facilities. 

“It can be taken me yrs to learn how manipulated I was by loan companies,” she reported. “It is a definitely insidious method.” 

Tryon added that although a faculty diploma frequently signifies financial mobility for people who grew up in minimal-income homes, the resulting debt debilitates folks for years. 

“The technique might want us to aspire to be in a different


tax bracket

,” she stated, “but if we are in this financial debt, we are so significantly worse off than our moms and dads.”

NJ college graduate pays off $70K in student loans by starting used book business

NJ college graduate pays off $70K in student loans by starting used book business

NEWYou can now hear to Fox News articles!

When President Biden has floated the plan of canceling “some” pupil bank loan personal debt — an idea both equally GOP and Democrat lawmakers alike are alarmed by, declaring it would price tag the authorities as well a lot cash and incorporate to inflation — some college graduates with hefty debt financial loans aren’t waiting around for a person or a thing to bail them out. 

They are pushing ahead, carrying out what is actually appropriate — and figuring out a way to pay back off their have debt. 

And for 1 Rutgers University graduate, that concerned a novel concept. 

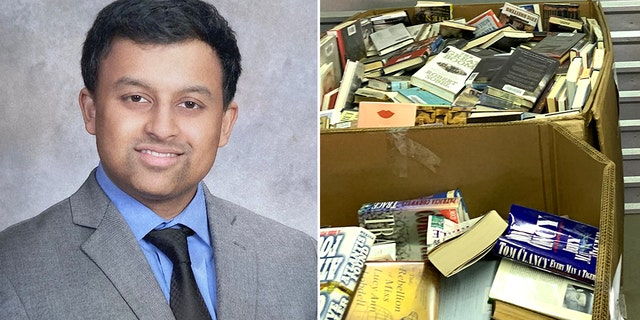
New Jersey native Pathik Oza graduated in 2018 with a B.A. from Rutgers College — he analyzed psychology and biology — with $70,000 in pupil financial loans, he told Fox Information Digital in an job interview.

OHIO Few, Moms and dads OF TWO, GET Large Scholar Mortgage Credit card debt Guiding THEM

And even though Oza began pursuing one more diploma ahead of his approach to go to health care school, he also identified a passion for rehoming made use of and discarded guides.

“I was strolling around one working day throughout the summer months, and I observed textbooks lying there, and I assumed there would be an option,” he said. 

O3 Books founder Pathik Oza of North Brunswick, N.J., during a recent Zoom interview with Fox News Digital about paying down his student debt. "I just started this volunteer work where I would collect unwanted books," he said. 

O3 Textbooks founder Pathik Oza of North Brunswick, N.J., in the course of a new Zoom interview with Fox Information Electronic about having to pay down his scholar credit card debt. “I just started off this volunteer do the job where by I would acquire undesired guides,” he claimed. 
(Fox Information Electronic)

“Why would textbooks be thrown absent? They could be redistributed to someone who may well want them. So I just started off this volunteer perform exactly where I would gather undesired publications,” he told Fox Information Digital.

What commenced as a variety gesture and a prospect to give back to area libraries, schools, shelters and children’s hospitals turned into a sparkling new enterprise possibility. 

An expanding range of requests for publications and a significant need for his providers grew to become a little something significantly too substantial for just Oza and his Toyota RAV4 to deal with. 

Pathik Oza designed the selection to flip reselling books into a successful business enterprise.

So Oza built the decision to change reselling publications into a enterprise. He commenced off by opening an Amazon account. 

He termed his enterprise O3 Guides.

FLORIDA-Primarily based Mom PAYS OFF $40K IN Student Debt Immediately after Dwelling ‘PAYCHECK TO PAYCHECK’

“The gain would maintain coming in, and it stored rising,” he said. “[In about] a month or so, I experienced all around 1,000 to 2,000 textbooks in Amazon warehouses. So it was rather awesome to see the expansion in the organization.”

Oza ongoing to develop by launching a web page and opening an Etsy shop, which “blew up” when the planet was locked down for the duration of the coronavirus pandemic. 

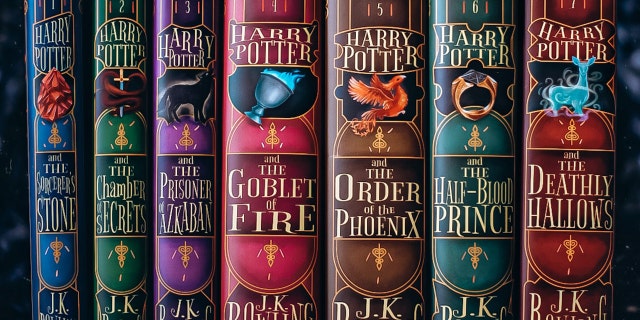
O3 Books' original dust jacket designs for J.K. Rowling's "Harry Potter" book series are shown here. (Pathik Oza/O3 Books)

O3 Books’ unique dust jacket models for J.K. Rowling’s “Harry Potter” book series are proven here. (Pathik Oza/O3 Guides)

He also identified that there was especially superior demand for his décor e-book sets and redesigned dust jackets he moved in that course to assistance spruce up the backgrounds of function-from-dwelling Zoom meetings.

By the end of 2020, Oza had created $115,000 from his facet enterprise — which lined his scholar financial loans in complete, and then some.

Oza figured out “a ton about finances,” he reported, by paying out off his loans and by fueling his very own smaller enterprise at the similar time.

Oza claimed he learned “a great deal about finances” by spending off his financial loans and by fueling his personal business at the similar time.

OHIO Author Paid out OFF $48K IN Scholar Financial loans IN 14 MONTHS: IT WAS ‘AN ADVENTURE’

Today, the 25-12 months-outdated stated he would truly feel “more cozy” getting on different sorts of borrowing in the potential centered on the economical know-how he’s accrued.

The achievements of O3 Books is now having to pay for Oza’s next diploma in total, doing away with the burden of needing to get out another personal loan. 

Pathik Oza of N.J. started O3 Books — and used the money he made from his new business to completely pay off his student loan debt. 

Pathik Oza of N.J. began O3 Guides — and utilised the funds he created from his new business to wholly shell out off his pupil personal loan credit card debt. 
(Pathik Oza)

The modest business enterprise proprietor has considering the fact that switched career paths. 

He is been pursuing a degree in personal computer science, though the assumed of hefty med school financial loans maybe in his long run gave him an further raise to consider treatment of debt he previously had.

“I felt it was urgent to pay people off,” he mentioned.

HOW TO Come to a decision WHICH Pupil Financial loans TO Fork out OFF Initial

For other pupils with personal debt who are seeking for a way to pay down their loans, Oza mentioned weighing the alternative of starting a little enterprise is a fantastic thought. He particularly encouraged using gain of on-line marketplaces like Amazon and Etsy.

“Any enthusiasm you’ve started off, there is undoubtedly a industry for it,” he said.

“You only will need a compact part [of the population] to [help] produce income in product sales. As extensive as you have 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the buyers, you have a whole-fledged business,” he included. “There is generally a market for anything.”

Expanding his own small business has supplied Oza a boost in terms of monetary literacy, so he also suggested that saving and investing one’s money is usually the “very best option.”

ROWE: Idea OF CANCELING Pupil Financial loan Personal debt ‘MAKES ME CRAZY’

“Make positive to understand finances and how you can greatest allocate your income,” he explained. “Loans are a stress no one would like — but you will get rid of them.”

O3 Books founder Pathik Oza shared ideas for other students with debt to pay down their loans. "Social media has opened up many opportunities to market your skills and allow you to create a side or potentially full-time income," he said.

O3 Textbooks founder Pathik Oza shared concepts for other pupils with debt to pay out down their loans. “Social media has opened up numerous prospects to industry your skills and make it possible for you to develop a side or possibly full-time revenue,” he mentioned.
(Pathik Oza)

Oza hopes one day to depart O3 Publications with his parents — as a continual outlet for supplemental money. In other terms, he desires it to keep in the family.

“This is an incredible side money I’ll keep endlessly,” he reported. “I built a model all over it. I developed a neighborhood close to it. So, it’s a little something I simply cannot allow go.”

“There is a market for your talent and there are numerous platforms you can use to showcase your skill.”

Oza also shared added tips for any individual needing excess earnings or cash to pay out down their scholar personal debt.

“I would suggest obtaining a section-time task — and if you do not have that much time, then use all those accessible several hours to make funds with a ability you have,” he mentioned. 

Click on Below TO Sign UP FOR OUR Lifestyle Publication 

“It could be nearly anything like advertising and marketing, art, world wide web design and style, application improvement or training … There is a industry for your expertise and there are a lot of platforms you can use to showcase your ability.”

“For example,” he added, “Instagram is an superb place for artists to showcase their artwork … The greatest section about this is you can operate when you are accessible.” 

Click on In this article TO GET THE FOX Information Application

Claimed Oza, “Social media has opened up quite a few possibilities to current market your expertise and allow you to create a facet or probably total-time revenue from a passion or talent you have. Once again, if your circumstance lets you to do this, consider to decrease your investing charges as substantially as achievable.”

Interest rates on new federal student loans going up for 2022-23

Interest rates on new federal student loans going up for 2022-23

Two years ago, federal pupil mortgage debtors appreciated the lowest desire costs at any time on their loans. This drop, prices for undergraduate debtors will be almost double what they were in 2020-21.

The fascination rates for new undergraduate immediate federal university student financial loans are established to raise to 4.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for the 2022-23 academic year, up from 3.73{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} previous yr and 2.75{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in 2020-21. The fascination prices on graduate direct loans are also set to boost to 6.54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} mum or dad and grad As well as loans will increase to 7.54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Due to the fact the new fascination premiums go into result beginning July 1, any new financial loans taken out ahead of then will have the desire premiums from the 2021-22 educational 12 months.

2021-22 interest fees

2022-23 desire prices

Undergraduate immediate mortgage

3.73{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

4.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Graduate direct bank loan

5.28{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

6.54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Plus mortgage

6.28{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

7.54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Growing rates make college or university far more pricey

Higher interest fees necessarily mean shelling out off loans will be more costly. For a dependent very first-year undergraduate student, a $5,500 personal loan — the maximum this scholar could borrow — will value $6,997 in excess of the conventional 10-calendar year repayment term with an desire fee of 4.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. At the 2020-21 amount of 2.75{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, this bank loan would price $6,297.

People getting on graduate immediate and Plus financial loans will see the cost of borrowing swell even far more. On top rated of larger fascination fees, As well as loans carry an origination charge of 4.23{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and don’t have any borrowing boundaries.

In accordance to the Hechinger Report, a nonprofit centered on instruction concerns, the typical As well as bank loan in 2019 was close to $14,000. That financial loan volume, taken on with the standard 10-12 months phrase and future year’s interest amount of 7.54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, will expense $19,977 more than the life of the loan, like $5,977 in curiosity.

Interest charges for federal college student financial loans are set by the Treasury Department’s May possibly auction of 10-12 months notes. The fascination rate on the May 10-12 months notes, 2.94{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, is extra to margins set by Congress, and these margins differ concerning styles of federal student loans.

For undergraduate immediate financial loans, 2.05 share factors are additional to the curiosity amount graduate scholar financial loans have 3.6 factors added and 4.6 points for As well as financial loans.

Post the FAFSA and think about the payoff

Raises to the federal student personal loan fascination costs make it even far more important to consider the payoff of college and whether or not any personal debt you choose on is really worth it.

Nonetheless, even with enhanced interest premiums, federal college student loans are the very best option to finance your education if you require financial loans. Submit the No cost Application for Federal Student Support, or FAFSA, to be eligible for federal, condition and college-centered assist.

Submitting the FAFSA also lets you to be regarded as for grants and other support you really do not have to repay, these kinds of as the Pell Grant. When you’ve taken edge of any assist you really don’t have to repay, exhaust all of the federal scholar financial loans made available to you prior to opting for personal college student loans. Federal scholar loans offer you more borrower protections.

The payoff of attending college or university will change dependent on your major, the price of attendance and the total of debt that you have to consider on to finance your schooling. If the payoff isn’t obvious for you, take into consideration choices to school or beginning at a community faculty in advance of transferring to a four-year college to attain your bachelor’s degree.

Far more From NerdWallet

Colin Beresford writes for NerdWallet. E-mail: cberesford@nerdwallet.com.

The post Curiosity Premiums on New Federal Student Financial loans Going Up for 2022-23 initially appeared on NerdWallet.

Student loan forgiveness divides Americans more by party and age than by education

Student loan forgiveness divides Americans more by party and age than by education
President Joe Biden introduced last thirty day period that he was weighing options to handle his campaign pledge to relieve college student credit card debt burdens, like a system that would limit the relief to $10,000 for each individual and exclude wealthier debtors. The Biden administration has earlier canceled extra than $18.5 billion of university student debt as a result of current forgiveness programs, in addition to issuing various extensions of the pandemic-period moratorium on college student financial loan payments.
About 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Us residents, 49{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, consider the US federal government is accomplishing also minor to address scholar loan credit card debt, in accordance to a CNN Poll conducted by SSRS in late April and Could, with 24{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} expressing that the governing administration is carrying out far too much, and the remainder that the existing tactic is about right. For comparison, 81{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} say the authorities is getting also very little motion on inflation.

A bulk of Democrats (56{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}) — and an even wider greater part of self-described liberals (69{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}) — say the authorities is accomplishing also minor on scholar mortgage credit card debt, according to the CNN poll, though only a third of Republicans and self-explained conservatives alike say the similar. Seventy {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of older people younger than 35 say the authorities is doing too minor, a determine that drops to 50{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} among individuals in the 35-49 age bracket, and 35{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} among individuals age 50 or more mature.

There are also racial and earnings-primarily based divides: 6 in 10 of persons of color say the government is accomplishing as well small, compared with 42{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of White People who say the same. And 57{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of these in homes producing a lot less than $50,000 each year want to see additional government action, in contrast with 42{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in greater-earning homes.

By distinction, on the other hand, you will find minor divide amongst school graduates and these with no a diploma: 50{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Americans devoid of a college degree say the govt really should acquire far more action on pupil bank loan credit card debt, as do 47{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of university graduates.

Although youthful grown ups are frequently supportive of government action on college student financial debt, their views also diverge alongside political and demographic traces. In a March poll of Us citizens ages 18-29, conducted by the Institute of Politics at Harvard Kennedy University, 38{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of younger older people explained that the govt should terminate student bank loan personal debt for anyone, 21{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} that personal debt should be canceled “only for those most in need to have,” 27{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} that the government really should not terminate money owed but as a substitute assistance with repayment possibilities, and 13{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} that there need to be no improve in authorities plan on the situation.

Around fifty percent of younger Democrats (48{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}) explained the federal government should really terminate all pupil mortgage debt, with 77{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} indicating the authorities ought to terminate personal debt for at the very least some Americans amongst young Republicans, 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} favored canceling all pupil personal loan debt, and 35{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} assumed at minimum some debts ought to be canceled.

Biden is considering canceling some student debt. Here's why it might not be such a great idea

Half of young Black Americans supported thoroughly canceling scholar loan debts, in contrast with 43{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Hispanic younger older people, 38{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of young Asian People and Pacific Islanders and 33{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of White youthful adults. There was once again rather minimal difference involving current university college students (41{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of whom explained all college student bank loan credit card debt really should be canceled), higher education graduates (39{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of whom stated that) and those who neither held a degree nor have been at the moment enrolled (36{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}).

The Harvard poll also identified that when asked about the countrywide concern that anxious them the most, just 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of young grown ups talked about instruction charges or pupil personal debt — 19{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, by contrast, pointed out inflation or the economy as a complete.

Although surveys give a fairly apparent photograph on how Americans divide over college student mortgage plan, they’re a lot less reliable in the amount of in general aid they find for federal government action. You will find a good reason for that — the way pollsters current the challenge also differs widely. Some surveys, for instance, ask about guidance or opposition for a distinct program, when other people lay out a selection of doable possibilities.

In an Axios-Ipsos poll from August, for instance, 55{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Us residents stated they supported “forgiving, or erasing, all federal student mortgage financial debt,” while 44{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} were opposed. But in a March 2021 poll from Grinnell School that asked Individuals to select involving a few insurance policies, just 27{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected forgiving university student loans for any one with university student personal debt, while 39{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} favored forgiving pupil financial loans “only for people in require” and 29{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} stated these kinds of loans should not be forgiven at all.

Taken jointly, all those numbers suggest that, with the scale and scope of governing administration motion on scholar mortgage debt even now not known, general public view toward a hypothetical response stays equally inchoate. You can find a very well of opportunity support for some kind of action on scholar financial debt, but considerably less consensus all around specifically what variety that ought to acquire — and significant place for Individuals to change their thoughts, based both equally on the particulars of any coverage, and the politics of its rollout.

Will Biden Cancel Student Loans? Here’s What the Public Wants.

Will Biden Cancel Student Loans? Here’s What the Public Wants.

Text measurement

Student debt: Biden is considering canceling some. Here’s why it might not be such a great idea

Student debt: Biden is considering canceling some. Here’s why it might not be such a great idea

But while some Democrats argue that the President should immediately erase large amounts of student loan debt for 43 million Americans with the stroke of his pen, the implications of such a significant policy move are complicated.

There are upsides and downsides.

On the one hand, student debt cancellation could deliver financial relief to millions of Americans, helping them buy their first homes, start businesses or save for retirement — all investments that may take a back seat to pay off student debt. Loan forgiveness could also help narrow the racial wealth gap, some experts say.

But broad student loan forgiveness would also shift the cost — likely hundreds of billions of dollars — to taxpayers, including those who chose not to go to college or already paid for their education. Loan cancellation could also add to inflation while doing nothing to address the root of the problem: college affordability.

“This is a pretty complex issue,” Education Secretary Miguel Cardona told MSNBC’s Symone Sanders earlier this month when she pressed him on why broad student debt cancellation hasn’t happened yet.
Borrowers currently hold $1.6 trillion in outstanding federal student loan debt, more than Americans owe in either credit card or auto loan debt. About 54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of borrowers with outstanding student loan debt owed less than $20,000 as of March 2021, according to the College Board. About 45{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the outstanding debt was held by the 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of borrowers owing $80,000 or more.
Compared with other kinds of debt, it’s extremely difficult to discharge student loans in bankruptcy. Prior to the pandemic, thousands of borrowers had their Social Security checks garnished because their student loans were in default.
Federal student loan payments and interest accrual have been frozen since March 2020 due to a pandemic-related pause that Biden has extended several times. Payments are set to resume after August 31, and the White House has indicated that the President will decide whether to cancel some student debt by then — just months before the midterm elections.

Student loan debt cancellation won’t lower the cost of college

A one-time cancellation of federal student loan debt would do nothing to bring down the cost of college for future borrowers or those who already paid for their degrees.

“Forgiving debt does not affect college affordability at all,” said Douglas Holtz-Eakin, president of the American Action Forum, a conservative think tank, and former director of the nonpartisan Congressional Budget Office.

In fact, it might even drive up the cost of college, he said. If prospective students have reason to believe that a future president may cancel their debt, they may be more willing to borrow more money — and colleges, in turn, may decide to charge more for tuition and fees.

“It creates this moral hazard and sets up an expectation that debt may be forgiven in the future,” Holtz-Eakin said.

Biden has acknowledged that college affordability is a problem and called for making community college free — but that move would require an act of Congress. The proposal was cut from the Biden-supported Build Back Better bill, which passed the House but stalled in the Senate.

An economic boost? Or higher costs for all?

A lot of borrowers say that having less student debt hanging over their heads could help ease the pain of rising inflation.

Here's who could benefit if Biden cancels $10,000 in student loan debt per borrower

If Biden cancels some student loan debt, it’s true that some borrowers will owe less money on a monthly basis and in turn, have more money in their pockets. But more consumer spending could add fuel to an already overheated economy.

“It’s a situation where what’s good for individuals is not necessarily good for society,” said Beth Akers, a senior fellow at the conservative American Enterprise Institute, where she focuses on the economics of higher education.

“In reality, it probably wouldn’t move the needle drastically in either direction. But the downside for cancellation got a bit worse since we entered this inflationary period,” Akers added.

One reason the economic impact may be modest is because borrowers generally pay back their student loans over time. They wouldn’t receive a lump sum of money if some of their debt is canceled. They would instead be required to pay less money each month toward their student loan payments.

A report from the nonpartisan Committee for a Responsible Federal Budget estimated that canceling all $1.6 trillion in federal student loan debt would increase the inflation rate by 0.1 to 0.5 percentage points over 12 months. But Biden has suggested he would cancel less than $50,000 per borrower.
The group has also found that canceling student debt is not a cost-effective way of providing economic stimulus.
The cost of canceling student loan debt would add to the deficit — transferring the cost from borrowers to all taxpayers. The White House has suggested Biden is considering canceling $10,000 per borrower, but excluding those who earn more than $125,000 a year. Under those parameters, student loan debt cancellation would cost at least $230 billion, according to the Committee for a Responsible Federal Budget.

Helping poorer households as well as high-earners

There are certainly many low-income Americans who are struggling to pay off their student loan debt. But it’s not easy to target loan forgiveness to those who need it the most and exclude borrowers with higher salaries.

Here's who could benefit if Biden cancels $10,000 in student loan debt per borrower

Many economists argue that canceling student loan debt would disproportionately benefit higher-wealth households, like those of doctors and lawyers, because those borrowers tend to have more student debt after attending graduate school.

An income threshold that cuts off borrowers who earn more than $125,000 a year could help make sure a bigger proportion of the relief goes to low-income borrowers.

Matthew Chingos, vice president of education data and policy at the Urban Institute, has estimated the share of forgiven debt by income group if Biden canceled $10,000 of student loan debt for borrowers earning less than $125,000 a year.

About 16{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the canceled dollars would go to the poorest households earning less than $25,000 a year.

Roughly one-quarter of the relief dollars would go to those earning between $26,000 and $44,000, and another quarter to those earning between $71,000 and $122,000.

One-third of the relief would go to households with total incomes between $45,000 and $70,000 a year.

Student debt cancellation would help close the racial wealth gap, experts say, because Black students are more likely to take on student debt, borrow larger amounts and take longer paying them off than their White peers.

“Canceling student debt is one of the most powerful ways to address racial and economic equity issues. The student loan system mirrors many of the inequalities that plague American society and widens the racial wealth gap,” wrote dozens of Democratic lawmakers in a March letter to Biden urging him to cancel “a meaningful amount of student debt.”
But the impact on the racial wealth gap could be muted by the fact that there are also fewer Black college students than White college students. Chingos’ model found that 62{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the canceled student loan dollars would go to White borrowers while 25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} would go to Black borrowers if Biden canceled up to $10,000 for those earning less than $125,000 a year.

Plus, most Americans don’t have student loan debt at all. Roughly 80{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of households below the $125,000 threshold don’t have student loan debt and would not see a benefit if Biden takes new action, according to Chingos.

Some loan forgiveness programs already exist, but they don’t always work

There are already federal student loan repayment programs that exist to help borrowers who are struggling to make their payments or were victims of for-profit college fraud.

Here's who is eligible for student loan debt relief after Biden's latest actions

Most federal student loan borrowers are eligible for loan repayment plans that tie their monthly payment amount to their income and family size, known as income-driven repayment plans. There are a variety of plans, but generally they cap payments at 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of a borrower’s discretionary income. After 20 or 25 years of payment, depending on the specific plan, the remaining student loan debt is forgiven.

But the programs are messy and don’t always work the way they should. A recent Government Accountability report found that few people have qualified for forgiveness under an income-driven repayment plan. The Department of Education had approved forgiveness for a total of 157 loans as of June 1, 2021. Meanwhile about 7,700 loans in repayment may have already been eligible for forgiveness.

The federal government also offers a student loan forgiveness plan for public sector workers who make 10 years of qualifying monthly payments. But the program, known as Public Service Loan Forgiveness, has also had problems that prevented people from qualifying.

The Biden administration has made changes to both the income-driven repayment program and the Public Service Loan Forgiveness program that are bringing millions of borrowers closer to debt forgiveness.

There is also a government forgiveness program for borrowers who enrolled at schools that shut down while they were enrolled or fell short of delivering the education the institutions promised. The Biden administration has been chipping away at a backlog of forgiveness claims filed under this program, known as borrower defense to repayment.

Altogether, about $18.5 billion in student loan debt has been forgiven for more than 750,000 borrowers since Biden took office, per the latest figures from the Education Department.