Student loan refund checks on their way to millions: Here’s what to do if you don’t benefit

Student loan refund checks on their way to millions: Here’s what to do if you don’t benefit

Millions are acquiring university student bank loan refund checks many thanks to a CARES Act provision, but a lot of will not qualify for any financial debt aid. (iStock)

As the White House’s scholar loan forgiveness application faces ongoing authorized battles, refund checks are currently being despatched to debtors who manufactured university student mortgage payments throughout the COVID-19 pandemic.

The checks occur immediately after the CARES Act paused payments for federal student financial loan debtors throughout the COVID-19 pandemic. Throughout this time, federal student loan payments ended up paused and interest fees dropped to {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} as part of the pandemic reduction package deal passed in March 2020.

“If you made voluntary payments throughout the payment pause (from March 13, 2020, by Dec. 31, 2022) and your current loan balance is under the volume of personal debt aid you will obtain, immediately after you efficiently implement for and obtain personal debt aid underneath the administration’s personal debt reduction strategy, we’ll routinely refund the total you paid out all through the payment pause (only up to the remaining amount of money of your suitable debt aid),” the Business office of Federal Pupil Assist states on its site.

Nonetheless, about 9.1 million federal scholar bank loan borrowers have produced at the very least just one payment from April 2020 to March 2022, according to the Place of work of Federal Pupil Aid

The pause is established to expire on December 31, 2022, next various extensions. Borrowers can call their pupil personal loan servicers to request refunds, according to the Business office of Federal College student Support. 

However, most federal student loan reduction doesn’t apply to private university student loan debtors. If you have private student loans and are hunting to lower your month-to-month payment, you could contemplate taking out a loan refinance to reduced your desire price. Go to Credible to review diverse college student bank loan loan providers, devoid of impacting your credit score rating.

Very good News: Private University student Financial loan Fascination Charges PLUNGE FOR 5- AND 10-Year Financial loans

Biden administration says scholar loan payment pause will not be extended

Even though federal scholar personal loan payments are presently paused and payments are optional, the Biden Administration declared in August the remaining extension of the “pause on pupil bank loan repayment, fascination, and collections through December 31, 2022.”

That suggests tens of millions of borrowers will want to get started building payments when all over again starting January 2023. The common monthly pupil financial loan payment for the latest graduates is $393, according to details from Credible. But more than 50 percent of college student financial loan debtors say they will not or may perhaps not be in a position to make payments when the pause ends, according to a review by Early morning Consult

If you have private scholar financial loans, they do not qualify for the federal college student personal loan payment pause. But you can reduce your month to month payments by refinancing.  Take a look at Credible to evaluate many student bank loan loan companies at after and find the interest charge which is ideal for you. 

HOW TO GET YOUR Funds All set FOR THE Finish OF THE College student Bank loan PAYMENTS PAUSE

University student bank loan forgiveness currently being battled in court

In August, President Joe Biden introduced his strategy to deliver one particular-time university student financial loan forgiveness of up to $10,000 to thousands and thousands of borrowers, or up to $20,000 for individuals who applied Pell Grant financial loans in faculty. To qualify, federal university student bank loan debtors ought to make less than $125,000 for each 12 months or $250,000 for married couples. 

But that plan is now remaining challenged in courtroom. A federal appeals court docket on Oct. 21 issued a non permanent block on the pupil personal loan forgiveness application as it considers lawful troubles raised by 6 states: Nebraska, Missouri, Arkansas, Iowa, Kansas and South Carolina. 

Prior to this determination, a federal district judge dismissed the circumstance, arguing plaintiffs did not exhibit that the plan straight harms their states. But the states appealed the decision. As the legal battle proceeds, the Biden Administration urged debtors to retain making use of for pupil mortgage forgiveness. 

But if Biden’s scholar mortgage forgiveness program goes into effect, private pupil personal loan borrowers won’t profit. If you have non-public university student loans, you can likely minimize your regular scholar financial loan payment by refinancing to a decreased desire price. Go to Credible to discover your personalised desire amount in minutes.

BIDEN ADMINISTRATION REVISES College student Financial loan FORGIVENESS FOR SOME Debtors

Have a finance-linked dilemma, but you should not know who to talk to? Email The Credible Funds Pro at moneyexpert@credible.com and your issue could be answered by Credible in our Cash Expert column.

5 things to know for Nov. 4: Twitter, Flu, January 6, Student Loans, Brittney Griner

5 things to know for Nov. 4: Twitter, Flu, January 6, Student Loans, Brittney Griner


CNN
 — 

The enormous rocket at the heart of NASA’s mission to return humans to the moon is being rolled out of its hangar today. After a series of issues and poor weather thwarted the first two launch attempts, the agency has spent weeks troubleshooting and is now gearing up for another attempt to get the rocket off the ground.

Here’s what else you need to know to Get Up to Speed and On with Your Day.

(You can get “5 Things You Need to Know Today” delivered to your inbox daily. Sign up here.)

Elon Musk will begin laying off Twitter employees this morning, according to a memo sent to staff, as several employees sue the billionaire alleging the layoffs are in violation of labor law. An email sent Thursday evening notified employees that they will receive a notice by 12 p.m. ET today that informs them of their employment status. The memo comes after previous reports said Musk had planned to lay off up to half of the company’s staff after acquiring it last week for $44 billion. Twitter had around 7,500 employees prior to Musk’s takeover. He started his tenure at Twitter by firing its CEO and two other executives, according to two people familiar with the decision. Musk also dissolved Twitter’s former board of directors.

Health officials are reinforcing their recommendations for people to get flu vaccines as this year’s strain picks up its pace across the US. There have been at least 880,000 cases of influenza, nearly 7,000 hospitalizations and 360 deaths from the flu so far this fall – including one pediatric death – according to data from the CDC. The numbers also show there haven’t been this many cases of influenza so early in the season since 2009. After recently receiving Covid-19 vaccines and boosters, some people have been waiting until later in the season to get the flu vaccine, CNN Medical Analyst Dr. Leana Wen said. However, since it takes about two weeks to reach optimal immune protection after receiving a flu vaccination, people who haven’t gotten one yet should do so now.

exp TSR.Todd.triple.threat.RSV.Covid.flu_00003501.png

Triple threat emerging: flu, Covid, RSV


02:52

– Source:
CNN

The House select committee investigating the January 6, 2021, insurrection at the US Capitol has interviewed more Secret Service witnesses, including the head of former Vice President Mike Pence’s detail. The committee is also expected to interview at least another half dozen Secret Service witnesses in the coming weeks, including current and former officials and agents, multiple sources told CNN. The panel’s efforts to secure testimony from an expanding list of current and former Secret Service agents during the closing months of its probe shows the committee is intensifying its push to learn more about what the Secret Service knew about looming threats to Pence and other government officials ahead of the attack. 

A sign with the U.S. Secret Service shield is cleaned before a briefing at the service's headquarters November 07, 2019 in Washington, DC.

Why Jan. 6 committee is asking Secret Service agent to testify again

President Joe Biden’s student loan forgiveness program remains on hold while a federal appeals court considers a legal challenge brought by six Republican-led states. The Biden administration is still accepting applications for student loan forgiveness, which is worth up to $20,000 per borrower, but it is not currently allowed to cancel student loan debt until the hold is removed. The Biden administration is also facing lawsuits from an attorney general and conservative groups that claim he does not have the legal authority to broadly cancel student loan debt. As for what happens next, an appeals court will decide whether to grant a preliminary injunction requested by the states. If granted, the student loan forgiveness program could be kept on hold while the court hears from both parties. If it’s not granted, debt cancellation may begin while the appeal plays out. The ruling could come at any time.

Cody Hounanian student debt crisis center bernal

College alum tells CNN: The only way to open the door was to take on student loan debt

US Embassy officials visited detained WNBA basketball star Brittney Griner in Russia on Thursday and “saw firsthand her tenacity and perseverance despite her present circumstances,” State Department spokesperson Ned Price said in a statement. They had not been able to visit Griner since early August but spoke with her by phone last month. After months of internal debate, the Biden administration previously offered to exchange a convicted Russian arms trafficker serving a 25-year US prison sentence as part of a potential deal to secure the release of Griner and Paul Whelan, who has been detained in a remote prison camp in Russia on espionage charges since 2018. US officials say they have continued to follow up on their offer and emphasized that the Americans’ detentions remain a top priority. 

Kyrie Irving apologizes amid Twitter controversy and suspension by Brooklyn Nets

The NBA star apologized on Instagram late Thursday, hours after the Nets announced a five-game suspension over his “failure to disavow antisemitism.”

Netflix launches a new plan with ads

After much anticipation, the platform’s cheaper plan with ads debuted in the US on Thursday. Here’s how it differs from existing plans. 

Miller Lite is selling a Christmas tree stand that doubles as a beer keg

Beer lovers are taking “holiday cheers” to a new level… This product was designed to “make it seem as if beer is being poured from the tree,” a company spokesman said. 

Jay-Z and Jeff Bezos are interested in buying the Washington Commanders together

The two billionaire businessmen already have major sports ties. Now, they’re in talks on a possible joint venture to buy an NFL team.

Iranian artist’s paintings of women take on a new sense of urgency

These symbol-laden paintings are charged with emotion and allude to issues that have recently sparked protests across Iran.

Which “extremely rare” item is expected to fetch up to $30 million at an upcoming auction?

A. George Washington’s journal

B. Key to the White House

C. First-edition copy of the US Constitution

D. Original senate gavel

Take CNN’s weekly news quiz here to see if you’re correct!

36

That’s the typical age of a first-time homebuyer in the US in 2022, up from 33 last year. A new report from the National Association of Realtors shows that first-time buyers made up just 26{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of all homebuyers in the year ending in June – an all-time low over approximately four decades. Financial analysts say many factors have made it a challenging environment for Millennials and Gen Zers to remain competitive in the market, including rising home prices, climbing mortgage rates, and the fact that younger generations have less cash saved for a down payment.

“Violence has no place in politics.

– White House press secretary Karine Jean-Pierre, condemning the reported assassination attempt on Thursday of Pakistan’s former Prime Minister Imran Khan. The country’s ex-leader was shot in the leg at a political rally outside the town of Gujranwala, Punjab province, Pakistani officials said. He was transported to Lahore to receive treatment and was in stable condition. An unnamed man suspected of firing shots at the rally has been detained, according to police. Khan has repeatedly claimed, without any evidence, that the US was behind his loss of power after he was ousted as Prime Minister in a no-confidence vote in April.

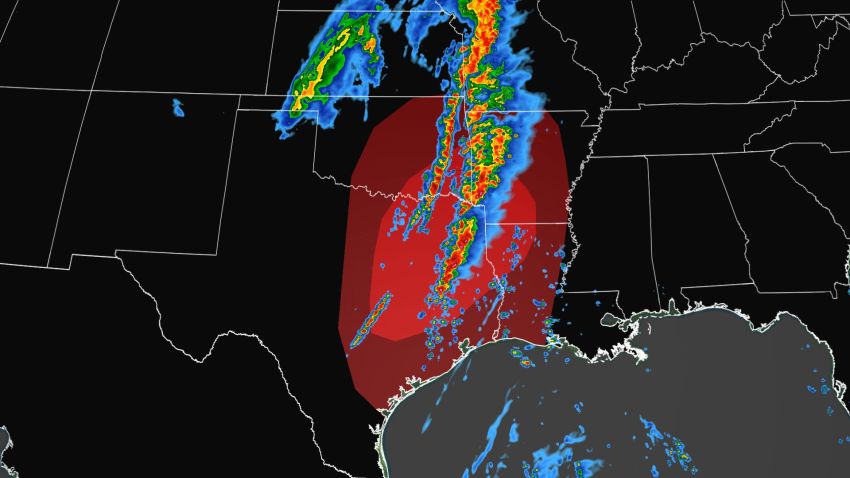
friday svr wx

Risk of severe storms for the South


03:08

– Source:
CNN

Check your local forecast here>>>

Indoor ocean simulator

The US Navy is testing its equipment in a massive pool that can replicate any wave situation in the world. Take a look inside. (Click here to view)

Supreme Court again declines to block Biden’s student loan relief plan

Supreme Court again declines to block Biden’s student loan relief plan

Supreme Court docket nominee and U.S. Courtroom of Appeals Decide Amy Coney Barrett on Capitol Hill in Washington, Oct 21, 2020.

Ken Cedeno | Reuters

The Supreme Courtroom on Friday rejected a next ask for to block the Biden administration’s student personal loan debt aid system.

Justice Amy Coney Barrett denied an emergency software to block the method introduced Tuesday by the Pacific Legal Basis, a conservative lawful team, on behalf of two debtors in Indiana.

On Oct. 20, Barrett rejected a similar ask for from the Brown County Taxpayers Association in Wisconsin.

Barrett is dependable for this sort of purposes issued from cases in the 7th U.S. Circuit Courtroom of Appeals, which involves Indiana and Wisconsin.

Friday’s selection has tiny functional impact. For now, university student financial loan forgiveness remains on hold from a challenge brought by 6 Republican-led states. An appeals court decide in the 8th Circuit in October granted the states’ unexpected emergency petition to keep the system pending thing to consider of the states’ attractiveness.

Far more from Personal Finance:
Treasury announces new Sequence I bond amount of 6.89{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}
Education Office to decrease ‘red tape’ on public company mortgage forgiveness
26 million debtors have utilized for college student loan forgiveness

Given that the White Home in August unveiled its strategy — to cancel $10,000 in college student financial loans for most debtors and up to $20,000 for people who gained Pell Grants for small-revenue households — it has faced at minimum 6 lawsuits.

Close to 26 million People in america have by now applied for student bank loan forgiveness, and the Biden administration has permitted 16 million of the requests, the White Home said Thursday. The administration has continued to stimulate debtors to apply for aid irrespective of the latest worries.

Caleb Kruckenberg, an attorney at Pacific Legal Basis, in an emailed statement mentioned, “We’re disappointed by modern denial but will proceed to combat this program in court.”

“Nearly considering the fact that this software was introduced, the administration has sought to stay clear of judicial scrutiny,” Kruckenberg stated. “Therefore much they have succeeded. But that does not alter the actuality that this application is unlawful from stem to stern.”

‘Standing’ continues to be an difficulty for forgiveness challenges

The primary impediment for people hoping to foil the president’s action has been acquiring a plaintiff who can demonstrate they have been harmed by the coverage, gurus say.

“These types of injury is necessary to establish what courts contact ‘standing,'” Laurence Tribe, a Harvard legislation professor, lately explained to CNBC. “No specific or small business or condition is demonstrably injured the way personal loan companies would have been if, for occasion, their financial loans to learners had been canceled.”

In that mild, Barrett’s final decision to reject the Pacific Legal Foundation’s ask for is not surprising, explained better training specialist Mark Kantrowitz.

“There were very several substantive differences amongst their unique lawsuit and the new lawsuit, which spells a lack of authorized standing,” he explained.

Republicans weigh plans to fight Biden's student loan forgiveness

In the Pacific Legal Basis situation, Indiana-based mostly plaintiffs Frank Garrison and Noel Johnson stated that they would be fiscally harmed if some of their university student financial debt was immediately forgiven since they would incur point out taxes on that canceled financial debt.

Indiana is a person of many states that has explained forgiveness would be taxable at the point out level, and potentially the county amount.

The two Garrison and Johnson are lawyers Garrison functions for the Pacific Authorized Basis and Johnson for the Public Desire Authorized Basis. They are pursuing reduction through the general public assistance loan forgiveness application, which enables those people who function for the govt or specific nonprofits to get their credit card debt canceled soon after 10 decades, or 120 payments. PSLF forgiveness is not regarded taxable profits.

Just after the preliminary lawsuit, the Education Department explained that borrowers can opt out if they do not want to have their financial loans forgiven.

Pupil bank loan debtors ‘in limbo’

As lawful issues mount, money advisors say borrowers are remaining pondering where by scholar bank loan forgiveness stands.

“The interference of the courts is actually troubling simply because individuals are searching for certainty with what is actually taking place with their scholar loans,” explained Ethan Miller, a accredited money planner and founder of Arranging for Development in the Washington, D.C., location. Miller specializes in purchasers with scholar loans.

“There was a prepare that clearly outlined the ways,” he stated. “And but everyone’s been place in limbo.”

Set up student for success with financial literacy education

Set up student for success with financial literacy education

Do you know the electric power of financial literacy? With Financial Literacy we can modify generational poverty, reinforce people, increase innovation, and make our communities extra secure.

Final thirty day period I shared the stage with fellow previous Bronco and Tremendous Bowl winner, Rod Smith. We went significantly outside of speaking about the new football period or the Broncos’ new quarterback and our most loved memories as players. We are on a greater crew now, one to encourage economical literacy in our communities.

We had an outstanding dialogue all over the have to have for money literacy and economic education, the personal lessons we have learned about generating sensible revenue choices, obtaining coaches (off the field) to mentor us, and what we hope for upcoming generations.

As Coloradans we have entrepreneurial spirit, innovation, epic sporting activities enthusiasts, and endless alternatives to accomplish our desires. For these explanations Colorado turned property for Rod and me all through and after our time as Broncos. However, in spite of Colorado’s entrepreneurial atmosphere, there are now no statewide graduation prerequisites for Colorado schools to give personalized finance or economic schooling classes. In point, only about 25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of faculty districts in the condition include personal finance in their authorized graduation qualifications. We will need to do far better for Colorado’s upcoming.

Economic Schooling Thirty day period, every Oct, just concluded and we have a golden opportunity to prioritize educating these important life capabilities — year ‘round.

The median credit history-card financial debt among the Coloradans is fourth optimum in the country and the point out was given a “C” in economic schooling by Champlain College’s Middle for Economic Literacy, which graded all 50 states on their efforts to develop fiscally literate substantial university graduates. We want to assist foreseeable future generations be prepared for key daily life choices they will deal with, how to help you save for the potential, and support the up coming technology.

When Rod and I sat on phase, in a fireside chat model at Economic Literacy Colorado’s fall fundraiser, we urged the viewers to equip our youthful persons with lifetime competencies that will set them up for accomplishment. Some of our vital takeaways consist of:

  1. Chase your goals but choose it slow. One of the most difficult factors to do as an grownup is help save cash. As two soccer stars who began building a lot of revenue at a speedy rate, we had been tempted to make significant-ticket purchases, as was the customized of our friends. But clever folks instructed us: help save 40{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of your revenue, and when it comes to a order, wait.
  2. Educate youth by taking them with you. Mentoring would make all the variance to a youthful individual. Bring them together with you on a enterprise offer, sit them upcoming to you on Zoom as you negotiate, and show them what you carry to the desk. This lights the route for them to do the same.
  3. We really don’t know what we don’t know. Faculty is where by you go to understand and acquire important lifestyle capabilities. We require our education and learning method to action up and provide our children with personal finance and financial instruction to established them up for long term accomplishment.

Before Rod and I had our time to communicate, we read from an unbelievably inspiring younger lady, Trinity Scales, a senior at the Denver University of the Arts. She needs to be a singer and songwriter and I have no question that she can accomplish nearly anything she sets her mind to.

Trinity just lately attended Financial Literacy Colorado’s Invest In Women summertime symposium to meet up with gals in the business enterprise and economic marketplace. She spoke about how meeting these inspirational women of all ages showed her that she has other options and profession paths she can choose to be prosperous in lifestyle as well. Trinity signifies our upcoming. We discover that no subject their background, youthful men and women in our point out are keen and ambitious to master far more about the instruments they have to achieve monetary independence. If we can increase obtain to academic programs, we will change our future generation’s good results.

Be part of me and Rod, and Financial Literacy Colorado in advocating for learners like Trinity. You can do so by:

  • Inquiring if your child’s faculty teaches own finance or economics.
  • Inquiring about the private finance and economics needs at your child’s faculty.
  • Championing financial and personal finance education and learning when talking to others.
  • Mentoring youth and discovering a seat for them at the desk.
  • Urging your legislators to make financial and private finance training graduation demands in educational institutions.

Colorado is the property of so lots of effective business owners and enterprise leaders. Let us make certain our youth are given the opportunity to study and develop into smart people, geared up and effective industry experts, all with monetary empowerment for several years to come.


Authors discuss their book on student loans and Black borrowers

Authors discuss their book on student loans and Black borrowers

Scholar debt is a challenge that influences folks of all races in the United States.

But in A Desire Defaulted: The Student Mortgage Disaster Among Black Borrowers (Harvard Education and learning Push), Jason N. Houle and Fenaba R. Addo argue that the university student financial loan industry is not one that operates for anyone. Black pupils “are deprived in two opposing phases of the course of action: credit card debt accumulation and credit card debt reimbursement,” they create. Houle is an associate professor of sociology at Dartmouth College, and Addo is an affiliate professor of general public policy at the University of North Carolina at Chapel Hill. They responded to issues about their ebook via e mail.

Q: Some folks say “debt is debt” and that race doesn’t participate in a significant job in debt. What would you say in reaction?

A: So, we are not sure who these “some people” are … so we’d want to know extra about who is arguing that race does not make any difference to greater reply this dilemma. But we would say it is indeniable that race matters for university student mortgage financial debt in the United States, and that it issues far more than most any other social issue you could imagine of. The data bear that out in quite substantially every single details established we could leverage on this situation. Racial disparities in debt are substantial when persons leave higher education, and they only get greater in the a long time that comply with. Racial disparities in financial debt repayment—difficulties with repayment, or default—are massive throughout all sectors (two-calendar year/4-yr/community/private).

In simple fact, in a overview of the literature, Jacob Gross, Nick Hillman and other students have shown that race explains approximately as much variation in default prices as does school completion. So, race matters a wonderful deal, and we just cannot just chalk up these racial disparities in mortgage results to issues associated to faculty option or higher education completion. For case in point, we know, in the combination, that 4-year college graduates have really very low default charges. But when you break it down by race, you see a really different story. Twelve several years following graduating from a 4-yr school, 4 percent of white borrowers have defaulted. In the meantime, about just one in five (20 percent) of Black 4-year school graduates have defaulted on their financial loans. There’s a distinct racial divide right here in terms of debt accumulation, financial debt repayment and the outcomes that pupil loans have on the perfectly-remaining of borrowers.

Extra broadly, there are other means that “debt is debt” argument falls apart. Credit card debt is what economist sociologists phone “relational”—you have a contract concerning the loan company and the debtor (and listed here we could search to how Black pupils are discriminated towards in financial loan marketplaces, which would also undermine any assert that “debt is debt”). But debt is also tied to all types of relationships—the associations concerning you and your household as you come to a decision how you’re likely to fork out for faculty, for example, or even the relationship concerning you and your intimate husband or wife as you navigate personal debt reimbursement. So, credit card debt is profoundly social. And if we inquire thoughts like: Why are some people using on so a great deal [more] debt than other people? Why are some people today getting issue paying down financial debt when other people are not? Why is financial debt so stress filled, so consuming and so substantially a millstone that weighs down some individuals but not other people? What we obtain is that, for some, getting on debt is an chance, and for others, it’s a profound possibility. And, we argue in the e book, these variances are deeply tied to race.

But we’d also add this: it is not just that race matters. It’s that anti-Black racism issues. Why are Black students saddled with much more credit card debt, have far more trouble repaying that personal debt, and why is university doing work improved for white college students than it is for Black college students? We simply cannot response these queries without the need of recognizing that university student credit card debt the two displays and provides current racial inequalities that are rooted in historic processes of social exclusion, and that Black pupils and their people are expected to navigate institutions that were being not designed for them.

Q: When you interviewed Black debtors, how did they see the problem?

A: You would likely want to dig into the reserve to see all of these stories here—because our respondents have a whole lot to say about this issue, and your query is quite, very broad. So permit us just emphasis on one theme that arrived out of our interviews: quite a few of the folks we talked to were being struggling beneath the fat of their debt—they amassed a great deal of personal debt in university, they ended up obtaining trouble repaying that personal debt afterwards—and a ton of these debtors had been actually grappling with the query “What could I have completed in a different way?” Some folks took this to their extreme—blaming on their own for their situation—but fairly substantially everybody took responsibility and, with the reward of hindsight, think they could have designed some distinctive decision so that they wouldn’t have finished up saddled with all this personal debt. And of program, these debtors have … internalized the broader social narrative on financial debt: that we could resolve all of these troubles if people had been just extra fiscally literate, or designed greater conclusions.

When we were being conducting our interviews, we questioned everybody how they felt about their university student financial loans, and quite a great deal all people gave us some edition of the tale “I want I could have finished some thing differently,” as if there was some final decision that they could have built that would have kept them out of personal debt. But a single tale trapped out to us. This human being who we phone Alexandra was actually challenging on herself—you know, she had like $30k in financial debt, she was having a tricky time earning her payments each and every month, she was working with unfavorable amortization. And all she did was blame herself, and she deconstructed every single solitary final decision she created. Here’s one particular matter she claimed: “I just desire I was a lot more intense. I received scholarships, but I would like I was even more intense in successful much more scholarships. I just wish I realized, like, ‘Hey, you should actually set up a company in high school.’ So then, I’d be in a position to shell out for school outright.”

We definitely like this quote, and this tale, due to the fact it will make it so obvious that she did every little thing “right” and it just was not plenty of. And she has gotten to the issue where she has these insanely superior anticipations for her superior school–aged self that are wholly unrealistic. And it would make the remedy evident: no amount of money of fiscal planning, or literacy, was heading to save her from this final result. Which helps make it all the far more upsetting, and unfortunate, that she appears to be like inward at her own faults when she is pondering about her problem.

That is a person illustration, but it is just an illustration. So several of our job interview respondents ended up constantly weighing the economic expenses and rewards of distinctive conclusions: perhaps they wished to go to that HBCU out of state, but they went to the regional university down the street to preserve income and maintain living at dwelling. And nonetheless they nevertheless desire they could have carried out one thing otherwise.

We typically communicate about university student bank loan financial debt in this state as the final result of unique conclusions: that with some economical literacy, or cautious arranging, college students can stay clear of getting on far too a lot financial debt or obtaining into difficulty. Politicians speak about this all of the time. Much of the debate all around pupil financial debt forgiveness revolves around this pretty problem: that some folks argue we do not want to subsidize other people’s lousy choices. But there’s so numerous difficulties with this framing. One particular, is it frames personal debt as some form of “mistake”—like if you took on debt, or far too considerably financial debt, then that is your individual fault, the result of your have decisions. But naturally, we’ve made better education such that you practically have no preference but to borrow if you want to go to school. So heading into personal debt is not some choice that needs to be optimized or enhanced upon—it’s a element of the method.

Q: How does debt affect Black students’ decisions about likely to graduate or specialist university?

A: So if we’re asking why so lots of younger men and women are picking out to go to graduate/specialist faculty, we can assume of financial debt as component of this story, but only portion. What really matters are the options and occupations that are available for people immediately after they complete their undergraduate diploma. A good deal of the debtors we talked to who went to graduate faculty experienced a very similar tale: they graduated, had issues getting a job just after college and then finished up generating much fewer than they imagined they would have in employment that only occasionally aligned with their degree. Then, at the time their pupil financial loans arrived because of 6 months following graduation, they experienced 1 far more invoice to spend when they were being by now having difficulties to locate their footing. And so normally, a ton of them were like: very well, if I want to make a dwelling, or get my foot in the door at some better occupation, I guess I have to go to graduate faculty. This is classic credentialism: as companies ratchet up the demands for some employment, then the labor pool will follow.

And all over again, ordinarily scholars and policy makers are a lot less concerned about graduate school debt, possibly with excellent motive: individuals with specialist degrees (lawyers, health professionals) might have eye-popping financial debt masses, but on normal they never have significantly issues repaying that financial debt since they are in these superior-paying professions. But newer research demonstrates that graduate school financial debt is rising, and that racial disparities in graduate faculty financial debt have gone via the roof in the past decade or so, for several of the exact same good reasons we communicate about in the book. And of program, graduate university is exactly where you can rack up the serious eye-popping amounts of credit card debt: $60, $80, $100k—because numerous of these graduate courses are unfunded, they serve to deliver in revenue for the faculty, and there are no mortgage boundaries for Furthermore loans.

So the dilemma is, will these graduate degrees spend off? And the response is we just don’t know, but what we do know is not promising: that is, even among the specialist degree holders, we see large racial disparities in salaries, promotion and profession advancement. So, once again, not only are Black borrowers having on a lot more hazard in the pursuit of a graduate degree—which they’re carrying out not as a vainness venture, but simply because they really feel like they have no choice—but the benefits do not look to be the exact same as their white counterparts will take pleasure in.

Q: What about what President Biden is hoping to do? Has he acknowledged financial debt as a racial difficulty?

A: Very well, initially of all, Biden is in all probability executing near to every thing he can given the political realities of Congress. This in all probability wasn’t going to go in the Residence and Senate, so this debt-forgiveness plan is almost certainly the ideal we can hope for, and to be trustworthy, it was in all probability a lot more than quite a few of us considered was possible three or 4 several years ago.

Does Biden figure out that university student personal debt is a racial justice issue? Most likely this is an argument that other people in his celebration have manufactured, even if he doesn’t converse about this publicly. So, we don’t know what it is in his heart.

But if we want to request whether this debt forgiveness may perhaps reduce some of the stark racial disparities in the stress of student financial loan financial debt we argue in this ebook? Perhaps, but it is not a silver bullet. That claimed, there are some options of the method that are promising. A several factors: 1) the policy by itself is progressive, and acknowledges inequality, if at minimum as a result of the lens of income. Those people with Pell Grants—which include things like many Black borrowers—are in a position to get up to $20,000 in forgiveness, whilst other debtors who had been most likely a lot more socially advantaged get significantly less in forgiveness. 2) The method is simple to utilize for, and (hopefully) basic to profit from. Our colleagues Pam Herd and Don Moynihan compose eloquently about “administrative burden” and how very well-indicating social plans and procedures are exceptionally difficult for people to entry. This is notably true in the pupil mortgage program: cash flow-dependent compensation, for example, is hard to access and keep enrolled in, and we all listened to the horror stories about the rollout of the Public Services Financial loan Forgiveness program …

Q: What more really should Congress, the president and faculties do about this difficulty?

A: At the close of the day, personal debt forgiveness is an crucial plan, but it is a downstream remedy to an upstream difficulty. And if we do not do extra to deal with faculty affordability—perhaps by rising monetary help, or relocating forward a nationwide plan on no cost college—we’re likely to be right back to square 1 in one more decade. So we completely need to see a lot more action on this entrance. And, as we argue in the guide, so a lot of the story at the rear of racial disparities in university student bank loan debt replicate[s] broader racial inequalities in this nation that are so significantly larger than larger education—structural racism, discrimination in the labor industry and discrimination in personal loan markets—so this will need broader fixes. Indeed, these are exactly the problems that the Black Life Make any difference movement reminded so lots of individuals of throughout the pandemic. So, if we don’t deal with the root of the problem—racism—we’re not likely to clear up this issue wholly.


Education Dept. overhauls federal student loan system

Education Dept. overhauls federal student loan system

Chip Somodevilla | Getty Illustrations or photos News | Getty Photographs

The U.S. Office of Training declared on Monday sweeping new changes to the federal scholar financial loan procedure, which includes extra shopper protections for borrowers and boundaries on the quantity of curiosity that can accrue on the personal debt.

“These days is a monumental move forward in the Biden-Harris team’s initiatives to resolve a broken pupil mortgage technique and construct one that is simpler, fairer, and much more accountable to borrowers,” reported U.S. Secretary of Training Miguel Cardona, in a assertion.

The new regulations really should make it easier for learners who’ve been defrauded by their educational institutions to get their university student loans canceled by the governing administration by the borrower defense course of action, and allows for the Education and learning Section to arrive to a resolve about these requests for aid as a team, in its place of necessitating each individual borrower to individually prove that they ended up sufficiently harmed or misled by their university.

More from Personal Finance:
How Fed’s curiosity fee hikes designed borrowing costlier
Strategies to support stretch your paycheck amid substantial inflation
‘Ugly times’ are pushing record annuity sales

Beneath the procedures, bigger training establishments that acknowledge federal pupil assist will be banned from demanding borrowers to signal necessary pre-dispute arbitration agreements or to waive their ability to participate in a course-action lawsuit above their borrower defense declare.

The Biden administration will also suppress the observe of desire capitalization — in which unpaid fascination is included to the borrower’s principal.

The Public Company Mortgage Forgiveness Software, which lets general public servants and these who perform for particular nonprofits to get their debt canceled just after a ten years, will also get an overhaul. Months that formerly did not qualify toward a borrowers’ credit card debt relief, such as people when they were in a economic hardship deferment, will be counted. Earlier ineligible late payments will also now qualify.

President Biden announces student loan debt relief plan

These changes will go into result on July 1, 2023.

Biden administration officers described these improvements as required and urgent to resolve a system plagued by complications.

In advance of the coronavirus pandemic, when the U.S. financial state was taking pleasure in just one of its healthiest durations in background, only about fifty percent of debtors had been in compensation. A quarter — or much more than 10 million folks — were in delinquency or default, and the rest experienced applied for momentary relief for struggling debtors, such as deferments or forbearances. These grim figures led to comparisons with the 2008 home loan disaster.