Fairer higher education system for students and taxpayers

Fairer higher education system for students and taxpayers

The better instruction process in England will be produced fairer for students and taxpayers many thanks to big reforms announced by the govt now.

College student finance will be place on a extra sustainable footing by guaranteeing a lot more pupils are having to pay again their mortgage in whole, and there will be a clampdown on very poor-excellent university classes that never gain graduates in the lengthy-expression.

Under the present method, additional individuals than at any time are heading to college but as well frequently, pupils are racking up credit card debt for very low-top quality classes that do not lead to a graduate occupation with a fantastic wage. This suggests that some pupils by no means even begin spending off their pupil financial loan. And presently, only a quarter of learners who started out complete-time undergraduate levels in 2020/21 are forecast to repay their financial loans in full.

The cost of pupil loans is raising speedily. The benefit of excellent financial loans at the stop of March 2021 attained £161 billion and it is forecast to increase to 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} a trillion pounds by 2043.

The govt is these days using motion to deal with the trouble head-on, rather than passing the challenge on to potential generations, by location out major alterations to the way learners will repay their financial loans, and producing a sustainable program which also assures obtain for all.

To make the process fairer for learners, the college student loan desire charge will be set at RPI+{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for new debtors beginning programs from 2023/24, that means that graduates will no for a longer period repay far more than they borrowed in genuine conditions. This satisfies a crucial manifesto motivation to deal with college student mortgage curiosity charges in this parliament.

Blended with the continued tuition cost freeze declared earlier this month, a college student coming into a three-year study course in educational yr 2023/24 could see their personal debt lessened by up to £11,500 at the point at which they come to be qualified to repay.

Nowadays the govt has also announced the tuition fee cap will be frozen at £9,250 for a further two decades – up to and which include 2024/25, more lessening the true price tag to college students.

To make the method fairer for taxpayers, the repayment threshold – the issue at which graduates start out repaying their college student bank loan – for new debtors setting up classes from September 2023 will be established at £25,000 until 2026-27.

This nevertheless usually means that graduates will not begin repaying until finally they have achieved effectively around the present median younger non-graduate salary of £21,500.

This makes guaranteed that an individual benefitting from a university degree tends to make a reasonable contribution to its cost: for instance, a graduate earning £28,000 would spend back £17 a month.

Graduate salaries are continuing to rise – in 2020, the common income for a graduate aged 21-30 was £6,500 larger than for a non-graduate – so it is appropriate we question individuals who are benefitting economically from the investment the taxpayer has produced in their greater schooling to add toward it.

The pupil mortgage repayment time period will also be prolonged to 40 yrs for new debtors from September 2023, to assure additional pupils repay their loan in full, taking into account the reality that people today are now working and earning for for a longer period.

Taken together, these improvements will lead to sizeable savings, ensuring the scholar finance technique is sustainable for the extended time period and can proceed to benefit hundreds of countless numbers of students each 12 months.

Schooling Secretary Nadhim Zahawi claimed:

Our country’s earth major universities and faculties are critical to levelling up chance by opening up access to a array of lifelong flexible submit-18 choices to assistance folks prepare, retrain and upskill.

This bundle of reforms will ensure college students are currently being supplied a range of distinct pathways, regardless of whether that is larger or additional education and learning, that lead to alternatives with the ideal results – and put an close the moment for all to higher interest charges on their university student financial loans.

I am delighted to oversee such a considerable amount of expense – practically £900m – bolstered by a revised, fairer, and extra sustainable student finance method which will preserve Greater Training accessible and accountable. These changes will develop a fairer program for the two pupils and the taxpayer.

Better and Even more Education Minister Michelle Donelan:

We are offering a fairer method for learners, graduates and taxpayers as well as foreseeable future-proofing the student finance program. We are freezing tuition expenses and slashing curiosity premiums for new pupil financial loan debtors, building positive that less than these conditions no-one will pay out again a lot more than they have borrowed in genuine conditions. This Federal government is offering on its manifesto pledges.

We are investing an additional £900m in our put up 18 education technique and bringing about a innovative modify in the way college students can examine, retrain and upskill throughout their life time.

The governing administration has also published two consultations. The first will seek sights on how to assure young men and women are encouraged to pursue the right route for them, and receive a reasonable offer for their financial investment if they pick out to go to college.

This contains contemplating the introduction of minimal eligibility requirements, to assure learners aren’t getting pushed into bigger schooling prior to they are prepared, and pupil quantity controls, so that weak-excellent, lower-charge courses which direct to very poor outcomes for college students, are not incentivised to expand uncontrollably.

The 2nd will set out plans to deliver the Lifelong Financial loan Entitlement (LLE) well worth the equal of four decades of article-18 training (i.e. £37,000 in today’s fees) to support college students to study, practice, retrain or upskill at any stage throughout their lives by means of adaptable and modular classes.

This is a seismic change in the way put up-18 instruction is funded and accessed, delivering additional choices, unlocking possibilities and strengthening social mobility.

The variations to student finance appear alongside broader reforms to greater schooling – backed by practically £900 million in new investment decision in excess of the following 3 years – to renovate the sector, supplying more routes throughout increased and technical training and enabling lifelong obtain to loans. This incorporate delivering additional funding for programs that assistance the NHS this sort of as drugs, dentistry and midwifery as very well as science and engineering. This is the major boost in federal government funding to help college students and training in the HE sector in more than a 10 years.

This announcement alongside the ongoing capabilities reforms, like the actions in our Skills and Write-up-16 Training Bill, which will make absolutely sure that everybody, no subject their track record, can acquire the abilities they want, at any stage of their lifestyle, to kickstart an exciting occupation or to retrain and upskill for a new purpose.

We are investing £3.8 billion far more in techniques over the class of this Parliament, with Apprenticeships, T Ranges, and the Lifelong Financial loan Entitlement our flagship programmes. In the Levelling Up white paper, the Authorities established out a new skills mission that will focus on 200,000 extra individuals in England to assistance them finish significant-good quality education each individual 12 months by 2030, which include the intention of 80,000 additional people today finishing courses in parts of England with the lowest abilities stages.

Sir Philip Augar, Chair of the Write-up-18 Education and learning Review panel reported:

The Capabilities Bill already going through Parliament, the lifelong understanding entitlement, the reforms to university student finance and the refocussing of HE offer a framework that is reasonable, sustainable and has the prospective to drive the total economic climate forward. The offer is constant with the spirit of the report of the article-18 instruction panel that I experienced the privilege to chair and types the basis of a correctly related even more and larger training sector. That link is prolonged overdue.

Robert Colvile, Director of The Centre for Plan Studies reported:

It’s encouraging to see the Authorities aim on offering benefit for revenue both equally for learners and taxpayers, and acting to deal with some of the most unfair factors of the current system, which we’ve highlighted in our exploration. In particular it is welcome to see ministers address the extortionate stage of the desire amount on scholar debt and the way a minority of bad-good quality classes tarnish the status of the better education sector – and the prospective buyers of the college students that get them. It is also very good to see the continued concentration on apprenticeships and lifelong finding out, as element of the overdue energy to diversify tertiary education beyond the common a few-12 months diploma.

Will Tanner, Director of Onward, reported:

For also extensive several young people have been inspired to unsuitable degrees that do very little to help their occupations or even go away them fiscally even worse off. The Govt is right to place a prevent to this and I hope that universities perform with ministers to stamp out low-quality programs and make sure every younger individual is on their appropriate path.

These reforms, coupled with a generous new Countrywide Scholarship Scheme for deprived dazzling youthful men and women, could completely transform increased instruction for the improved and support younger persons create improved futures, irrespective of their qualifications.

James Kirkup, Director of the Social Marketplace Foundation, claimed:

The Lifelong Mortgage Entitlement has the prospective to give additional folks the options offered by Britain’s great universities and schools, some thing that will only turn out to be extra significant as lifespans increase and occupations get for a longer period. It is a likelihood for training vendors and companies to perform together to provide far more training to more men and women in new and versatile techniques, benefiting learners and the Uk financial state.

Degree apprenticeships are a further great illustration of that sort of partnership and reveal how the different areas of the education and expertise system can appear jointly to provide new possibilities and support a additional successful economy.

David Goodhart, Head of Capabilities and Training at the Policy Trade feel tank and creator of Head, Hand, Coronary heart: The Battle for Dignity and Position in the 21st Century (Penguin):

These measures are an additional critical stage to rebalancing publish-faculty training and education. For far too extended we have been more than-producing academically educated kids with low quality degrees who are unable to get graduate work opportunities, although companies are determined for folks with middle amount specialized and electronic capabilities. The Lifelong Loan Entitlement should also help to reverse the plunge in portion-time and experienced college students in bigger training, even though targeted expenditure boosts individuals bigger tutorial skills that we do need in STEM disciplines.
Financial education is effective and efficient

Financial education is effective and efficient

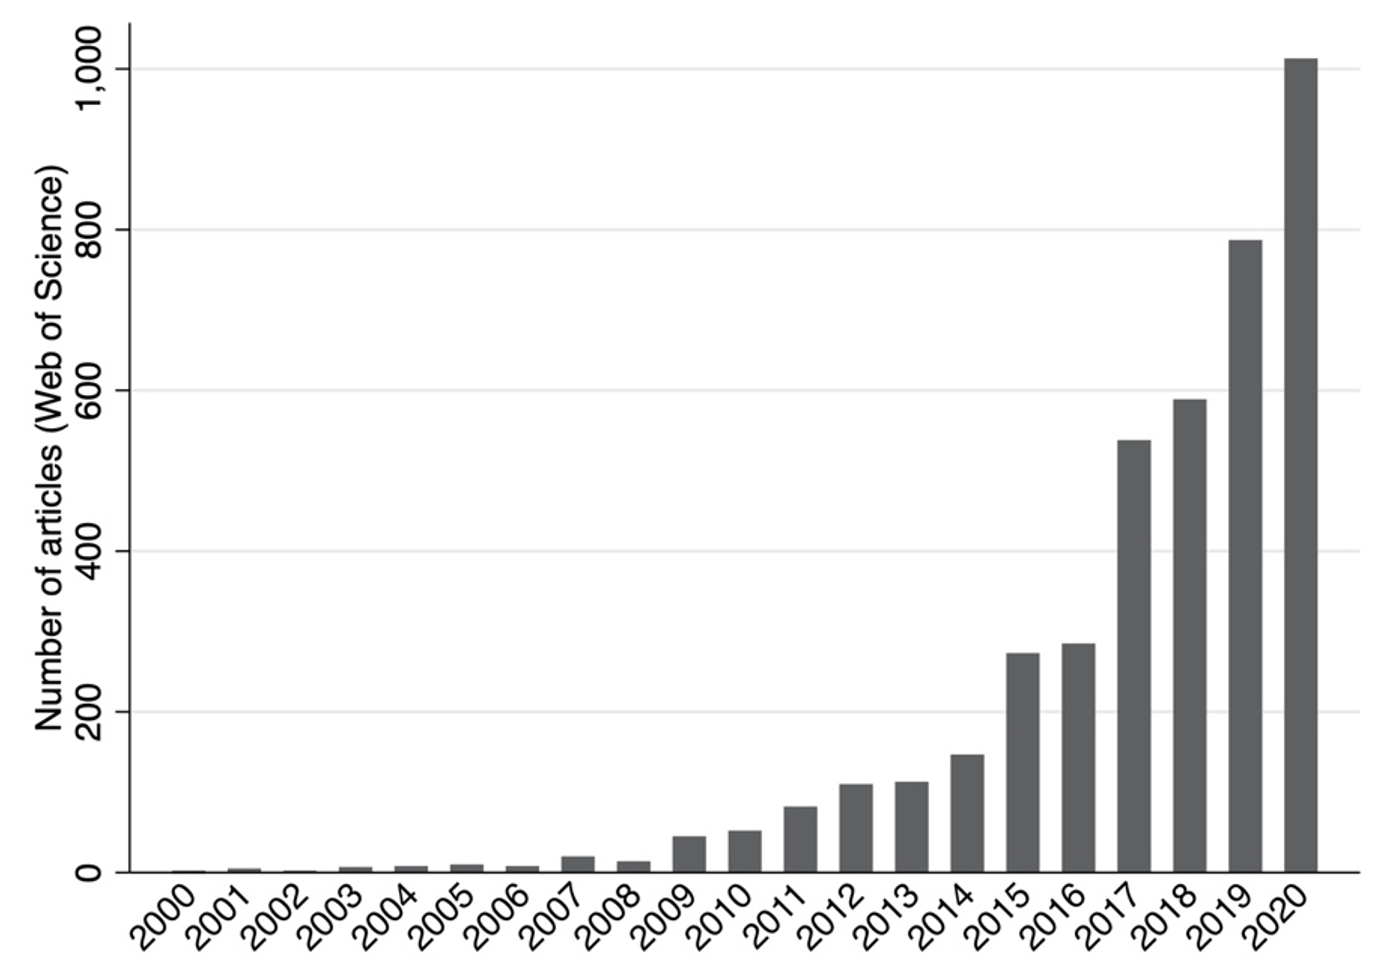
Analysis on economical literacy has been gaining momentum, and the variety of posts that incorporate the time period ‘financial literacy’ in their title or summary has grown swiftly in the past 10 decades (see Figure 1). The recognition of financial literacy is even further apparent in coverage and policymaking: the big greater part of OECD member international locations now have nationwide methods for fiscal training (OECD 2015). 

Figure 1 Number of content articles on ‘financial literacy’ for each year in the Internet of Science, January 2022

Financial education is effective and efficient

Continue to, there is resistance to introducing economic schooling in faculties or the office. Two big arguments in opposition to monetary education and learning are that it would be ineffective and inefficient. We investigate the applicable proof and display that these concerns are misguided.

Evidence from randomised managed trials

The proof on money schooling consists of far more than 1,000 released studies. Right here, we concentrate on a somewhat modest established that is regarded as the gold typical of arduous evaluation – randomised managed trials. We retrieved 76 randomised managed trials, masking 33 nations and around 160,000 individuals (Kaiser et al. 2020). The noted interventions ordinarily concentrate on several procedure consequences in just one particular review, building 673 treatment effects in whole: 50 randomised controlled trials report 215 outcomes about financial understanding and 64 report 458 consequences with regards to a variety of domains of financial behaviour.

Meta-analyses with a variety of methods

We use a meta-assessment to ascertain the basic impact of economical instruction, applying the 670 procedure consequences as observations. The treatment method result on every single consequence is calculated in standardised suggest distinctions. These consequences are then aggregated. 

There are two main strategies in the literature to evaluate usefulness. Meta-analysis in fields such as drugs usually works by using the prevalent-result tactic, which assumes that there is a widespread real influence and that noticed variations in remedy-influence estimates are due to random sampling mistake. 

In money instruction, nonetheless, most meta-analyses rely on the random-outcomes technique, which assumes that the reports beneath consideration are quite heterogeneous, in particular with regards to goal teams, intervention goals, or intensity (e.g. Miller et al. 2015). As a result, the normal outcome is assumed not to be a preset parameter but, somewhat, a distribution of probable accurate effects. We use this latter approach, while we are watchful to exhibit that our findings are not driven by the selection of the estimation technique (Kaiser et al. 2020, Appendix B).

Financial education improves awareness and behaviour

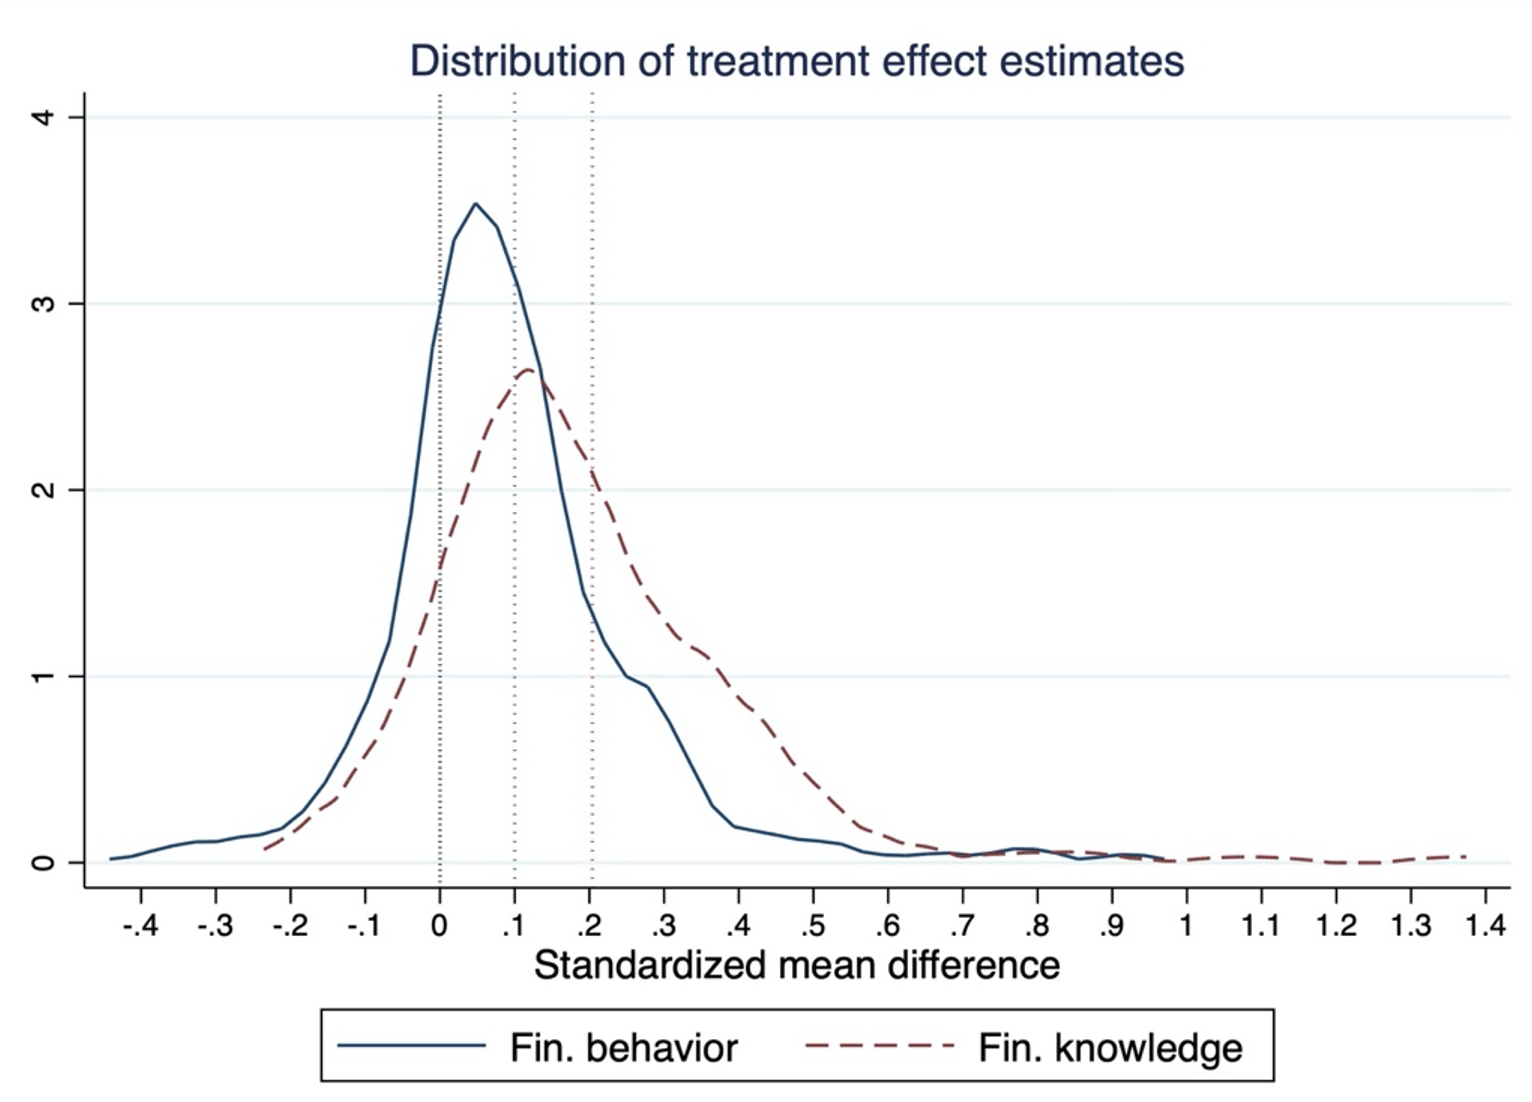
We locate that economical instruction will work and performs effectively. Performance is assessed by two benchmarks: 1st, by contemplating the believed general result and, 2nd, by evaluating the magnitude of cure effects to other fields of education interventions. The mean influence of monetary education and learning on expertise is about .2 standard deviations, and the necessarily mean effect on behaviour is .10 standard deviations. The equipped distribution of these benefits is proven in Figure 2.

Figure 2 Uncooked distribution of cure influence estimates (Kaiser et al. 2020)

Notes: Dotted lines show meta-assessment weighted averages at .1 and .204 regular deviations for the outcomes of money behaviours and financial know-how, respectively.

The self esteem intervals associated with these estimates rule out zero-results of monetary education and learning. Even now, the comprehensive distribution of noticed treatment method-outcome estimates suggests that not all interventions realize success (determinants of accomplishment include, for case in point, teacher excellent or motivating mothers and fathers see Borowiecki 2022, Listing et al. 2021). This fact, nonetheless, does not justify the declare of ‘mixed evidence’ for financial instruction simply because this sort of failures are prevalent and noticed in other fields of schooling too. Moreover, some failures are usually anticipated in fields with very little encounter, and fiscal education is a young industry, as also indicated by the increasing impact dimensions amid more new randomised controlled trials relative to the very first interventions.

Particular finance instruction is as effective as schooling in other domains

We assess the effectiveness of fiscal instruction to other fields to assess what can be anticipated from fiscal schooling. The order of magnitude of .20 conventional deviations (i.e. the typical influence on fiscal understanding) is equivalent to typical outcomes of other instructional interventions. Relying on the classification of Kraft (2019), our final result of .203 can be deemed as a medium to large effect.

With regards to the impression on monetary conduct, conduct may perhaps be a lot more hard to influence than know-how. In this perception, the reasonably lesser measurement of the statistical outcome of financial instruction on conduct helps make sense. An typical influence of .1 normal deviations is comparable to other domains of academic interventions, these kinds of as health or electrical power conservation.

End result is robust to adjusting for publication bias

Even if the estimated success is strong to the estimation strategy, there is issue that posted benefits could possibly be distorted by the selective publication of experiments. Factors for this sort of a publication bias are that lecturers might be far more very likely to publish papers with statistically considerable final results than with null success, and that funding institutions may perhaps desire good results. There is indeed robust evidence for publication bias and selective reporting of success in economics (e.g. Brodeur et al. 2020). Thus, it appears vital to account for potential biases just before earning a judgement on the usefulness of financial schooling.

We apply the technique by Andrews and Kasy (2019) to management for a attainable publication bias. Success clearly show that this bias is current and significant, with conditional publication chances of insignificant benefits staying amongst 25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 40{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} as opposed to success that go tests for regular degrees of statistical importance. Therefore, the described efficiency of financial training might be inflated thanks to publication bias, but the modified result dimensions keep on being sizeable (about .15 regular deviations on information and about .06 regular deviations on behaviour) and the involved self-confidence intervals rule out zero-consequences.

Money schooling is a small-price tag intervention

Whilst economic education programmes are efficient on average, small is known about their costs and price-performance. In our sample of randomised managed trials, 20 papers also report costs. 

The mean charge for each outcome and participant is about $60, which is a ‘low cost’ educational intervention in accordance to Kraft (2019). As a result, the medium-sized remedy effects appear to be at small fees, resulting in a usually favourable cost-success ratio.

Summary

The debate about financial education and learning programmes is at times hindered by the argument that the evidence about their effectiveness is ‘mixed’. This stems from concentrating on randomised controlled trials which generally seem to report scaled-down estimates of statistical effect than effects-analysis models with lessen degrees of interior validity (Fernandes et al. 2014, Kaiser and Menkhoff 2017). 

Nonetheless, when we analyse not long ago available randomised managed trials that consist of a big range of reports across 33 countries, we come across a sizeable standard impact of fiscal schooling on knowledge and behaviour at a comparatively very low charge. This final result retains true for various empirical designs and changing for publication bias. These success offer a stable foundation to lengthen research into better comprehending which styles of programmes are most impactful, price tag-efficient, and scalable and for whom.

References

Andrews, I, and M Kasy (2019), “Identification of and correction for publication bias”, American Economic Assessment 109(8): 2766–94.

Borowiecki, K J (2022), “How lecturers influence creative imagination: Proof from tunes composition considering the fact that 1450”, VoxEU.org, 29 January.

Brodeur, A, N Prepare dinner and A Heyes (2020), “Methods subject: p-hacking and publication bias in causal examination in economics”, American Economic Evaluation 100(11): 3634–60.

Fernandes, D, J G Lynch Jr and R G Netemeyer (2014), “Financial literacy, money education, and downstream monetary behaviors”, Administration Science 60(8): 1861–83.

Kaiser, T, A Lusardi, L Menkhoff and C City (2020), “Financial training affects fiscal knowledge and downstream behaviors”, CEPR Dialogue Paper 14741 and Journal of Financial Economics, forthcoming.

Kaiser, T, and L Menkhoff (2017), “Does monetary instruction impact monetary habits, and if so, when?”, Planet Bank Economic Critique 31(3): 611–30.

Kraft, M A (2019), “Interpreting result sizes of training interventions”, Academic Researcher, forthcoming.

List, J, J Pernaudet and D Suskind (2021), “Addressing the roots of educational inequities by shifting parental beliefs”, VoxEU.org, 12 December.

Miller, M, J Reichelstein, C Salas and B Zia (2015), “Can you help another person become monetarily able? A meta-evaluation of the literature”, Earth Financial institution Research Observer 30(2): 220–46.

OECD (2015), National procedures for economic instruction, OECD/INFE Coverage Handbook, Paris: OECD.

I’m 66 and retired, but owe $70K in student loans. Can I get them canceled?

I’m 66 and retired, but owe K in student loans. Can I get them canceled?

On an earnings-primarily based compensation prepare for student financial loans, some borrowers may possibly have payments that are $.


Getty Images/iStockphoto

Dilemma: I’m 66 yrs aged and retired and have $70,000 in scholar bank loan financial debt. I’m at the moment on an money-driven compensation plan but my financial loans are getting moved to a distinct loan servicing agency. My bank loan payments have been $ a month since my Social Security is too reduced to warrant payments. Is there a way to have this financial debt canceled? I do not hope l will live prolonged enough to repay these financial loans.

Have a question about having out of scholar bank loan or other debt? Electronic mail chill@marketwatch.com.

Remedy:  This question “cuts to the heart” of why senior citizens are asking the Biden administration “What about us?” concerning pupil mortgage aid, says Andrew Pentis, loans pro and certified pupil loan counselor at StudentLoanHero. The administration has “been really fantastic about specific scholar loan forgiveness programs” for groups this sort of as veterans and disabled people, he adds, but for more mature borrowers, not so a great deal. That mentioned, execs have some ideas for you.

In your particular case, student mortgage professionals concur on a range of fronts about this circumstance: a) There is no magic bullet to terminate the personal debt b) recognition of the the latest reshuffling of personal loan servicers exiting and getting into the marketplace is laudable – some debtors are not as on top of factors and c) being on the present-day class of earnings-centered repayment is a good program primarily based on the specifics you’ve offered.

Although your debt-to-earnings ratio may perhaps put the kibosh on securing additional credit score, the upside is that you are on an cash flow-pushed reimbursement plan to preserve the regular bill small. There are four earnings pushed reimbursement plans, and they’re made to preserve economical regular monthly payments relative to money. 

As payments are produced – in your scenario, $, but it could be another amount in other scenarios – for 20 or 25 years, dependent on which of the 4 IDR plans you are enrolled in, the leftover harmony will be forgiven. 

Profits in your scenario is unlikely to alter considering the fact that the source is your Social Security reward, and every month payments ought to also keep on being static. As very long as you continue to keep building the $ regular monthly payment your credit score rating must only go up, pros say. The loan is heading to keep on being latest, and you don’t have to get worried about lacking a payment and the damaging repercussions of delinquency. 

There is a achievable caveat. There has traditionally been money tax imposed on forgiven student personal loan credit card debt, but Congress not long ago created forgiveness tax-totally free by 2025 on the federal stage. Assuming which is not extended and you obtain relief for the personal loan after that date, you could have a large tax monthly bill on your arms. 

Be aware although, that plans modify – and modify once again. “There is generally a probability that personal loan forgiveness may possibly no more time be regarded as taxable profits underneath earnings driven reimbursement,”  claims Anna Helhoski, college student loan skilled at NerdWallet. Given your confined income, you could most likely enter into some sort of repayment arrangement with the IRS.

It is also vital to be aware that, in accordance to Leslie Tayne, founder and controlling director of Tayne Legislation Team, personal bankruptcy is possible not a decision here due to the fact it doesn’t seem that a bodily disability is generating operate extremely hard.

As you keep your present repayment strategy, think about these housekeeping chores. Make contact with your new federal personal loan servicer to verify that your account is in get and that “there’s been no hiccups in the transfer,” states Pentis. Assure that you’re nonetheless qualifying for your IDR strategy and are up to date, and check to be positive you are remaining credited for your $ payments (annualcreditreport.com) considering the fact that faults materialize. 

Regarding your final position of your lifetime expectancy: Fiscal sages are in sync about mortality and legal responsibility. If you are the major borrower of a federal scholar personal loan and you go absent, then the debt would be discharged.

Home prices skyrocketed by nearly 19{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} last year

Home prices skyrocketed by nearly 19{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} last year

All locations noticed price gains past 12 months, but increases ended up strongest in the South and the Southeast, every of which have been up in excess of 25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Phoenix, Tampa and Miami described the maximum annual gains among the the 20 metropolitan areas in the index in December. Phoenix led the way for the 31st consecutive thirty day period with prices 32.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} better than the year just before. It was followed by Tampa with a 29.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} raise, and Miami, with a 27.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} boost.

“We keep on to see extremely robust advancement at the metropolis degree,” said Craig J. Lazzara, controlling director at S&P Dow Jones Indices. “All 20 cities observed price tag raises in 2021, and selling prices in all 20 are at their all-time highs.”

Above the past numerous months dwelling prices have been mounting at really significant, but decelerating fees, stated Lazzara. But that deceleration paused in December. Soon after peaking at 19.8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in August, the once-a-year price tag maximize declined as a result of the fall to 18.8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in November, wherever it stayed in December.

Thirty day period-to-thirty day period, house costs in the US Nationwide Index, which handles all 9 U.S. Census divisions, improved 1.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in December from November, just after seasonal adjustment.

Lazzara explained the energy of the US housing sector is getting pushed, in section, by Us residents who made a decision to transfer during the pandemic.

A persistent minimal stock of households dropped to report small ranges in December, according to a modern report from the National Affiliation of Realtors. In the face of continued robust desire, price ranges ended up pushed better. Newly created properties are in the pipeline, but a extensive-jogging shortage, mixed with the lingering consequences of the pandemic indicate it will just take yrs to meet demand from customers.
How much house can I afford?

Nevertheless, increasing mortgage loan prices could begin to quell some of that desire, Lazarra mentioned. “In the quick phrase, we should soon start to see the effects of increasing home finance loan charges on dwelling costs.”

Mortgage loan charges, which had risen only steadily due to the fact August, started to abruptly climb in late December and have considering that risen to virtually 4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for a 30-12 months mounted-price home finance loan.

“A marked adjust could be forward for development as increasing mortgage premiums try to eat into homebuyer buying energy,” mentioned Danielle Hale, Real estate agent.com’s main economist.

Larger home finance loan charges have additional additional than $200 to the monthly expense of a regular for-sale residence since December 2020 — when costs were at all-time lows. Far more than fifty percent of that maximize has occurred around the previous 8 weeks, Hale explained.

“With dwelling charges envisioned to go on rising, even at a slower rate, affordability will increasingly problem 2022 purchasers as a ten years-extensive underbuilding trend has left the housing industry 5.8 million residences brief of home advancement,” said Hale. “At the same time, we hope pandemic developments like workplace versatility and aggressive labor market place situations to give employees the enhance in revenue and broader look for locations they want to navigate a even now-hard housing sector successfully.”

11 Tips To Ensure Your Guest Posts Are Effective Advertising For Your Business

11 Tips To Ensure Your Guest Posts Are Effective Advertising For Your Business

Guest posts are an fantastic way to get publicity for your company. As a result of this kind of articles advertising, you can expect to create yourself as a credible skilled in your industry and get important brand exposure to the publication’s viewers.

On the other hand, it’s not enough to generate an short article mentioning your product or service or provider. With guest posts, it is really vital to strike the appropriate equilibrium in between efficiently advertising your corporation and serving the requirements of the outlet that’s publishing your write-up.

If you have a guest publishing chance coming up, be confident to abide by this practical guidance from the users of Youthful Entrepreneur Council. 

1. Inform A Tale

When producing a guest publish for yet another web page or publication, one matter you need to focus on to make sure it can be effective in “advertising and marketing” is to produce about an knowledge in your business that taught you a lesson. Readers are craving actual tales and details that they can relate to and master from. Storytelling is the best “marketing” there is. – Alfredo Atanacio, Uassist.ME

2. Prioritize Value

In our content material-pushed environment, the additional worth you carry to the readers, the superior advertising and marketing your post gets to be. So my assistance is to quit wondering about it as a piece of marketing and to start off pondering about the most practical, actionable, unforgettable and targeted information that you can give to the audience of the specific publication. When folks really feel witnessed, they turn into faithful. – Daria Gonzalez, Wunderdogs

3. Discover Publications With Comparable Audiences

Start by on the lookout for publications that have the exact concentrate on audience as yours. When that transpires, you don’t have to set in any more effort to encourage your small business. Just concentrate on creating posts about your product or service or services that develop worth for your audience. If you can make useful articles, even the mention of your business or a link to a single of your goods can add large price to your brand. – Josh Kohlbach, Wholesale Suite

4. Provide High quality

The major advertising position of a visitor publish need to be its good quality and helpfulness. There’s not usually a will need to immediately mention your self or your organization at all except you want to convey to a story to illustrate a place. The objective is to create oneself as an authority that likely customers will want to contact. – Kalin Kassabov, ProTexting

5. Construct Authority

When guest submitting for a unique publication, always aim on building substantial-good quality written content that the visitors will uncover engaging, fascinating and beneficial. This will assist you create authority and you’ll very easily be capable to get believe in. Use visitor putting up possibilities to create authority relatively than promote your brand name. In the extensive run, you are going to bring in qualified prospects and enhance conversions. – Thomas Griffin, OptinMonster

6. Leverage Your Region Of Knowledge

The most effective way to boost your business enterprise in a visitor submit is to not be advertising. As an alternative, concentrate on educating your viewers about some thing in the sector they are not aware of. This indicates creating on spots of your genuine expertise and speaking from serious-lifestyle examples. Also, constantly try to remember to have a url back to your web-site somewhere in the articles. – Kelsey Raymond, Affect & Co.

7. Contain Authentic-Daily life Illustrations

Authentic-lifestyle examples constantly entice folks and resonate with them. So, when you compose a guest put up, be guaranteed to consist of a scenario examine or a achievement tale. This is a fantastic way to market your company in an indirect way. You might be stating the details and showing your audience what your small business can do. With success stories and illustrations, you can establish your model through guest posts. – Syed Balkhi, WPBeginner

8. In excess of-Supply

Considering the fact that most guest posts expressly prohibit promotion, the most powerful way to obtain notice for your model or company is to be outstanding with your message. If you happen to be composing an academic piece, give 110{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. Provide the viewers with your most effective stuff. Then, make certain that when a person searches your identify on the net, you or your firm are at the prime of the webpage. – Jared Weitz, United Capital Resource Inc.

9. Show The Correct Individuals

Marketing will work only when it’s revealed to the correct persons. So the No. 1 detail to consider when crafting a guest write-up for a publication (specifically if your intention is advertising) is the audience. Who are the audience? Do they in shape into your consumer persona? If not, you will find not substantially cause to go ahead due to the fact even if you get the views, there would not be any further more action. – Solomon Thimothy, OneIMS

10. Consider Visitor Posts Portion Of Your Portfolio

Even though you are crafting a submit for anyone else’s web page, it must continue to be considered a component of your greater overall body of work. What I signify by this is that you shouldn’t overlook about the written content of your guest posts, but take into account them portion of a greater dialogue you’re getting through all the content you share on the internet. This will also inspire additional engagement with readers on these other web pages. – Bryce Welker, Real Estate Schooler

11. Present Actionable Advice

I have discovered that supplying viewers with actionable information and applicable hyperlinks potential customers to more robust guest put up engagement. You’ll want to take into account the problems your audience will come upon and present crisp advice that they can use to remedy their troubles. If you can enable men and women by means of your guest article, they are significantly additional possible to test out your site. – John Brackett, Smash Balloon LLC

Charter sharpens its business services edge

Charter sharpens its business services edge

&#13
Spectrum Organization, the business solutions device of Constitution Communications, is broadening the scope of Managed Network Edge (MNE), an giving released about a 12 months back and underpinned by Cisco’s Meraki platform. &#13
&#13

&#13
Spectrum Enterprises’ initial MNE providing blended baseline connectivity (wired and wireless) and switching with stability and managed firewall protection, Wi-Fi and LAN management, together with support for secure community cameras. The most current update, which even now faucets into the MNE portal, provides support for distant access personnel and teleworkers together with a Digital Edge company that allows company prospects to link securely to numerous cloud support suppliers, such as AWS, Google Cloud and Microsoft Azure. &#13
&#13

Charter sharpens its business services edge

Charter pulled in $1.69 billion in professional companies income in Q4 2021, improving on a year-in the past full of $1.62 billion.
&#13
(Supply: Charter Communications)

&#13
&#13
&#13
&#13

&#13
Charter released MNE very last year as it grew ever more clear that IT leaders at tiny and midsized corporations, as nicely as enterprises with multiple department places, desired supplemental instruments to smooth out functions all through a pandemic that forced men and women to do the job from residence. &#13
&#13

&#13
“They had been getting to rethink their network,” Bob Schroeder, vice president, company details products management at Spectrum Enterprise, defined. “They experienced to rapidly adjust how they accommodated get the job done from house and had to put some of their initial courses on keep to tackle digitization and their journey into this new entire world.” &#13
&#13

&#13
This latest wave of bolt-ons supports remote accessibility, enabling buyers to securely join to the company network when they are on the go. Schroeder claimed Spectrum Company is among the 1st to enable that by means of Cisco’s AnyConnect Safe Mobility computer software. &#13
&#13

&#13
The new teleworker characteristic is identical to distant accessibility but focuses on individuals who are operating from property on a more everlasting basis, these kinds of as make contact with middle employees. Instead of supporting that functionality through application, Spectrum Organization using a components consumer – Cisco’s Meraki Z-Series cloud-managed teleworker gateway. &#13
&#13

Cisco's Meraki Z-Series cloud-managed teleworker gateway. 
 
(Source: Charter and Cisco. Used with permission.)

Cisco’s Meraki Z-Series cloud-managed teleworker gateway. &#13

&#13
(Resource: Charter and Cisco. Utilised with permission.)

&#13
&#13
&#13
&#13

&#13
The Virtual Edge enhancement allows Spectrum Business consumers to build a secure connection from their SD-WAN to AWS, Azure or Google Cloud, Schroeder mentioned. &#13
&#13

&#13
SMB and enterprise&#13

&#13
Spectrum Business is pitching the new functions to its existing foundation as very well as new consumers in a current market that consists of the two midsized businesses and massive business customers with a number of branch places. Spectrum Organization is offering them instantly and by means of its telecom company distributors. &#13
&#13

&#13
“You will find no enterprise out there today that isn’t going to need to have some kind of these abilities,” Schroeder mentioned. &#13
&#13

&#13
Spectrum Organization is launching these enhancements as Charter begins to see business companies expansion rebound a bit after the pandemic strike businesses difficult. Charter created about $1.69 billion in industrial providers earnings in Q4 2021, ahead of a 12 months-back total of $1.62 billion. Company-relevant revenues in Q4 2021 strike $643 million, up from $623 million in the yr-in the past quarter. &#13
&#13

&#13
Linked posts:
&#13

&#13

&#13
— Jeff Baumgartner, Senior Editor, Light Examining

&#13
&#13