JDE Selects Orange Business Services for Future-Proof and Scalable Connectivity Infrastructure to Support Global Business Expansion

JDE Selects Orange Business Services for Future-Proof and Scalable Connectivity Infrastructure to Support Global Business Expansion

AMSTERDAM & PARIS–(Business enterprise WIRE)–Jacobs Douwe Egberts (JDE), a international coffee business, has deployed Orange Organization Solutions secure end-to-conclude connectivity alternatives for much more than 120 spots throughout the world based on Adaptable SD-WAN. The versatile infrastructure has aided support the company’s formidable world expansion strategies and digital transformation

JDE wished a remarkably scalable infrastructure that could satisfy both of those its bespoke specifications and increasing small business needs into the potential. Orange Small business Companies has implemented a world-wide connectivity solution making use of managed Versatile SD-WAN across 40 nations around the world in Europe, Africa, Asia Pacific and Latin The usa. In addition, Orange gives a assortment of managed network security providers throughout the core infrastructure of JDE’s info facilities situated in Amsterdam, Sao Paulo and Singapore, together with cloud-based security options.

Flexible SD-WAN proves its flexibility

Adaptable SD-WAN demonstrated its value early on by supporting JDE’s merger and acquisition functions following its not long ago obtained organization in the Asia Pacific area. JDE quickly built-in the new groups and sites into its international IT infrastructure, allowing for them to entry corporate programs and the network. This saved a considerable quantity of time and authorized for speedy onboarding.

“Orange Enterprise Companies has aided us make a powerful, resilient, and over all scalable and secure connectivity infrastructure. This has speedily set us on a solid transformational route, furnishing the electronic and versatile providers our company needs to achieve our enlargement plans,” claimed Alexander Min, Global IT Director, Global Data Units at JDE. “In addition, we have found an enhanced conclusion-consumer encounter, specifically in distant locations.”

“JDE is benefiting from a protected and agile infrastructure constructed on our Evolution System connectivity, cloud and protection abilities. This approach is developed to accelerate its electronic transformation and propel its business forward. The organization has already observed major overall performance positive aspects with the potential to quickly convert up and insert new internet sites to its community, and this is with any luck , just the beginning of a fruitful partnership,” said Nemo Verbist, Senior Vice President Europe for Orange Enterprise Providers.

About Orange Enterprise Solutions

Orange Small business Products and services is a network-native electronic services corporation and the world wide business division of the Orange Team. It connects, guards and innovates for enterprises about the entire world to help sustainable company progress. Leveraging its connectivity and procedure integration know-how throughout the digital price chain, Orange Organization Services is well positioned to guidance global corporations in places these kinds of as computer software-described networks, multi-cloud expert services, Facts and AI, intelligent mobility products and services, and cybersecurity. It securely accompanies enterprises across every single phase of the details lifecycle stop-to-stop, from assortment, transportation, storage and processing to assessment and sharing.

With corporations flourishing on innovation, Orange Small business Services spots its consumers at the heart of an open collaborative ecosystem. This involves its 29,100 staff members, the belongings and abilities of the Orange Group, its technologies and small business partners, and a pool of finely selected start out-ups. Much more than 3,000 multinational enterprises, as properly as two million specialists, businesses and regional communities in France, place their have confidence in in Orange Company Solutions.

For extra information, go to www.orange-business.com or abide by us on LinkedIn, Twitter and our weblogs.

Orange is a person of the world’s main telecommunications operators with revenues of 42.5 billion euros in 2021 and 286 million buyers around the globe at 30 September 2022. Orange is outlined on the Euronext Paris (ORA) and on the New York Inventory Trade (ORAN). In December 2019, Orange offered its new “Engage 2025” strategic plan, guided by social and environmental accountability. When accelerating in advancement areas, these types of as B-to-B services and placing information and AI at the heart of innovation, the total Orange Team will be an appealing and liable employer.

Orange and any other Orange product or support names incorporated in this substance are logos of Orange or Orange Brand Expert services Limited.

Vermonters strongly endorse personal finance education

Vermonters strongly endorse personal finance education
Poll Finds Overwhelming Positive Support; Civics Education Also Important to Residents

Vermont Business Magazine More than nine out of 10 Vermont residents believe that personal finance education is an important subject that should be taught in high school. This overwhelming finding emerged from a statewide poll of 541 voters conducted this month by Public Policy Polling for the Center for Financial Literacy at Champlain College.

John Pelletier, director of the center, notes that the poll shows 93 percent of Vermont residents agree that a personal finance course should be offered in high school. Pelletier also notes that 88 percent of Vermont adults believe that guaranteed access to a personal finance course for all Vermont high school students is urgently needed. Yet, despite these views, currently, few Vermont high school students have guaranteed access in high school to a full-semester course in personal finance prior to graduation.

See results below.

Pelletier believes that this poll data will help state education policy makers, legislators, the state board of education and the agency of education make informed decisions regarding personal finance education in Vermont’s public schools.

“Personal finance education changes behaviors in positive ways,” says Pelletier. “Research demonstrates that high school students with this knowledge improve their own money management practices, and share this learning with their families, resulting in improved parent knowledge, saving and spending behaviors.”

He also notes that individual financial literacy means healthier family balance sheets, which in turn builds a stronger state economy. And studies like this one show employees who are money savvy are happier with and remain longer in their jobs.

Courtney Poquette, who teaches personal finance at Winooski High School, says she and her students believe it is the most important course in high school in 2023. “It’s the one course Vermont students will take in high school that they will use every day for the rest of their lives.” Her former student David Klinker, now a student at Champlain College, agrees, and wrote a commentary piece in VT Digger outlining how the course completely changed his life.

Pelletier says that there is a national movement to bring the subject to more high schools, since just 1 in 4 students nationwide currently have access to a guaranteed course.

Personal finance is also an issue of equity, says Pelletier. He points to this 2022 study by Next Gen Personal Finance, which shows that in states that do not guarantee access to personal finance education those who arguably need this training the most are the least likely to receive it. In these states, which includes Vermont, wealthy and less diverse high schools are approximately three times more likely to guaranteed access to this training than very poor and very diverse high schools in our nation.

On the positive side, he notes that last year, six more states passed legislation guaranteeing a personal finance course, bringing the total number of states with such guarantees to 17. He also notes that it is expected that a dozen more states will consider this change in 2023, Vermont being among them. 

In the state poll, 87 percent of respondents indicated that high school personal finance education was very important and 12 percent said it was somewhat important. Ninety-three percent of respondents said a course covering budgeting, investing, taxes and saving should be offered in high school, while 83 percent felt the course should be guaranteed for all students.

Informed that just 12 percent of high school students in Vermont were guaranteed a personal finance course, 88 percent of poll respondents said a law requiring such a course is an urgent issue. Currently in Vermont, only Black River, Lamoille, Milton, Missisquoi, Spaulding, Vergennes and Winooski high schools provide student with guaranteed access to personal finance in high school. BFA St. Albans plans on joining this list of guaranteed access high schools.

A bill calling for a course in civics was introduced in the last session of the Vermont legislature, so the poll also included questions on this issue. Eighty four percent of respondents believe a course in civics—covering the Constitution and matters related to the U.S. government—is very important, and 92 percent indicated that such a course should be taught. Eighty-five percent of respondents believe civics should be a guaranteed course.

Pelletier notes that personal finance education doesn’t stop in high school. A 2019 U.S. Treasury Department report on financial literacy best practices for colleges included the recommendation that colleges “should require mandatory courses to teach students financial concepts and skills.” 

Champlain College is one of the few colleges that requires its on-campus undergraduate students to take personal finance training as a graduation requirement. The college’s InSight Program teaches students fundamental personal finance skills including how to negotiate your salary (including benefits and evaluation of compensation packages), create and follow a budget, establish credit, manage debt, invest your money, and more. 

“Champlain equips its students with the life skills needed to complement academic and career success,” said Olivia Vittitow, the InSight Program Manager. “Embedding four years of financial, personal, and wellbeing-focused workshops, seminars, and one-on-one coaching as a part of our undergraduate requirements has resulted in Champlain graduates avoiding student loan default issues and enjoying financial stability after graduation.”

Evidence that Financial Education Improves Behavioral Outcomes

Evidence-Based Policy & Implementation Resources

Evidence that Financial Education Improves Behavioral Outcomes

a) The Effects of K-12 Financial Education Mandates on Student Postsecondary Education Outcomes

Research from the National Endowment for Financial Education. Financial education mandates have positive impacts on student borrowing behaviors across all income groups. States with personal finance graduation requirements have students with a higher incidence of applying for financial aid, a lower incidence of borrowing from private student lenders, a higher incidence of receiving grants and federal aid, and a lower likelihood of carrying credit card balances.

b) Does Financial Education Impact Financial Literacy and Financial Behavior, and If So, When?

Most earlier studies of financial education rely on outdated financial education requirements. Kaiser and Menkhoff show significant positive effects of financial education on both financial literacy (knowledge) and financial behavior. This meta-analysis corrects an often cited meta-analysis from Fernandes et. al. (2014), adding additional interventions and a more rigorous statistical methodology to make its conclusions. Compelling, rigorously critiqued evidence of the need for “just in time” financial education for high school students.

c) Financial Education Matters: Testing the Effectiveness of Financial Education Across 76 Randomized Experiments

We study the rapidly growing literature on the causal effects of financial education programs in a meta-analysis of 76 randomized experiments with a total sample size of over 160,000 individuals. The evidence shows that financial education programs have, on average, positive causal treatment effects on financial knowledge and downstream financial behaviors. Treatment effects are economically meaningful in size, similar to those realized by educational interventions in other domains, and are at least three times as large as the average effect documented in earlier work. These results are robust to the method used, restricting the sample to papers published in top economics journals, including only studies with adequate power, and accounting for publication selection bias in the literature. We conclude with a discussion of the cost-effectiveness of financial education interventions.

d) Does State-Mandated Financial Education Affect High-Cost Borrowing? (UPDATED 2019)

“…young adults who were required to take personal finance courses in high school were significantly less

likely to borrow payday loans than their peers who were not. These effects do not significantly differ by race/ethnicity or gender, suggesting that financial education may be useful regardless of demographics.” 

e) Retirement Savings with School-Based Financial Education

Students’ financial literacy performance is significantly associated with their schools’ and teachers’ characteristics, both positive and negative. Students who attend a school with adequate teaching materials and competent teachers — those who demonstrate control over their classroom and try to actively engage with students — are more likely to perform at the two highest levels on the PISA financial literacy test.

f) Optimal Financial Knowledge and Wealth Inequality

Financial literacy plays a key role in explaining inequality. Different levels of financial knowledge early in life have important implications for how much people will save. Adding financial knowledge to life cycle models permits a more accurate rendering of a world where consumers must cope with complex financial markets and must save so as to provide for their own retirement.

g) The impact of high school financial education: experimental evidence from Brazil

This paper studies the impact of a comprehensive financial education program spanning six states, 868 schools, and approximately 20,000 high school students in Brazil through a randomized control trial. The program increased student financial knowledge, increased saving rates for purchases, better likelihood of financial planning, and greater participation in household financial decisions by students. “Trickle-up” impacts on parents were also significant, with improvements in parent financial knowledge, savings, and spending behavior. The study also finds evidence that the program affected students’ inter-temporal preferences and attitudes.

h) Personal Finance Education Mandates & Student Loan Repayment

“Students with higher-income parents respond by adjusting borrowing, reducing median balances by 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. By contrast, first-generation and low-income borrowers bound by mandates did not significantly adjust borrowing, but were nonetheless more likely to pay down balances..”

i) Can financial literacy reduce domestic violence?

“Yes. Using data on more than 3.7 million intimate partner violence (IPV) incidents between 1994 and 2016, and exploiting the staggered introduction of state-mandated personal finance high school graduation requirements across U.S. states for identification, we show that improvements in women’s financial literacy can significantly reduce the rates of violence against women perpetrated by their male partners. We conservatively estimate a reduction in violence by between 3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and 11{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. Our evidence points to financial literacy deterring financial abuse, thereby empowering women to leave abusive relationships earlier or by preventing the first incident from ever occurring.”

Evidence-Based Policy & Implementation Resources

a) Transforming the Financial Lives of a Generation of Young Americans POLICY RECOMMENDATIONS FOR ADVANCING K-12 FINANCIAL EDUCATION

What we propose here is a comprehensive strategy to impart personal financial management skills to young people while they are in school. Recommendation 1: Introduce key financial education concepts early and continue to build on that foundation consistently throughout the K-12 school years. In addition, CFPB encourages states to make a stand-alone financial education course a graduation requirement for high school students. Recommendation 2: Include personal financial management questions in standardized tests. Recommendation 3: Provide opportunities throughout the K-12 years to practice money management through innovative, hands-on learning opportunities. Recommendation 4: Create consistent opportunities and incentives for teachers to take financial education training with the express intention of teaching financial management to their students

Consumer Financial Protection Bureau. (2013). Transforming the Financial Lives of a Generation of Young Americans POLICY RECOMMENDATIONS FOR ADVANCING K-12 FINANCIAL EDUCATION. [online] consumerfinance.gov. Available at: http://files.consumerfinance.gov/f/201304_cfpb_OFE-Policy-White-Paper-Final.pdf

b) Final Report – President’s Advisory Council on Financial Capability

The Council acknowledges that financial capability must be woven into the fabric of our lives—into our homes, our schools, our workplaces, our communities, even the design and regulation of the financial products and services we use. 

United States Treasury. (2013). Final Report President’s Advisory Council on Financial Capability. [online] treasury.gov. Available at: https://www.treasury.gov/resource-center/financial-education/Documents/PACFC{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20final{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20report{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20revised{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}2022513{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}288{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}29_R.pdf

c) Financial Capabilities of College Students from States with Varying Financial Education Policies

Well-educated students exhibit positive financial behaviors. After analyzing data from 15,797 college students, Gutter found that students from states where a financial education course was required had the highest reported financial knowledge and were more likely to display positive financial behaviors and dispositions. Compared to other students, these young adults were: More likely to save; Less likely to max out their credit cards; Less likely to make late credit card payments; More likely to pay off credit cards in full each month; Less likely to be compulsive buyers; More likely to be willing to take average financial risk

https://www.nefe.org/_images/research/Financial-Education-Mandates-Report/Financial-Education-Mandates-Report-Executive-Summary.pdf

d) Financial Education in High Schools Across America

State-level embedded course requirement mandates do not result in full compliance. While this lack of compliance could be because course catalog descriptions do not detail financial literacy instruction in all schools, it could also be because state departments of education have trouble auditing embedded course mandates. In our estimate, only 43{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} within states that have embedded course mandates have either a standalone or embedded course requirement.

e) Financial Literacy Subject Survey

Between July 15th and 17th, 2017 the National Financial Educators Council asked 5,123 young adults, “What high school-level course would benefit your life the most?” Respondents chose money management more often than math, science, and social studies:

  • 49.97{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Money Management (Personal Finance)”
  • 18.25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Mathematics (Algebra, Geometry)”
  • 14.43{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Social Studies (History, Government)”
  • 17.35{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} selected “Science (Biology, Chemistry)”

State by state results are available: NFEC Survey: “Should High Schools Require Financial Literacy?” 

NFEC. (2017). Financial Literacy Subject Survey. [online] Available at: https://www.financialeducatorscouncil.org/Financial-literacy-subject-survey/

f) A review of youth financial education: Effects and Evidence

“This report reviews current research and reporting in the field, and is intended to inform policymakers, practitioners, financial educators, and researchers of the current state of rigorous evidence on financial education in schools”… “This report features studies that (1) evaluate youth financial education programs in schools, (2) have a causal interpretation evidenced by a randomized controlled trial, natural experiment setting, or a valid pre-post study design, and (3) have been published in peer-reviewed academic journals or as reviewed working papers. Note that the studies predominantly relate to school based programs, as this is the context in which most youth financial education research has occurred.”

  • “Well-implemented state financial education mandates led to a clear improvement in financial behaviors.”
  • “Many U.S. financial education programs improve financial knowledge for students, though effect sizes vary based on the population served, amount of instruction time, and topics covered.”
  • “Other countries have used more widespread randomized controlled trials to study the effects of programs as they embed and expand them broadly. Those studies also provide useful information.”
  • Consumer Financial Protection Bureau. (2019). A review of youth financial education: Effects and Evidence. [online] consumerfinance.gov. Available at: https://files.consumerfinance.gov/f/documents/cfpb_youth-financial-education_lit-review.pdf

g) Digital vs. in-person financial education: What works best for Generation Z?

“Nowadays, financial literacy is one of the most important skills that can be acquired by a tech-savvy Generation Z student. In order to understand what format of financial education works best for Generation Z, we set up an experiment that involved implementing a financial education program called “Futuro Sicuro” with a sample of 650 High School students in Italy. The program allowed us to gather data from two treatments at the class level, namely 1) a traditional financial education simplified program with the presence of a financial advisor, and 2) a digital financial education program using web-based applications based on learning-by-playing concepts. The two treatments were associated with different costs but showed similar effects: three weeks after their conclusion, we find that both courses did increase actual financial knowledge and the results also aligned with participants’ realistic assessments of their own financial skills. A follow-up study also reveals the persistence of these effects three months later for the traditional course.”

h) Best Practices Implementing Financial Education in High Schools

“…breaks the implementation into eight stages: (0) building a coalition, (1) crafting and passing either legislation or administrative rule change, (2) constructing an implementation plan, (3) funding, (4) teacher professional development, (5) developing standards and selecting course resources, (6) teacher endorsement models, and (7) auditing and creating a feedback loop for continuous improvement.”

Urban, Carly (2022). Best Practices Implementing Financial Education in High Schools [online] Available at: https://papers.carlyurban.com/MTBestPracticesReportFINAL.pdf

About the Center for Financial Literacy: Established in 2010, Champlain College’s Center for Financial Literacy (CFL) was designed to promote and develop financial literacy skills among individuals, allowing them to make more sound decisions about spending, credit, debt, investments, and complex financial situations such as buying a home and saving for retirement. The CFL is nationally acclaimed for its efforts to increase the personal finance knowledge of our citizens and has become the credible, go-to source for national media coverage of financial literacy.

About Champlain College: Founded in 1878, Champlain College is a small, not-for-profit, private college in Burlington, Vermont, with additional campuses in Montreal, Canada, and Dublin, Ireland.  Champlain offers a traditional undergraduate experience from its beautiful campus overlooking Lake Champlain and a broad portfolio of online degrees and certificates through Champlain College Online. The College is known for its distinctive and innovative approach to career-focused education and its “upside-down” curriculum, which help students be: “Ready for Work. Ready for Life. Ready to Make a Difference.” Champlain ranks in multiple categories of U.S. News and World Report’s “Best Colleges,” including Best Value Schools, Best Colleges in the North, Best Colleges for Veterans, and Top Performers on Social Mobility. Champlain was also listed among The Princeton Review’s “The Best 388 Colleges” in 2023 and was recognized as a 2022. College of Distinction for its “Engagement, Teaching, Community, and Outcomes.” For more information, visit www.champlain.edu.

January 17, 2023, Burlington, VT — Center for Financial Literacy

Vermonters strongly endorse personal finance education

4 Tips For Building A ‘Culture Of Collaboration’ Within Your Business

4 Tips For Building A ‘Culture Of Collaboration’ Within Your Business

Though there are lots of elements that can enjoy a part in making the great business culture, number of issues can prove additional critical than setting up a society of collaboration. In simple fact, exploration from Stanford reveals that performing in a collaborative setting tends to make workforce 50{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} a lot more successful at job completion, though also boosting their engagement and commitment.

It might sound cliche, but it is correct: your staff is the lifeblood of your small business. No issue what your field, creating a balanced office environment lifestyle driven by collaboration is critical to driving results for your firm. Optimistic work cultures have been observed to improve productiveness, engagement, retention and other important data.

Building a collaborative culture within just your enterprise is nicely truly worth the exertion — and with the right procedures, you can promptly reinforce this element of your function.

1. Set up a Basis of Have faith in and Communication

As a leader, you established the tone for how collaboration can be carried out within just your corporation. Comparable to creating powerful partnerships with other enterprises, an inside collaborative lifestyle requirements a strong foundation of consistent communication and transparency.

This doesn’t indicate that each and every employee desires to know the precise information of your company’s financials. But it does necessarily mean that you share the data every person desires to do their careers perfectly, fairly than hoping to unnecessarily restrict entry to data. A transparency motivation matrix can assist your staff determine what desires to be shared, and with whom.

Creating a consistent cadence for sharing facts can also be practical. Even a thing as straightforward as weekly e-mail updates or check-in meetings with the complete group can keep anyone on the same website page and provide extra likelihood to collaborate.

2. Make Alternatives for a Tradition of Collaboration

Collaboration doesn’t take place by accident — especially if you are still in the center of transitioning absent from a system the place workforce generally work on impartial projects.

As a chief, you can foster collaboration by deliberately designing jobs that demand a staff of employees. This can be in particular handy when you develop cross-functional undertaking forces, which demand users of distinct departments to function with each other on a shared target or initiative. Even anything as simple as assigning a handful of team users to perform collectively on a undertaking can be of use.

As the saying goes, “Knowledge is the best teacher.”

These early collaborative activities that you produce for your crew may possibly call for more advice, but they will provide as the best screening floor for mastering to function collectively. As your group will become more snug with this approach, they will be better geared up for cross-functional duties, and will be extra keen to collaborate in scaled-down techniques on their unique responsibilities.

3. Use Engineering to Make Collaboration Seamless

You’re hardly alone in your quest to generate a culture of collaboration. For illustration, a vast variety of know-how applications these kinds of as Slack, Asana and Mural are now accessible to streamline and simplify the collaborative procedure, regardless of regardless of whether you all share the identical business office room or operate remotely. 1 pattern several companies are turning to is the use of “no-code” and “low-code” company system management platforms that can be uniquely tailored for individual groups.

Jason Drinen, follow direct at ExpressAbility, describes how tailor made organization applications can go a long way in driving extra meaningful collaboration. “Processes and productivity put up with when teams do not have a way to collaboratively work, have visibility to procedures or a way to conveniently make their particular person contributions. To stay clear of that, small business tools should be customized to in shape the workforce so collaboration can be definitely seamless. When companies leverage minimal-code BPM platforms, they can obtain speedy growth of software package that fits duties to people, somewhat than the other way close to. This leaves firms better equipped to answer to a dynamic marketplace with collaboration that definitely boosts their productiveness.”

4. Assess and Revise

As with any other adjust or initiative your small business undertakes, you should really on a regular basis evaluate your processes for constructing a tradition of collaboration. Right before, for the duration of and after you start emphasizing collaboration, you need to examine your company processes to establish places that are as well individual-oriented, as well as locations wherever your existing techniques or procedures make collaboration difficult.

The feedback of your employees will be crucial in this exertion. Amassing opinions from your workforce can assistance you determine shortcomings in your effort and hard work to build a collaborative society, as properly as alternatives for larger collaboration. Superior still, the method of gathering responses in alone will strengthen collaboration by serving to your team develop more relaxed about speaking and coming up with options with each other.

Normally, when you’ve carried out your possess assessments and collected opinions from this workforce, the following action is to revise your processes so you can make it easier to collaborate. Make positive that the “revision” process is collaborative in and of alone, collecting insights and suggestions from all stakeholders to be certain your new answers are genuinely productive for every person.

Realize More With a Tradition of Collaboration

Setting up a lifestyle of collaboration in your organization may perhaps need a honest amount of work, in particular if your group has earlier focused on unique-oriented tasks.

But as you actively try to build a far more collaborative culture, your team will be equipped to thrive like by no means in advance of. From unlocking creative imagination to just strengthening gratification and engagement at function, a collaborative lifestyle will aid you get much better results from your group — and on your own.

Advance tax refund provider raises loan limit to $7,000 amid raging inflation

Advance tax refund provider raises loan limit to ,000 amid raging inflation

More Americans may seek advances against their income tax refunds this tax season as rising prices strain budgets and government stimulus programs end.

Santa Barbara Tax Products Group increased the size of its advance refund loans to $7,000 from $6,000 and extended loan availability by two weeks to Mar. 17. The firm processes 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of refunds issued by the IRS and manages refund loans for some tax preparers and accounting firms.

The increases come as a survey last month by tax preparation firm H&R Block showed 69{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of employed individuals are “extremely concerned” about inflation.

Those over age of 40, women, single moms, and people with fair to poor credit are most likely to have experienced a worsened financial situation, with fewer work hours, no raises, and higher prices primarily to blame.

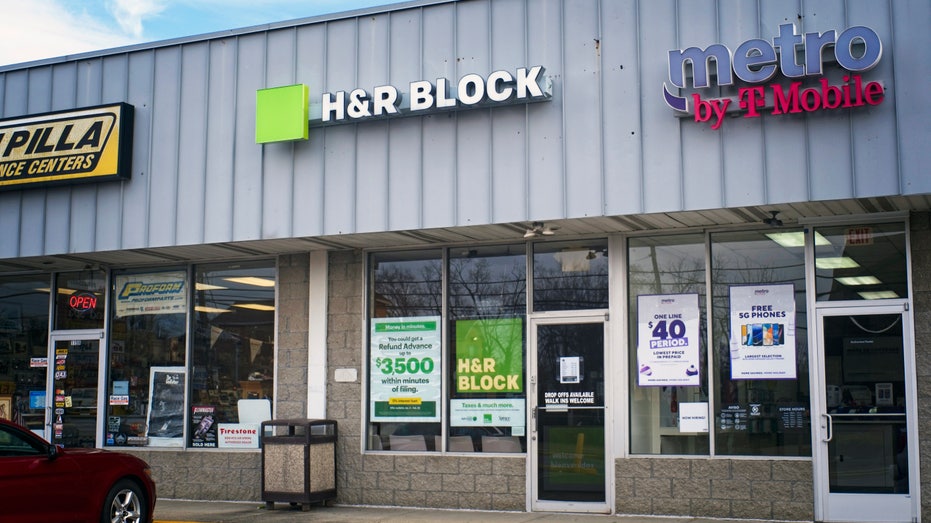
H&R Block store exterior in shopping plaza

Exterior of H&R Block store, Bellmawr, N.J., Jan. 7, 2023. (Fox News)

H&R Block in among tax preparers and tax software companies that offer loans against anticipated tax refunds.

“For many, this is their single largest financial event of the year,” H&R Block told FOX Business. Last year over 96 million filers received refunds averaging $3,039, according to IRS data.

Some taxpayer cannot wait for their money. The IRS aims to issue most refunds in fewer than 21 days for taxpayers who file electronically and choose direct deposit. However, the service will not begin accepting returns until Jan. 23.

“One big change this year is that most temporary COVID-19 relief measures and programs have expired,” says H&R Block Chief Tax Officer Kathy Pickering. “These include the Recovery Rebate Credit, the expanded Earned Income Tax Credit, Child Tax Credit, and dependent care credit for individuals.”

For example, President Joe Biden’s American Rescue Plan increased the child tax credit to $3,000 for each qualifying child between ages 6 and 17 and to $3,600 for each qualifying child under age 6 — but only for 2021. The law also offered early payments of up to 50{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the estimated amount.

For the 2022 tax year, there were no advance payments, and the credit dropped back to $2,000 per child.

Many tax refund loans come with no finance charges or loan fees. However, you may pay a tax preparation or software fee and/or an electronic filing fee.

TRUMP TAX RETURNS: IRS HOBBY RULES PUT $1.1M OF DEDUCTIONS AT RISK

H&R Block Refund Advance ($3,500)

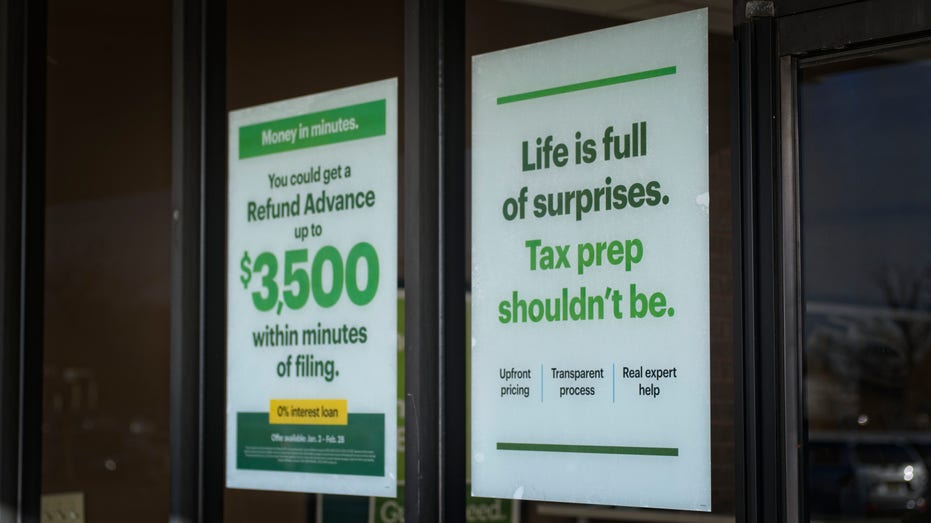
H&R Block window signs

Signs in an HR Block storefront window advertising tax refund advance loans and tax preparation, West Berlin, N.J., Jan. 8, 2023. (Fox News)

Refund Advance through Pathward, N.A. offers loans of $250, $500, $750, $1,250 or $3,500. You can apply through Feb. 28. If approved, the funds are available on a prepaid debit card within minutes after your taxes are filed. The loan has no finance charge or loan fees and 0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} annual percentage rate (APR).

Ticker Security Last Change Change {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}
HRB H&R BLOCK INC. 37.85 +0.26 +0.69{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

IRS SAYS AVOID ‘SURPRISE’ TAX BILL BY MAKING FOURTH-QUARTER PAYMENT BEFORE JAN. 17

TurboTax Refund Advance ($4,000)

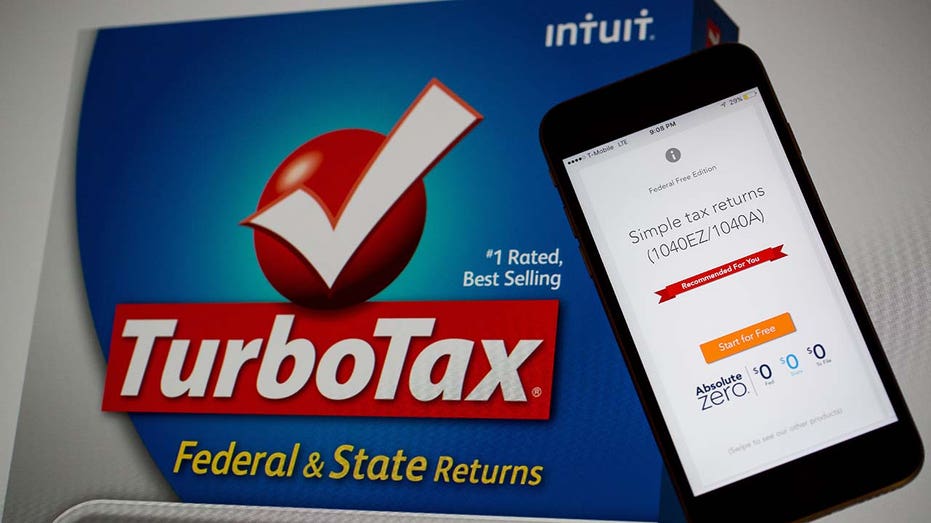
TurboTax intuit

The Intuit Inc. TurboTax application is demonstrated on an Apple Inc. iPhone 6s in this arranged photograph taken in New York, U.S., on Feb. 15, 2016. (Photographer: Michael Nagle/Bloomberg via Getty Images / Getty Images)

Intuit’s TurboTax offers loans through First Century Bank, N.A. in 10 amounts from $250 to $4,000 for filers with refunds of at least $500. If approved, your money will be deposited into a Credit Karma MoneySpend (checking) account as quickly as one minute after the IRS accepts your e-filed federal return. Funds are accessible online through a virtual card and a physical Visa debit card. Refund Advance is available through Feb. 15. The loan has a 0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} APR and $0 loan fees.

Ticker Security Last Change Change {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}
INTU INTUIT INC. 393.21 -3.49 -0.88{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

IRS SAYS YOUR TAX REFUND COULD BE SMALLER IN 2023 — HERE’S WHY

Jackson Hewitt Tax Refund Advance and No Fee Advance ($4,500)

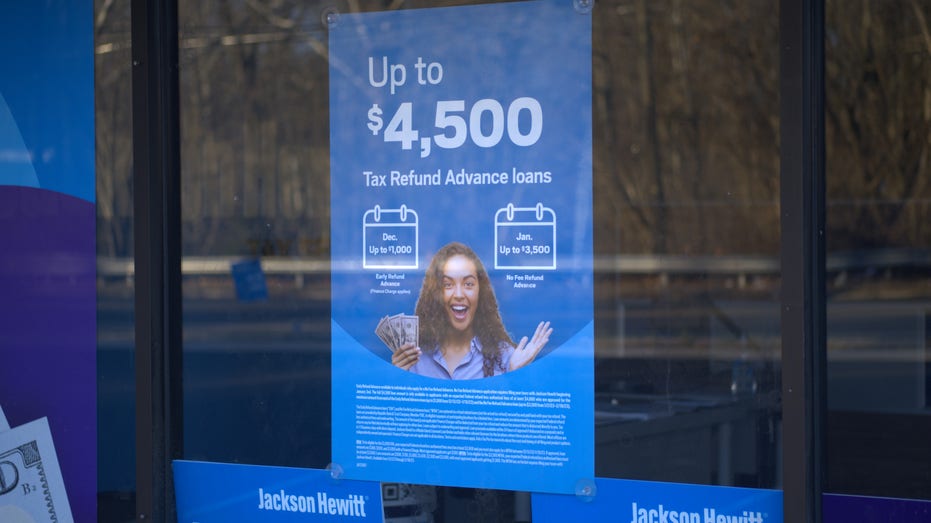
Jackson Hewett tax refund advance loan poster

Tax refund advance loan poster in a Jackson Hewitt store, Pine Hill, N.J., Jan. 8, 2023. (Fox News)

Jackson Hewitt offers two loan products.

Tax Refund Advance loans of $300, $500 and $1,000 were available through Jan. 15. They were limited to borrowers who also apply for a No Fee Refund Advance. 

Both loans are provided by Republic Bank & Trust. If approved, loan proceeds will be available within 24 hours if disbursed on an American Express prepaid card or in 1-5 business days with direct deposit.

TRA loans come with a 6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} finance charge, so a $500 loan would include a $30 charge, equal to an APR of 34.22{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

No Fee Advance loans are available in amounts between $500 and $3,500. The offer is available though Feb. 19. The loan has no fees and 0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} APR.

STILL MISSING YOUR TAX REFUND? THE IRS WILL SOON PAY YOU 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} INTEREST

Fast Cash Advance ($7,000)

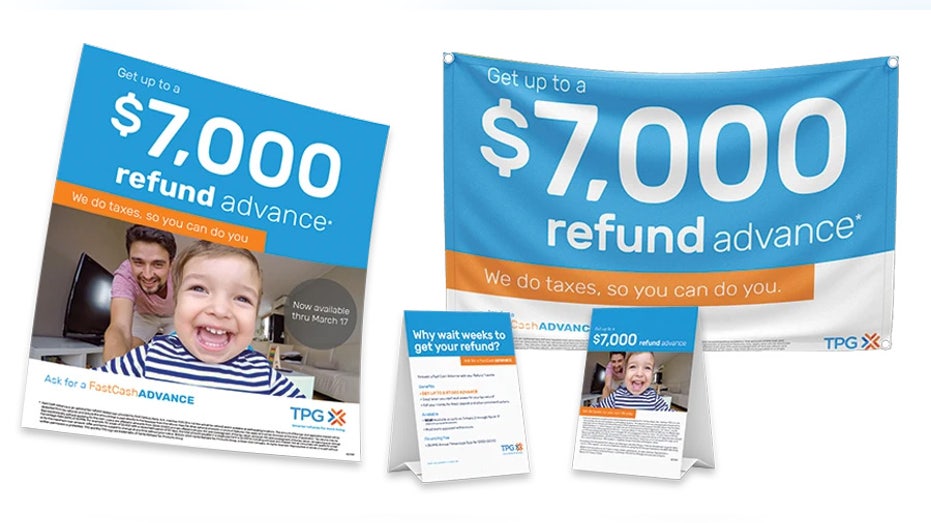
Tax refund loan poster, banner and tent cards

Green Dot’s Santa Barbara Tax Products Group tax refund loan poster, banner and tent card marketing materials for tax professionals. (Santa Barbara Tax Products Group)

Tax preparers can offer Fast Cash Advance loans through First Century Bank in amounts between $500-$7,000. If approved, your money will be available by check, direct deposit or GO2bank Visa debt card.

All loans have an APR of 35.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Ticker Security Last Change Change {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}
GDOT GREEN DOT CORP. 17.54 -0.34 -1.90{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

GET FOX BUSINESS ON THE GO BY CLICKING HERE

The steep plunge in used car prices — what it means, and what’s ahead

The steep plunge in used car prices — what it means, and what’s ahead


New York
CNN
 — 

Monitoring utilised automobile rates is enough to give any individual whiplash.

Since the get started of the pandemic and the resulting disruptions to new motor vehicle provide chains to start with sent charges soaring, employed vehicle costs posted their most significant once-a-year improve on file – up 45{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in the 12 months ending in June 2021, according to the Shopper Price tag Index – prior to swinging to a 12-month drop of 8.8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in the most recent examining for December.

That was the most significant 12-thirty day period plunge in costs for applied vehicles since June 2009, when Normal Motors and Chrysler have been the two in individual bankruptcy proceedings and the economic climate was hemorrhaging a 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}-million careers a thirty day period.

“It was a totally wild ride,” explained Ivan Drury, director of insights at Edmunds.com Inc., an on the internet methods for inventory and information and facts on vehicles.

Information from Edmunds displays the average selling price of a used vehicle purchase in December at $29,533, down virtually $1,600 from the history large of $31,095 arrived at in April 2022. Today’s typical made use of auto rate is about the same as the ordinary new car or truck price as not too long ago as 2010.

While the charges of late model utilised vehicles are down only 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} off their peak in accordance in accordance to Edmunds, the rate of more mature utilised vehicles, all those 5 many years or older, have fallen 15{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} or more from their peaks early in 2022.

Specialists say motives for the drop consist of greater desire charges that make it a lot more highly-priced to finance a car acquire, limiting need. CarMax

(KMX)
, the nation’s largest pure utilized vehicle vendor, has warned that the combination of higher price ranges and superior desire fees is building an affordability trouble for numerous prospective buyers, hurting total demand.

But the primary explanation for the drop in utilized car or truck selling prices is the amplified offer of new automobiles.

It was the deficiency of new auto inventory that drove up price ranges. Elements shortages, in particular for laptop chips, experienced choked off generation of new automobiles in a great deal of 2022, resulting in the least expensive stage of whole-year US new auto sales considering that 2011.

The small source of new vehicles induced an even greater bounce in the normal selling price of employed cars and trucks, as purchasers who would otherwise acquire new cars turned to the used motor vehicle market place.

“At a single issue it seemed that everybody who was heading to purchase new finished up obtaining utilised,” claimed Greg Markus, government vice president of AutoLenders, mother or father company of New Jersey’s biggest applied automobile dealership chain.

That bundled rental motor vehicle organizations, which right before the pandemic ordinarily bought about 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} or a lot more new cars for every calendar year. With confined stock of cars to market, automakers essentially stopped generating decreased-priced fleet gross sales, and even rental motor vehicle providers ended up forced to switch to the used automobile marketplace.

All that has started to adjust in current months. Automakers are reporting much more materials of the chips they have to have, and are producing and offering extra cars, such as a return of fleet revenue. In general, sales ended up up 9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in the fourth quarter when compared to a yr in the past, and virtually 6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} better than in the 3rd quarter, according to Cox Automotive. And with additional purchasers acquiring the new vehicles they want, that means lessen demand from customers for applied cars.

Authorities say section of the decrease in utilised car costs is that the price tag will increase have been not sustainable and had been partly pushed by customers at utilised motor vehicle auctions overpaying for the restricted provide of made use of vehicles.

“There was nowhere for these prices to go but down,” claimed Markus.

There could be extra declines in employed motor vehicle costs in the months forward, as new auto inventories continue to construct. A single thing that could set a flooring below the made use of automobile price ranges: late model utilised cars will probable be in limited provide specified the decreased new motor vehicle output around the last 3 decades.

“The offer concern is still grim,” claimed Markus. For the reason that of that, “I don’t believe we’re having down to 2019 ranges,” he additional.

The run-up in made use of car or truck selling prices was a key driver in the nation’s in general inflation amount, incorporating about a total share position to the over-all enhance in buyer price ranges from April of 2021 as a result of May well of 2022. Now it’s a element supporting to carry down the speed of inflation, shaving far more than a third of a level off the overall charge in December.

This is clearly great news for those people wanting or needing to obtain a utilized motor vehicle, while it can have a destructive effect on motor vehicle buyers by decreasing the price of auto they hope to trade in. Edmunds demonstrates the common trade-in value in December down virtually $3,000, or 11{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, to $22,605, from the document significant hit in June of 2022.

That drop in the worth of trade-ins could also be a headwind on vehicle selling prices by reducing what prospective buyers are able to fork out.

Want Better Returns? Don?t Ignore These 2 Business Services Stocks Set to Beat Earnings

Want Better Returns? Don?t Ignore These 2 Business Services Stocks Set to Beat Earnings

Earnings are arguably the most vital one number on a company’s quarterly economic report. Wall Road plainly dives into all of the other metrics and management’s enter, but the EPS figure helps slice through all the sounds.

The earnings figure itself is essential, of study course, but a defeat or skip on the bottom line can at times be just as, if not additional, critical. Thus, buyers need to think about shelling out shut focus to these earnings surprises, as a big beat can aid a inventory climb and vice versa.

The ability to identify shares that are very likely to leading quarterly earnings expectations can be lucrative, but it is no uncomplicated task. Listed here at Zacks, our Earnings ESP filter assists make factors a lot easier.

The Zacks Earnings ESP, Described

The Zacks Earnings ESP, or Predicted Shock Prediction, aims to find earnings surprises by concentrating on the most modern analyst revisions. The fundamental premise is that if an analyst reevaluates their earnings estimate in advance of an earnings release, it means they probable have new facts that could quite possibly be extra accurate.

With this in brain, the Predicted Shock Prediction compares the Most Accurate Estimate (being the most the latest) against the over-all Zacks Consensus Estimate. The share change provides the ESP determine. The technique also utilizes our main Zacks Rank to deliver a more powerful program for identifying stocks that could conquer their following quarterly earnings estimate and potentially see the stock price tag climb.

In actuality, when we mixed a Zacks Rank #3 (Keep) or better and a good Earnings ESP, shares manufactured a beneficial shock 70{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the time. Perhaps most importantly, employing these parameters has assisted make 28.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} once-a-year returns on average, in accordance to our 10 12 months backtest.

Most stocks, about 60{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, tumble into the #3 (Maintain) classification, and they are predicted to complete in-line with the broader marketplace. Shares with a #2 (Acquire) and #1 (Strong Buy) rating, or the top rated 15{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and top 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of shares, respectively, ought to outperform the market place, with Potent Purchase shares outperforming much more than any other rank.

Really should You Consider S&P World wide?

The past matter we will do right now, now that we have a grasp on the ESP and how effective of a instrument it can be, is to swiftly look at a qualifying inventory. S&P Worldwide (SPGI) retains a #3 (Maintain) at the instant and its Most Precise Estimate comes in at $2.49 a share 24 days absent from its forthcoming earnings launch on February 9, 2023.

SPGI has an Earnings ESP determine of +.66{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, which, as discussed earlier mentioned, is calculated by having the proportion big difference in between the $2.49 Most Accurate Estimate and the Zacks Consensus Estimate of $2.47. S&P Worldwide is one particular of a big database of stocks with positive ESPs. Make guaranteed to make use of our Earnings ESP Filter to uncover the best stocks to purchase or sell right before they have claimed.

SPGI is section of a large group of Business Solutions stocks that boast a constructive ESP, and traders may want to choose a seem at Booz Allen Hamilton (BAH) as very well.

Slated to report earnings on January 27, 2023, Booz Allen Hamilton holds a #2 (Purchase) ranking on the Zacks Rank, and it truly is Most Precise Estimate is $1.08 a share 11 days from its future quarterly update.

Booz Allen Hamilton’s Earnings ESP determine currently stands at +5.06{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} after having the percentage distinction in between its Most Correct Estimate and its Zacks Consensus Estimate of $1.03.

For the reason that each shares hold a constructive Earnings ESP, SPGI and BAH could probably submit earnings beats in their upcoming stories.

Find Stocks to Invest in or Provide Right before They are Noted

Use the Zacks Earnings ESP Filter to transform up shares with the optimum chance of positively, or negatively, shocking to buy or sell ahead of they’re claimed for worthwhile earnings period investing. Check out it out right here >>

Zacks Names “Single Greatest Pick to Double”

From hundreds of stocks, 5 Zacks professionals every single have decided on their preferred to skyrocket +100{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} or a lot more in months to occur. From individuals 5, Director of Analysis Sheraz Mian hand-picks one particular to have the most explosive upside of all.

It is a little-identified chemical firm that’s up 65{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in excess of previous year, nevertheless however grime low-priced. With unrelenting demand, soaring 2022 earnings estimates, and $1.5 billion for repurchasing shares, retail investors could soar in at any time.

This enterprise could rival or surpass other recent Zacks’ Shares Set to Double like Boston Beer Enterprise which shot up +143.{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in little much more than 9 months and NVIDIA which boomed +175.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in one 12 months.

Cost-free: See Our Prime Stock and 4 Runners Up >>

Want the latest suggestions from Zacks Expenditure Exploration? Now, you can download 7 Finest Shares for the Following 30 Times. Click on to get this totally free report

S&P World Inc. (SPGI) : Free of charge Stock Examination Report

Booz Allen Hamilton Keeping Company (BAH) : No cost Stock Examination Report

To read this report on Zacks.com simply click in this article.

Zacks Investment decision Exploration

The views and viewpoints expressed herein are the views and thoughts of the author and do not automatically replicate those people of Nasdaq, Inc.