Here are 5 changes student loan borrowers could see in 2022

Here are 5 changes student loan borrowers could see in 2022

recep-bg | E+ | Getty Visuals

Lifetime with no university student financial loans is coming to an conclusion.

The U.S. Department of Instruction by February will restart payments for the thousands and thousands of People with instruction financial debt. They’ve been authorized to pause their charges for near to two several years due to the fact of the coronavirus pandemic.

But the resumption of the payments may be just 1 of many alterations in keep for debtors.

These are some of the other major probable developments on the horizon, professionals say.

Loan cancellation

Whilst Democrats haven’t included pupil mortgage forgiveness in their substantial investing bill at this time performing its way by Congress, there is certainly still the risk that the relief could come from separate legislation or as a result of govt motion by President Joe Biden.

Biden has stated that he is in aid of canceling $10,000 of the loans for all, but some Democrats continue to tension him to elevate that amount of money to $50,000.

Much more from Personal Finance:
How to get a jump-get started on the forthcoming tax period
A lot more than 1 in 3 U.S. adults carry clinical financial debt, study finds
Prevent these 3 holiday break scams on Black Friday and Cyber Monday

If all federal college student bank loan borrowers received $10,000 of their financial debt forgiven, the fantastic education personal debt in the country would slide to all around $1.3 trillion, from $1.7 trillion, according to larger education and learning expert Mark Kantrowitz. And 33{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of federal scholar bank loan borrowers, or 14.4 million folks, would see their balances reset to zero.

Canceling $50,000 for all debtors, on the other hand, would shrink the country’s remarkable college student mortgage debt balance to $700 billion, from $1.7 trillion. Meanwhile, the $50,000 strategy would forgive all of the personal debt for 80{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of federal scholar personal loan borrowers, or 36 million men and women.

Following years of speculation close to loan forgiveness, debtors might before long get an reply.

“If wide student loan forgiveness will manifest, it really should be before long, as Democrats will want to see it applied in advance of the mid-expression elections,” Kantrowitz said.

Additional bankruptcy selections

New servicers

3 organizations that serviced federal student financial loans — Navient, the Pennsylvania Better Instruction Support Agency (also known as FedLoan) and Granite Point out — all lately announced that they’d be ending their partnership with the government.

As a outcome, around 16 million debtors will have a various enterprise to offer with by the time payments resume, or not prolonged just after, according to Kantrowitz.

Double-check out that your servicer has your existing call data, so that you receive all the notices about the future modify, gurus say.

Impacted borrowers should get many notices, stated Scott Buchanan, executive director of the Scholar Personal loan Servicing Alliance, a trade group for federal scholar mortgage servicers. Appear February, if you mistakenly send out a payment to your outdated servicer, he mentioned, the money must be forwarded to your new a single.

Grace interval

Even though federal pupil financial loan bills will technically be because of all over again in February, borrowers might have some additional time.

The Education and learning Department is thinking about giving debtors a three-thirty day period grace interval “where late payments will not be documented as delinquent to the credit history bureaus and the borrowers will be instantly put in a forbearance,” Kantrowitz claimed.

But even though interest on federal university student financial loans has been stopped through the payment pause, it will commence remaining billed yet again in February.

Enable with lower payments

Next chance for defaulted borrowers

Five mistakes that can lead to a bad car loan

Five mistakes that can lead to a bad car loan

As if we need more bad news about car buying, an analysis by Consumer Reports shows that many Americans are drastically overpaying for their car loans. And we can’t place all the blame on the pandemic or supply chain problems.

In one case, Consumer Reports found that a Maryland resident with “sterling credit” who bought a new 2018 Toyota Camry two years ago will end up paying $59,000 by the end of the loan. The reason: Their interest rate was bumped up to 19{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} when they actually qualified for a rate of 4.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

The Consumer Reports study, which looked at 858,000 car loans, concluded that bad car loans, the rising cost of cars and other factors have pushed the average monthly car payment to about $600 — an increase of almost 25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} over the past 10 years.

With a little education and free online tools, such as a car payment calculator, you can set up a loan that works for your budget and avoid some common car loan pitfalls.

1. Extending the loan’s term

The term is how many months it takes to pay off the loan. The longer the term, the lower the monthly payments. However, the longer you take to pay off a loan, the more interest you will pay.

For example, if a person with a credit score of about 600 buys a $30,000 car and finances it for 60 months at the rate of 6.61{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, they’ll pay $5,311 in interest. But if that loan is extended to 80 months, they’ll pay $7,175 in interest. That’s an extra $1,864 up in smoke.

2. Not shopping for your loan

Before you shop for a car, you really should shop for a loan. Start by checking your credit and resolving any issues you discover. Then, apply for a preapproved car loan from a credit union or online lender. By doing this ahead of time, you can choose the down payment and loan term to fit your budget.

Getting preapproval also simplifies the negotiation process because it gets you focused on the out-the-door price. You can always take the dealer’s financing if the interest rate is lower. But your preapproved loan will serve as a bargaining chip to get its best rate.

3. Being ‘upside-down’ on a car loan

You’re upside-down on a car loan when you owe more than the car is worth. If you experience an unexpected life change — a divorce, death or sickness in the family — and you have to sell the car, you’ll have to pay off the loan, plus the negative equity.

On the other hand, if you have equity in your car, you can use that as a down payment on your next car. Or just sell it, pay off the loan and pocket the difference.

4. Rolling negative equity into the new loan

If someone is upside-down on a car loan, but they just have to buy that new car, the dealer will be happy to roll the negative equity into the next loan. In that way, a person who is $10,000 upside-down on a car loan can buy a $30,000 car and wind up with a $40,000 loan.

There’s no good reason to roll negative equity into a new loan. Doing so can lead to a spiral of debt as you try to keep up with the payments. Instead, keep driving your current car and try to make extra payments until you’re right-side up.

5. Buying extras

Sometimes, that car you agreed to buy has dealer-installed options that aren’t listed on the sticker. If that’s not enough, the finance manager might give you the hard sell on an extended warranty, a wheel and tire warranty or a prepaid maintenance plan.

All of these extras go into your balance on the sales contract and result in a much higher loan to pay off. The best strategy is to flush out those extras early in the negotiation process. I like to ask for an out-the-door price with a breakdown of all the costs and fees.

Here are several ways to keep control of your car loan:

Use a car loan payment calculator to estimate your monthly payment. Try using different terms and down payment amounts to see what works best for your budget.

Be realistic about what monthly payment you can afford, and shop for a loan that meets that criterion.

Getting preapproved for a car loan is perhaps the single best way to keep control of your car-buying transaction.

Carry as little debt as possible by saving for a down payment of at least 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the purchase price.

Reed writes about the auto industry and finance for NerdWallet.com. His Twitter handle is @AutoReed.

Public Service Loan Forgiveness: Nearly 30,000 awarded debt cancellation so far under new rules

Public Service Loan Forgiveness: Nearly 30,000 awarded debt cancellation so far under new rules

“I cried when I bought the letter. I actually come to feel like I can ultimately breathe yet again,” claimed Rickfelder, who experienced a further five several years of payments to make less than the aged procedures of the Community Company Loan Forgiveness application. She began having to pay off her college student credit card debt about 16 a long time in the past.

The letter, which she obtained from the US Division of Schooling in Oct, claimed that she would get credit score for 91 added every month payments she had produced on her pupil financial loans. That meant that she experienced currently produced additional than the 120 payments required for financial debt forgiveness below the PSLF application, which is aimed at borrowers functioning in government and nonprofit sectors.

“I appreciate educating. But it has usually been a financial wrestle. Now I do not have to keep getting a workaround for the debt,” Rickfelder, a single mother, claimed.

Around the yrs, the funds she borrowed for her undergraduate and master’s degrees ballooned due to the fact her payments ended up barely masking the curiosity on the university student loans. Her credit card debt grew to much more than $189,000.

Now, in addition to the cancellation of her remaining scholar mortgage personal debt, she also received a refund previous 7 days for the further payments she experienced designed.

Eligibility for the PSLF method is briefly expanded until finally October 31, 2022, so that it now contains debtors who have older loans that failed to originally qualify as well as those who were in the improper repayment plan but met the other prerequisites.

Extra than 550,000 persons are predicted to see their financial debt wiped absent sooner than expected due to the alterations.

Problems with the university student loan forgiveness application

The Community Services Bank loan Forgiveness method was signed into legislation by President George W. Bush in 2007 and supplies an incentive for staff to continue being in lessen-having to pay, community service work opportunities despite their pupil financial debt.

Lecturers, social staff and first responders can be suitable as nicely as doctors and lawyers — if they were used entire time by a nonprofit or the govt although creating payments.

Following borrowers make 10 a long time of qualifying month to month payments, their remaining federal scholar debt is wiped absent.

But the method has long been criticized for staying challenging to navigate, with debtors acquiring very little assist from their personal loan servicers, the organizations that take care of the billing. Numerous borrowers have claimed they found out they were not suitable for forgiveness only soon after building what they considered were being a decade’s really worth of qualifying payments.
New Public Service Loan Forgiveness rules: What borrowers need to know

Prior to the not long ago introduced adjustments, eligibility also hinged on owning a Direct Mortgage and being enrolled in an money-pushed repayment approach, which sets payments based mostly on earnings and family size. Those with Federal Spouse and children Schooling Loans, which have been built by non-public loan companies but backed by the governing administration, did not qualify. Much more than 80{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of borrowers who have submitted types that did not satisfy the program’s requirements had 1 of these financial loans.

Debtors are allowed to consolidate a Federal Family members Instruction Loan into a Direct Financial loan to turn into suitable for the program, but none of their previous payments would rely toward the necessary 120 — right until now.

Many pupil mortgage debtors are nevertheless waiting

Owing to the short term waiver, it no more time matters what variety of federal college student bank loan a borrower has or what payment program he or she is enrolled in. All payments will be qualified for PSLF if the borrower was doing the job complete time for a qualifying employer.

But several debtors who newly qualify for personal debt forgiveness are nevertheless waiting to see their harmony reduced. It is really heading to consider time for the Section of Schooling to evaluation all their accounts.

“Remember to have an understanding of that intricate alterations of this magnitude are tricky to system and execute,” wrote Federal Student Aid Chief Operating Officer Richard Cordray in a letter despatched to debtors earlier this month.

“We are functioning as swiftly as feasible to update your account and give you distinct and exact info. This might just take quite a few months,” he added.

The letter also acknowledged that some qualifying borrowers have been given bewildering details from their personal loan servicers and some have even been denied since the program overhaul was announced. Cordray pledged that all those borrowers’ accounts would be reviewed in the future handful of months.

What university student financial loan borrowers can do up coming

Lots of debtors would not have to consider any action in buy to have the Office of Education and learning critique and update the amount of their qualifying payments.

But individuals with more mature Federal Family members Instruction Loans will have to consolidate into a Immediate Personal loan if they have not previously completed so. These who by now have Direct Financial loans but have not submitted an work certification sort for past intervals of repayment have to also do that now.

Borrowers have until eventually October 31, 2022, to make these alterations to qualify for forgiveness below the short-term waiver. For individuals not sure if they qualify, the Department of Education up-to-date its PSLF Assist Software earlier this week to mirror the new suggestions. The tool provides much more details about up coming ways wanted to acquire edge of the waiver.

If You Want Student Loan Forgiveness, Do These 5 Steps

If You Want Student Loan Forgiveness, Do These 5 Steps

If you want student loan forgiveness, do these 5 steps.

Here’s what you need to know.

Student Loans

With student loan relief from the Covid-19 pandemic ending imminently, student loan borrowers are scrambling to find ways to get student loan forgiveness. For the past 22 months, thanks to Congress, President Donald Trump and President Joe Biden, there have been no mandatory federal student loan payments, 0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} interest rates on federal student loans, and no collection of student loans in default. However, with the expiration of student loan relief, many student loan borrowers need financial help. If you want student loan forgiveness, do these 5 steps.


1. Know there won’t be any wide-scale student loan forgiveness

If you’re hoping for mass student loan forgiveness soon, stop hoping. Why? There’s a low likelihood of wide-scale student loan cancellation in the near-term. Progressives in Congress have been campaigning on up to $50,000 of student loan forgiveness for student loan borrowers. However, Biden has shown no indication that he is seeking to cancel student loans for all or most student loan borrowers. (Here’s who qualifies for student loan forgiveness right now).While the U.S. Department of Education is considering mass student loan forgiveness among its cadre of ameliorative measures, Biden and the Education Department have focused on targeted student loan forgiveness. Could mass student loan forgiveness happen? Sure, but you should focus on other strategies for student loan repayment rather than expecting your student loans will get cancelled soon.


2. Check current options for student loan forgiveness

Biden has cancelled $11.5 billion of student loans since becoming president in January. That’s only the start, with billions of dollars more in student loan forgiveness expected. There are multiple ways to get student loan forgiveness. (How to apply for student loan forgiveness during the Biden administration). First, if you have a total and permanent disability, Biden cancelled $5.8 billion of student loans for these borrowers. Second, if you were misled by your college or university, your student loans could be partially or totally cancelled. Biden has cancelled $1.5 billion of these student loan borrowers. Third, if you’re pursuing public service loan forgiveness, Biden has cancelled $4.5 billion of student loans. (These borrowers don’t qualify for student loan forgiveness)


3. Get public service loan forgiveness

You can still get student loan forgiveness through the Public Service Loan Forgiveness program. This is an active program that is open to all federal student loan borrowers. How much student loan forgiveness can you get? Answer: all your federal student loans can get cancelled. The Education Department announced this month that $2 billion of student loans will be cancelled within weeks. To qualify, you’ll need to meet several requirements, including working full-time for a qualified public service or non-profit employer, make 120 monthly payments, and enroll in an income-driven repayment plan, among other requirements. The Biden administration made major changes to student loan forgiveness, which relaxed the rules significantly and makes it easier to get student loan forgiveness. That said, these changes are temporary, so if you’re pursuing public service loan forgiveness, make sure to complete a limited student loan forgiveness waiver before October 31, 2022. This way, you can count previously ineligible student loans and student loan payments to help you get student loan forgiveness faster. (Here’s how to apply for limited student loan forgiveness)


4. Get student loan forgiveness even if you don’t work in public service

So, if you don’t have a total and permanent disability, don’t qualify for borrower defense to repayment, or don’t work in public service, you may think that you won’t qualify for student loan forgiveness. Not necessarily. There are several other ways to get student loan forgiveness.


5. Refinance student loans

If you want student loan forgiveness, student loan refinancing may be a smart option for you. With student loan refinancing, you can get a lower interest rate, lower monthly payment, or both. Student loan refinancing rates are incredibly low, and start at 1.74{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

This student loan refinancing calculator shows you how much you can save with student loan refinancing.

For example, let’s assume you have $70,000 of student loans with a 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} interest rate and 10-year repayment term. If you refinance at a 2.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} interest rate and 10-year repayment term, you could save $153 each month and $18,344 total.

You can refinance private or federal student loans, or both. You can choose a fixed or variable rate, and choose a student loan repayment term from 5-20 years. While you won’t get immediate “student loan forgiveness,” you can save thousands of dollars or tens of thousands of dollars over the life of your loan through savings in interest. To qualify, you’ll need a credit score of at least 650, stable income, be employed or have a signed job offer, and a low debt-to-income ratio. Student loan refinancing of federal debt is not for everyone, however, if you think you’ll need federal loan benefits such as federal student loan forgiveness, forbearance or deferment, for example. Why? Through refinancing, your federal debt becomes private debt and these federal benefits won’t be available. So, you could refinance private debt only. Alternatively, you may not need these federal programs or prefer a lower rate to save more money, so in that case, you could choose to refinance both private and federal loans.

As you navigate strategies for student loan repayment, make sure you understand all your options. Here are a few smart places to start to save money on your student loans:


Student Loans: Related Reading

How to apply for limited student loan forgiveness

Education Department will cancel $2 billion of student loans

Here’s who qualifies for student loan forgiveness right now

3 ways to get a lower student loan payment

Ohio State has a plan to erase student loan debt : NPR

Ohio State has a plan to erase student loan debt : NPR

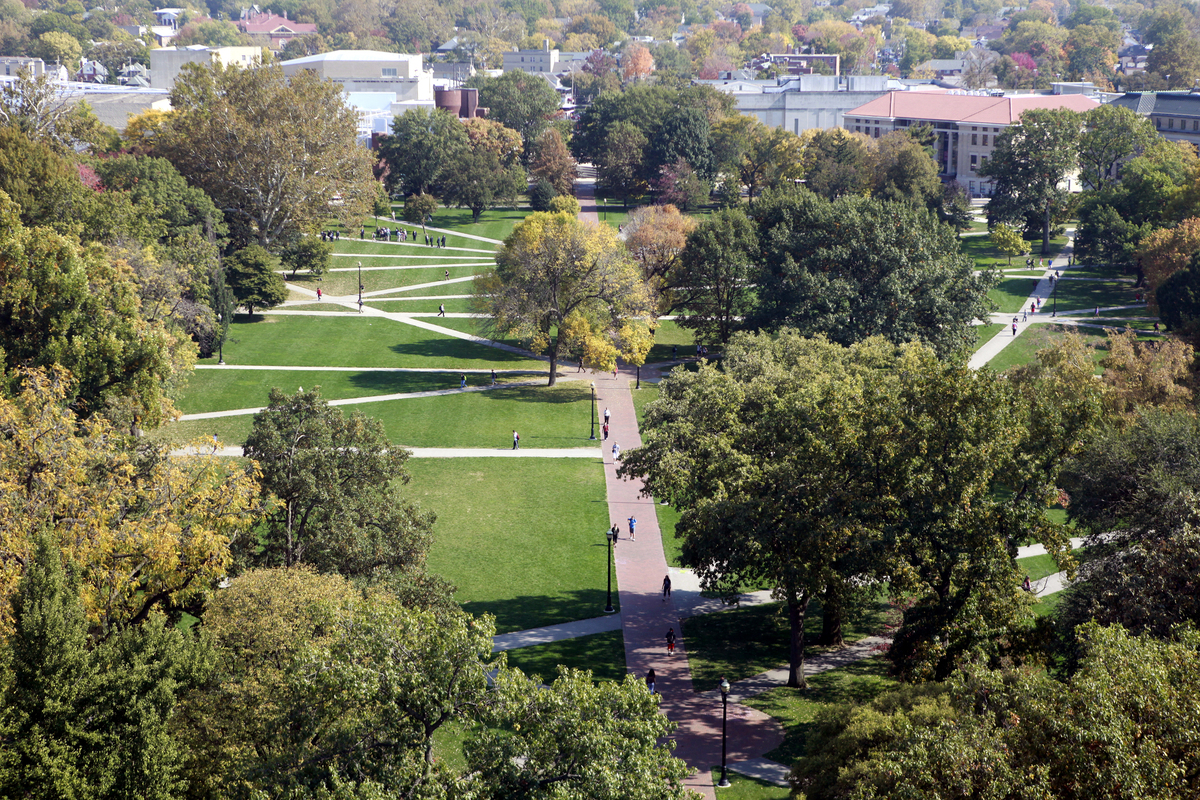
An aerial look at of The Oval on the campus of the Ohio Condition College in Columbus, Ohio.

Terry Gilliam/AP


conceal caption

toggle caption

Terry Gilliam/AP


An aerial see of The Oval on the campus of the Ohio State College in Columbus, Ohio.

Terry Gilliam/AP

Ohio State College has released an formidable, 10-12 months system to raise $800 million to reduce all loans from monetary assist deals supplied to undergraduates.

“It truly is not free of charge higher education, it really is not no cost tuition,” claims Kristina Johnson, the president of Ohio Condition, “but can we acquire one of the most significant universities in the state and acquire pathways for our learners so that they can graduate personal debt-free of charge?”

The college, which graduates additional than 8,000 undergrads a calendar year, suggests about fifty percent of people learners graduate with financial debt. On common, graduates depart the university owing about $27,000, an volume that is in line with nationwide averages for college students finishing a bachelor’s degree.

“We have surveyed our students and what they explain to us is that with $27,000 in regular personal debt, they’re making selections that they if not would not have created. They are not heading to graduate faculty, serving their community, purchasing a residence,” says Johnson. “We want folks to abide by their passions, what they’re genuinely intrigued in, since we know when they do that, they’re heading to be most thriving, pleased, pleased and fulfilled.”

Not the to start with, but probably the largest

The credit card debt-elimination system would charge Ohio Point out about $110 million a year, offered to learners by way of scholarships, operate prospects and compensated internships. Philanthropy will be the greatest ingredient of the initiative, but Johnson explained the university is also working with condition lawmakers to enhance pupil support.

The go by Ohio Point out follows efforts in the latest a long time by other universities, but most have been at lesser, far more selective educational institutions, like Amherst University in Massachusetts, and among the the Ivy League. Ohio State is a single of the largest universities in the place with far more than 40,000 undergraduates.

Though there are much more than 6 dozen schools that offer minimal-revenue family members a path to a financial debt-cost-free undergrad practical experience, considerably less have built it a policy for all students, no matter of cash flow. In 2018, Johns Hopkins University in Maryland gained a $1.8 billion present from alum Michael Bloomberg, the previous New York Metropolis mayor, to switch financial loans with scholarship grants at the university.

The initiative at Ohio State seems to be the premier attempt by a condition college to do this. “The dilemma is: Can it be carried out at scale?” says Johnson. “That is what I’m tremendous fired up about. We’re going to do it at scale.”

The flagship campus, based mostly in Columbus, also funnels in college students from Ohio’s regional campuses across the state, broadening the guarantee to have an effect on a much larger sized swath of learners.

The program would start out with a pilot software for 125 incoming freshmen upcoming tumble, growing to consist of all undergraduates over the subsequent ten years.

Democrats’ $2 trillion spending bill excludes student loan forgiveness

Democrats’  trillion spending bill excludes student loan forgiveness

Olga Kaya | iStock | Getty Visuals

One element about the Democrats approximately $2 trillion social paying out invoice that hasn’t garnered considerably focus is the point that scholar personal loan forgiveness has been excluded.

Even now, the absence of any schooling credit card debt aid from the sweeping legislation aimed at lifting up American households has caused frustration and disappointment for advocates and debtors, who position to President Joe Biden’s recurring guarantees on the marketing campaign path to cancel at minimum $10,000 of the loans for all. (Other Democrats had pressured him to increase that quantity to $50,000.)

“I am progressively pessimistic about the Biden Administration,” reported Luke Herrine, former authorized director of the advocacy team the Personal debt Collective.

Superb scholar financial loan personal debt in the U.S. has topped $1.8 trillion, posing a greater stress to family members than credit score card or automobile credit card debt. Struggles to repay the personal debt are frequent: Much more than a quarter of debtors are in delinquency or default.

A lot more from Particular Finance:
Where to make and preserve cash as inflation rises
46{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Americans assume to retire in financial debt
How climbing inflation may direct to bigger tax costs

Due to the fact March 2020, the U.S. Office of Training has presented most people today with federal college student loans the alternative to pause their payments with no interest accruing, and just about all have done so. The charges are scheduled to resume in February.

“They ought to understand that individuals have become employed to not paying pupil credit card debt, and several have begun to request why they really should ever have to shell out yet again,” Herrine mentioned.

The absence of motion could value the get together, he said.

“Re-commencing scholar financial loan payments just in advance of a mid-term election is politically idiotic,” Herrine explained.

The White Dwelling did not immediately respond to a ask for from CNBC for remark.

The reconciliation process by way of which Democrats hope to go their huge investing bill was considered to be the perfect time to enact student loan cancellation. That’s because the method would not involve any Republican assistance, whereas standalone laws, owing to procedural procedures in the Senate, would leave Democrats needing to get at least 10 Republicans to indication on. That’s an not likely feat, political authorities say.

But it was the actuality that Democrats could not even have gotten all their customers on board for pupil financial loan forgiveness that very likely held them from putting it in the monthly bill, professionals say. Provided the party’s razor-slender vast majority, the opposition of one Democrat can derail the complete legislation.

“Many Democrats are anxious about the price tag tag of loan forgiveness,” said larger schooling expert Mark Kantrowitz. Canceling $50,000 in college student financial loans for every single borrower would charge far more than $1 trillion, in accordance to his calculations.

Proponents of wide student bank loan forgiveness are continue to keeping out hope, arguing that the president has the electric power to terminate the credit card debt through govt action.

Biden has asked the U.S. Office of Justice and the U.S. Division of Education and learning to evaluation his lawful authority to crystal clear the financial loans devoid of Congress. The success have not been manufactured community yet, but the president has so significantly expressed hesitation to make these a move.

Nonetheless, some consider that route remains the extra promising a person when compared with receiving all Democrats to again a jubilee, Herrine mentioned.

“Congressional progressives imagine that, in the brief phrase, they have a better opportunity convincing Biden than convincing the moderates,” he reported.