Dems again urge Biden to cancel student loan debt as payment restart looms

Dems again urge Biden to cancel student loan debt as payment restart looms

A group of Democrats is ramping up the strain on President Biden to use his government authority to cancel billions of dollars in pupil bank loan debt and extend a moratorium on payments that is poised to expire in February. 

In a Wednesday letter tackled to the White Residence, Senate Vast majority Leader Chuck Schumer, D-N.Y. Sen. Elizabeth Warren, D-Mass. and Rep. Ayanna Pressley, D-Mass., warned that hundreds of thousands of family members could be hurt financially and that the economy’s restoration from the pandemic imperiled if Biden does not lengthen the federal government’s pause on pupil loan payments, which is slated to conclude on Feb. 1, 2022. 

The lawmakers cited an analysis executed by the Roosevelt Institute, a progressive assume tank, demonstrating that resuming college student-loan payments in much less than two months will “strip” 18 million borrowers of $7.12 billion a thirty day period and $85.48 billion on a yearly basis around the up coming year. 

CANCELING College student Mortgage Credit card debt COULD Gain Rich Us citizens THE MOST

The research examined 60{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the 43 million complete borrowers in the U.S. afflicted by the payment pause, excluding the 7.7 million folks who are powering on payments. Based on that data, there are around 18 million debtors who – prior to the freeze on payments began – paid an normal of $393 for every month toward their loans. 

“To reduce the pupil credit card debt crisis from dragging down on our financial restoration, undermining the effectiveness of the American Rescue Plan, and producing needless ache and pressure for American family members, we strongly urge you to increase the pause on college student loan payments and fascination and act to terminate university student personal debt,” they wrote in the letter.

Senate The greater part Chief Chuck Schumer speaks to reporters following a Democratic plan assembly at the Capitol on Sept. 28, 2021. (AP Image/J. Scott Applewhite / AP Newsroom)

Lawmakers have cited the extra uncertainty triggered by the new omicron variant of COVID-19, which has been observed in at minimum 57 nations, which include the U.S. 

There is nevertheless a lack of clarity over how unsafe the pressure is, together with no matter if it is much more transmissible or able of producing extra serious ailment. Early evidence indicates an increased risk of reinfection. 

“If we will not extend the pause, curiosity fees just pile up. College students owe a fortune,” Schumer claimed. “And with omicron right here, we are not having out of this as swiftly as we would like.”

The Training Division has supplied about $72 billion in relief on university student personal loan fascination by itself, the lawmakers previously claimed. About 41 million Individuals are benefiting from the federal government’s pause of university student loan payments, which started in March 2020 and was two times extended.

Schumer, Warren and Pressley also identified as on Biden to cancel $50,000 in fantastic federal credit card debt for each borrower through executive order. The Democrats have taken care of that Biden could use existing government authority less than the Increased Education and learning Act to purchase the Department of Instruction to “modify, compromise, waive or launch” student loans.

Sen. Elizabeth Warren puts on her mask just after talking at a information convention on Capitol Hill on March 1, 2021. (AP Image/Susan Walsh)

They cited the Roosevelt Institute analysis, which approximated that wiping out $50,000 in federal personal debt for every borrower would enhance the nation’s GDP by $173 billion in the 1st year the plan was executed.

“The authors of this assessment are suitable,” the lawmakers wrote. “We strongly urge you to act without the need of delay. In the meantime, we strongly urge you to extend the pause on pupil bank loan payments, interest and collections right until the overall economy reaches pre-pandemic employment stages.”

This kind of sweeping govt action by Biden would virtually definitely experience a legal challenge, and it is unclear no matter if it could survive. Critics have argued that making use of this kind of power exceeds the president’s authority granted by Congress.

GET FOX Small business ON THE GO BY CLICKING Listed here

Biden campaigned on canceling billions of bucks in university student financial loan credit card debt but has so significantly erased just a fraction of the pledged amount for about 72,000 borrowers, drawing ire from some progressive lawmakers who want him to shift even further left on the concern.  

Exceptional college student loan credit card debt has doubled about the previous decade, nearing a staggering $1.7 trillion. About one in six American grownups owes funds on federal scholar mortgage debt, which is the major amount of money of non-mortgage financial debt in the U.S. It has been cited as a key hindrance in people’s “economic everyday living” by Federal Reserve Chairman Jerome Powell.

‘Killing the middle class’: millions in US brace for student loan payments after Covid pause | Biden administration

‘Killing the middle class’: millions in US brace for student loan payments after Covid pause | Biden administration

Jennifer Rae Wilson, a social employee and single mother of 3 little ones in Richland, Washington, has struggled with pupil financial loan personal debt considering the fact that she went back to school and graduated in 2000 – extra than two many years back.

Struggling to increase three boys with very very little kid assistance, Wilson decided to attend higher education 10 yrs right after graduating high faculty to make improvements to her job potential clients. She was at some point able to go out of very low-profits aid housing and off governing administration support packages.

“But then the faculty financial loans hit,” explained Wilson. “I could not afford to pay for the payments on prime of lease and all of the other matters, there was no way that I could make those payments.”

She is not alone, as university student financial debt in The us has come to be a disaster for thousands and thousands of citizens that generally feels like it will past for people’s complete life, or at least blight them for quite a few many years to arrive just after graduation. Close to 44.7 million Us residents have superb scholar bank loan financial debt totaling more than $1.86tn, with 42.3 million Us citizens holding federal university student bank loan credit card debt.

The US Department of Education and learning paused reimbursement, collections and fascination on federal university student loans in reaction to the Covid-19 pandemic beneath Trump, with the remaining extension on the pause set to expire on 31 January 2022.

But now thousands and thousands of Americans are bracing for resuming payments on federal pupil loans immediately after just about two yrs of aid – and the crisis is established to roll on once more.

Amongst rent, costs and daycare expenditures, Wilson went into default following not becoming equipped to hold up with college student financial loan payments. Then her paychecks commenced staying garnished in 2010 to pay off the college student financial loans of all-around $1,000 per thirty day period, which was just having to pay off the fascination on her principal.

The pause on university student personal loan repayments throughout the pandemic authorized Wilson to capture up on other payments and purchase a residence, but she concerns about the payments restarting.

“It sort of considerations me a minimal bit with it coming again with what they’re heading to be ready to present us in terms of payment designs,” additional Wilson. “I’ve been earning payments for 20 many years and my harmony has only long gone up. That does not make any perception. If I created a $1,000 per month payment on my motor vehicle, or on my home, I would be compensated off and I would not have a residence mortgage or would not have a car or truck financial loan. But with this, it doesn’t appear to be to make a big difference.”

A latest study of a lot more than 33,000 pupil bank loan borrowers conducted by the Scholar Credit card debt Disaster Centre identified 89{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of borrowers are not fiscally safe more than enough to resume payments on 1 February. Prior to the pandemic, over half of all college student personal loan debtors were being both in default, forbearance, deferment, or in any other case not presently making payments on their university student debt.

PJ Rivera of Texas is 1 of the borrowers not prepared to resume scholar personal loan payments. His preliminary university student personal debt was all around $80,000, but has increased with desire to $110,000, despite building payments of $1,000 a thirty day period.

“Student financial loans have crippled my ability to have personal savings but the lack of ability to help my spouse and children who are struggling with clinic expenditures and other health care payments,” claimed Rivera. “The method doesn’t function. It is not the students’ fault simply because you have to have funds to pay out for your vocation. Probably tuition shouldn’t be so significant to begin with. Absolutely everyone need to be capable to review and understand about whichever they are passionate about with no going broke or residing to fork out and almost nothing else.”

The regular scholar bank loan credit card debt for new college or university graduates is around $30,000. Joe Biden campaigned on cancelling $10,000 in scholar financial loan personal debt for each person and cancelling pupil personal debt for Us citizens who attended Traditionally Black Faculties and Universities and general public colleges, but the Biden Administration has however to terminate credit card debt for these People in america

Beverly Dunker Brown of New York City concluded her undergraduate and graduate degrees in the 1980s and 90’s, but with superior curiosity fees and having on guardian in addition loans for her son, her student bank loan financial debt has amplified from all around $43,000 in financial loans to over $150,000.

“I will be in my late 80s paying scholar loans off of social security cash flow,” reported Dunker Brown. “I have Federal Household Training Mortgage Plan financial loans which ended up not paused. I just can’t afford to pay for to shell out them and go on to ask for forbearances on them.”

Regardless of earning a six-determine income in organization administration, she is unable to properly help save for retirement, help you save for home, and cares for her disabled spouse who is a most cancers survivor and consistently needs dialysis. Her personal college student financial loans are $862 regular and the father or mother additionally financial loans for her son will insert yet another $362 a thirty day period when the federal college student financial loan pause finishes.

“The curiosity and penalties are just insane. My college student mortgage harmony improves just about every thirty day period. Black and Brown persons simply cannot get in advance,” included Dunker Brown. “I have no generational wealth, retirement savings or personal savings for an unexpected emergency, however I have an MBA that I attained in 1996. Having a fancy degree was not the solution it was supposed to be.”

Black college graduates owe an ordinary of $7,400 extra in university student financial loans than white college or university graduates, and that hole a lot more than triples to nearly $25,000 after 4 a long time from graduation.

Sabrina Elliott of Charlotte, North Carolina, couldn’t afford to pay for to make payments toward her pupil loans for the to start with eight yrs following graduating legislation college. By the time she could afford to pay for to start out creating payments, with the personal debt ballooned from more than $72,000 to additional than $166,000.

For the past 7 yrs, Elliott has produced regular minimal payments of almost $1,400 a month, but however owes a lot more than the original financial loans despite spending around $90,000 toward the credit card debt in that time.

“Student loans ought to not impair a human being from currently being a homeowner, starting up a household or a badge of disgrace,” mentioned Elliott. “I have made payment for in excess of seven years and the equilibrium is the identical. As you can see, I have repaid the unique personal loan. The bare minimum payment is a property finance loan payment but not high enough to cut down the financial debt.”

Kaida Flowers, a household and baby therapist in Philadelphia, Pennsylvania, has struggled to test to fork out her student financial loans from her undergraduate and master’s degree, and only can make all-around $50,000 a calendar year working a task she pursued to try to assistance men and women and emphasized university student financial debt is producing her and others who pursued comparable career paths to struggle to get by.

She has struggled to try to pay back her pupil loans from her undergraduate and master’s diploma, and only would make close to $50,000 a yr doing work a occupation she pursued to test to assist folks and emphasised college student debt is triggering her and other individuals who pursued similar vocation paths to struggle to get by.

When the payments resume, she will be compelled to fork out $300 a month once more toward her pupil financial debt, most of which goes toward curiosity.

“They’re killing the middle class,” added Flowers. “Part of the American dream is you go to college, you test to do a little something to have a improved life, but it’s just not what it is.”

President Biden hasn’t yet kept his student loan forgiveness promise : NPR

President Biden hasn’t yet kept his student loan forgiveness promise : NPR

President Biden walks to Marine One outside the White House on Dec. 2.

Anna Moneymaker/Getty Images


hide caption

toggle caption

Anna Moneymaker/Getty Images


President Biden walks to Marine One outside the White House on Dec. 2.

Anna Moneymaker/Getty Images

When President-elect Joe Biden was asked whether student loan cancellation figured into his economic recovery plan, he declared, “It should be done immediately.”

“[Student debt is] holding people up,” Biden said on Nov. 16, 2020. “They’re in real trouble. They’re having to make choices between paying their student loan and paying the rent.”

On the campaign trail, Biden had pledged to cancel at least $10,000 of student debt per person.

One year later, while Biden has provided hundreds of thousands of borrowers with debt relief, that $10,000 promise remains unfulfilled. Here’s a look at why — and what he has done.

Biden has focused on preexisting forgiveness programs

The Biden administration’s approach to student loan relief began with improving, extending or expanding a handful of programs that were already on the books.

“We’re working really hard to get students the relief that they’re entitled to” through these preexisting programs, Undersecretary of Education James Kvaal told NPR on Friday.

While it’s not loan forgiveness, Biden extended the pandemic pause on federal student loan payments; that pause is now slated to lift in February. His other actions essentially keep promises the U.S. government had already made to borrowers — rather than make new ones. For example:

  • Total and permanent disability discharge: In August, Education Secretary Miguel Cardona announced that the department would erase the federal student debts of thousands of borrowers with permanent disabilities. A 2019 NPR investigation found that, even though eligible borrowers have been legally entitled to a full discharge of their loans, the process was so complicated that fewer than half were able to shed their debts. The latest data from the Education Department suggests that these changes will help at least 370,000 borrowers drop more than $6.5 billion in student debts.
  • Borrower defense and closed-school discharge: The Biden administration has dramatically expanded efforts to help students who have been defrauded by for-profit colleges and/or whose schools have been forced to close. Defrauded students who previously filed “borrower defense” claims but were given only partial relief under Trump administration rules will now see the rest of their federal student loans discharged.
  • Public Service Loan Forgiveness (PSLF): The program meant to forgive borrowers’ debts after 10 years of public service and steady loan payments has been notoriously stingy, with complex rules and serial mismanagement pushing out many eligible borrowers. In October, though, the department used its expanded pandemic authority to retroactively loosen those rules and give borrowers credit for disqualified loan payments. According to the department, the overhaul has already forgiven $2 billion in debts.

Through these efforts, the Education Department says it has discharged or is in the process of discharging roughly $12.7 billion in student debt, affecting more than 638,000 borrowers.

While these moves were cheered by borrowers and advocates, they were not without controversy. The top Republican on the House Education Committee, Rep. Virginia Foxx of North Carolina, decried the department’s PSLF waiver, calling it “an abuse of executive authority” and “too significant of an issue” to act without Congress.

Broader loan forgiveness would be even more controversial.

In February, Sen. John Thune, R-S.D., responded to some Democrats’ demand that Biden forgive as much as $50,000 in student debt per borrower by calling it “incredibly, fundamentally unfair” to students who have already repaid their debts.

Foxx agrees, telling NPR that borrowers have a responsibility to repay their student debts: “It’s no different than having taken out a loan for a car that you then find you can’t pay back or taking out a loan for a home that you can no longer pay for — or you choose not to pay for.”

Many critics of broad loan forgiveness agree that the cost of college is out of control but insist that canceling student debts would simply address a symptom of the problem, not its cause.

“In fact, Democrats’ ‘solution’ is likely to make things worse,” Thune said on the Senate floor.

“What incentive will colleges have to restrain tuition growth if they think they can rely on the federal government to subsidize their students’ tuition fees through loan forgiveness?”

Advocates and borrowers aren’t satisfied with Biden’s actions so far

While many Republicans have resisted calls for debt cancellation, many Democrats and advocates for student loan relief are growing restless. To them, Biden’s $12.7 billion in debt relief so far is a rounding error, considering that nearly 46 million Americans have $1.6 trillion in federal student loans. And he campaigned on doing more — again, $10,000 per borrower.

“That was a pretty clear promise that he made during the campaign,” says Persis Yu, policy director at the Student Borrower Protection Center. “And certainly, that is a promise that I think many borrowers are right now waiting for him to fulfill.”

Yu also says keeping that promise would make a huge difference, especially for borrowers already in default. “Roughly 16 million borrowers would have their entire debts extinguished, and that amounts to roughly two-thirds of the borrowers who are in default.”

“Crumbs’ worth of action.” That’s how Jalil Mustaffa Bishop describes the Biden administration’s efforts thus far. The assistant professor at Villanova University studies inequities in higher education.

In June, borrower advocates erected signs in front of the White House calling on President Biden to cancel student debt.

Paul Morigi/Getty Images


hide caption

toggle caption

Paul Morigi/Getty Images

Mustaffa Bishop says the student loan system badly needs an overhaul, especially “for groups that historically have been marginalized and had to experience generations of different types of debt traps,” from sharecropping to subprime mortgages to payday lending. Student loans are no different.

Mustaffa Bishop co-authored a recent survey of nearly 1,300 Black borrowers. The report, “Jim Crow Debt,” produced in partnership with the Education Trust, unpacks how pervasive racial inequities, including widespread wealth disparities and persistent workplace discrimination, have left many people of color drowning in student debt.

A 2019 report from the Institute on Assets and Social Policy at Brandeis University found that “Twenty years after starting college, the median debt of White borrowing students has been reduced by 94 percent — with almost half holding no student debt — whereas Black borrowers at the median still owe 95 percent of their cumulative borrowing total.”

Two-thirds of respondents to Mustaffa Bishop’s survey said, in hindsight, they regretted having taken out student loans.

“The student debt crisis is a racial and economic justice issue and we must finally begin to address it as such,” said Rep. Ayanna Pressley, D-Mass., in a statement roughly one year ago. “Broad-based student debt cancellation is precisely the kind of bold, high-impact policy that the broad and diverse coalition that elected Joe Biden and Kamala Harris expect them to deliver.”

There are two ways to cancel student loans

To understand why Biden hasn’t pushed for broad student loan forgiveness, it helps to understand how he could, using one of two doors: 1) Congress or 2) executive action.

Door No. 1 is less controversial, to be sure, but keying it open requires bipartisan support or, at least, unwavering support from Democrats. Loan cancellation appears to have neither.

Consider this: Among the proposals that have been dropped from Biden’s Build Back Better agenda is his pitch for free community college. It’s hard to imagine Democrats would abandon that, at a cost of roughly $45 billion, but still support spending at least $370 billion on student loan forgiveness.

So this door is likely locked — and maybe boarded up from the inside.

That leaves Door No. 2.

Much has been written about the president’s authority — through his education secretary — to simply cancel the debts of millions of borrowers. Here’s an NPR primer from nearly two years ago.

But Biden doesn’t seem eager to try this door. For one thing, he says, it’s not certain that canceling student loans with the stroke of his pen would hold up in court, admitting in a February 2021 town hall that “I don’t think I have the authority” to cancel $50,000 per borrower.

And Biden is not alone in his skepticism.

“The president can’t do it,” said House Speaker Nancy Pelosi, D-Calif., speaking to the media in July. “That’s not even a discussion.”

Whether Pelosi’s conclusion was driven by facts or political expediency (read: giving Biden cover for not keeping a campaign promise), Biden has resisted acting unilaterally.

There’s also the matter of cost. Again, forgiving $10,000 per borrower would come with about a $370 billion price tag, according to the Brookings Institution. Forgiving $50,000 per borrower could cost about $1 trillion.

“Why should taxpayers — 70{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of whom didn’t go to college — pay back loans for people who have an obligation they haven’t fulfilled?” Foxx asks. (In 2020, the U.S. Census Bureau reported that “From 2010 to 2019, the percentage of people age 25 and older with a bachelor’s degree or higher jumped from 29.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 36.0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.”)

Foxx thinks this popularity question is a big reason behind Biden’s hesitancy to act.

“I do think the president maybe understands that broad loan forgiveness is not popular in this country, which is why, I think, he has not gone the route of doing what some in his party want to do.”

But polling suggests broad loan forgiveness would be popular, if done with some nuance. For example, a Grinnell College poll conducted in March found that 27{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of respondents supported forgiving all student debt and an additional 39{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} supported forgiveness “for those in need.” In other polling — from Vox/Data for Progress and the Harris Poll — a majority of respondents supported broad, if limited, forgiveness.

Instead of acting unilaterally, though, this year Biden asked the Education and Justice departments to explore his legal options. The results are still TBD, more than six months later.

Since then, the White House has gone largely quiet on loan cancellation. Some advocates — and many Democrats — worry that, for whatever reason, the administration is intentionally dragging its feet. Not so, said Kvaal, the education undersecretary, in his interview with NPR.

“Legal authority is not an on-off switch. You need to think about the standards that would be applied, the rationale that we can muster,” Kvaal explained. “We are looking very carefully with the White House and the Department of Justice at whether we can cancel loans across the board for everyone, and that’s something where deliberations are still continuing.”

Time may be running out

There’s an argument to be made that Biden is running out of time to broadly cancel student debts. Democrats’ majorities in Congress are likely to shrink next year, if not melt into minorities.

What’s more, the Education Department has said it will require that federal student loan payments, paused during the pandemic, resume as early as Jan. 31.

Imagine millions of borrowers navigating a repayment system they haven’t used in more than a year and a half. Many will need to speak with their loan servicing company to change repayment options. And two of those companies, which serve roughly 15 million borrowers, are right now transitioning out of the federal student loan business all together.

NPR has spoken with more than a dozen student loan experts, including a handful inside the department, who all say they expect this return to repayment to be … difficult.

If broad-based student loan forgiveness is going to happen, it makes all the sense in the world to do it before Jan. 31. Biden’s campaign pledge would mean millions of borrowers would have their debts erased, allowing them to avoid this difficult, potentially disastrous payment restart.

That doesn’t mean Biden has to keep his $10,000 loan forgiveness pledge by then. It just means, if he doesn’t, it’s hard to imagine broad forgiveness happening anytime soon, if at all.


93{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of payday loan borrowers regret taking out their loans, survey finds

93{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of payday loan borrowers regret taking out their loans, survey finds

Payday financial loans can be a debt entice for borrowers who are not able to find the money for to make payments. This is how you can repay your payday mortgage equilibrium prior to it can be sent to credit card debt collectors.  (iStock)

Payday loan providers prey on borrowers with lousy credit who desperately have to have cash, trapping them in a cycle of higher-fascination credit card debt that is challenging to repay. 

The wide the greater part (93{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}) of debtors regret using out their payday financial loan, in accordance to a new survey from DebtHammer. Just 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of respondents explained their monetary situations improved after borrowing a payday bank loan, even though 84{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} claimed they were worse off.

Payday financial loans give individuals an avenue to borrow modest, short-expression dollars financial loans with out a credit score look at. But the common repayment time period is just two months, which potential customers 4 in 5 borrowers to borrow a new payday personal loan to repay their present personal debt, the Shopper Monetary Protection Bureau (CFPB) documented.

It’s attainable to get out of payday bank loan debt without the need of renewing your personal loan and incurring extra expenses. Retain looking at to master how to crack the cycle of payday bank loan borrowing, these types of as consolidating personal debt with a individual loan. You can assess fees on credit card debt consolidation loans for free of charge on Credible with no impacting your credit score score. 

Best Quick-Expression Financial loans: Evaluate YOUR Alternatives

3 ways to get out of a payday loan

The average value of a payday personal loan is equivalent to an once-a-year proportion level (APR) of nearly 400{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} — in other text, borrowers who preserve rolling above their payday loans could pay back 4x the amount of money they originally borrowed around the study course of a calendar year.

Payday creditors may well have you think that rolling above your mortgage is the only way to fork out off your personal debt, but that’s not the scenario. Right here are a few choice methods to crack the payday loan cycle:

  1. Personal debt consolidation financial loans
  2. Prolonged payment programs
  3. Credit counseling

Read about every reimbursement prepare in the sections beneath.

3 Things YOU Should Hardly ever DO WITH YOUR Unexpected emergency FUND

1. Financial debt consolidation loans

Individual financial loans are lump-sum loans that are usually made use of to consolidate additional substantial-fascination financial debt, such as payday financial loan personal debt. They appear with preset interest charges and compensation terms, which suggests that your every month payments will be the exact same while you repay your debt.

These credit card debt consolidation financial loans are commonly unsecured, which indicates that you you should not have to set up an asset as collateral. Because they are unsecured, lenders ascertain your fascination price and eligibility dependent on your credit score score and personal debt-to-profits ratio. 

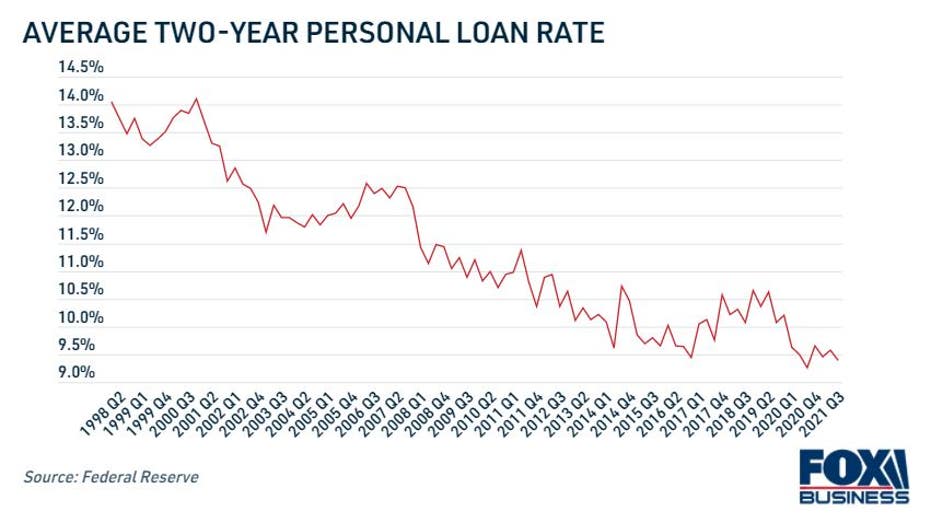
Properly-certified borrowers may well qualify for a minimal rate on a particular personal loan for debt consolidation. Own bank loan premiums are in close proximity to all-time lows, according to the Federal Reserve, averaging 9.39{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in Q3 2021.

Some credit history unions also present smaller payday substitute loans (Buddies), which let users to borrow up to $2,000 with an curiosity fee cap of 28{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. Nonetheless, these loans can be tricky to uncover given that just a tiny part of credit score unions offer you Pals. 

You can see if you qualify for a personal debt consolidation financial loan on Credible with a delicate credit score inquiry, which will not affect your credit score. Use a personalized financial loan calculator to estimate your month to month payments to see if this selection can aid you get out of payday mortgage debt.

Credit score CARD Desire Rates SPIKE TO In the vicinity of ALL-TIME Higher, FED Facts Exhibits

2. Extended payment designs

An prolonged payment system (EPP) lets payday financial loan borrowers repay their credit card debt about a for a longer time time than the usual two-7 days repayment expression. Quite a few states need payday creditors to supply EPPs, so you can have to analysis your state legal guidelines to see if you’re eligible.

Some payday lenders may perhaps offer you EPPs irrespective of regardless of whether they are required to do so by regulation. Creditors belonging to the Neighborhood Monetary Providers Affiliation of The usa (CFSA) are essential to present EPPs to borrowers, but other money establishments may not provide this alternative.

HOW Long DO Negative Merchandise Stay ON YOUR Credit history REPORT?

3. Credit score counseling

Nonprofit credit history counseling agencies give free or low-expense expert services for borrowers who are battling to deal with their financial debt. One particular of these expert services features enrolling payday personal loan borrowers in a credit card debt administration system (DMP).

Below a DMP, a credit score counselor will enable you build a finances and debt compensation program. Credit counselors may perhaps be equipped to assistance you negotiate with payday loan companies to lock in a lower fascination price or lower the bank loan amount.

You can see a whole listing of certified nonprofit credit counselors on the Division of Justice web-site. If you however have questions about payday bank loan debt aid, study far more about financial debt consolidation by getting in touch with a knowledgeable financial loan officer on Credible.

Debtors WHO CONSOLIDATE Credit score CARD Personal debt CAN Conserve $2K+ ON Typical, Information Displays

Have a finance-relevant problem, but you should not know who to check with? E mail The Credible Revenue Specialist at moneyexpert@credible.com and your concern could be answered by Credible in our Money Pro column.

Here’s who has qualified for student loan forgiveness under Biden

Here’s who has qualified for student loan forgiveness under Biden

The Biden administration has forgiven federal student debt through four major loan forgiveness programs, including PSLF and borrower defense. (iStock)

Since President Joe Biden took office in January 2021, hundreds of thousands of Americans have seen their student loan debt wiped out — some of these borrowers have even had their balances reduced to zero.

While a significant portion of the population has benefited from federal student loan forgiveness, about 43 million borrowers still owe a total of $1.73 trillion worth of college debt, according to the Education Data Initiative. That’s an average balance of $39,351 per borrower.

Keep reading to learn who is eligible to have their student loans discharged. If you’re one of the many borrowers who will still owe student debt, consider your repayment options like student loan refinancing. Visit Credible to compare student loan refinancing offers from multiple private lenders for free without impacting your credit score.

BIDEN ADMINISTRATION ISSUES ‘FINAL EXTENSION’ OF STUDENT LOAN DEFERMENT

Who has qualified for student loan forgiveness under Biden?

The Department of Education has extended more than $11.5 billion worth of student loan relief to about 580,000 borrowers under the Biden administration through the following student loan forgiveness programs:

Learn more about each program in the sections below.

CAN AN INCOME-CONTINGENT REPAYMENT (ICR) PLAN HELP GET MY STUDENT LOANS FORGIVEN?

Total and permanent disability discharge

  • Borrowers who qualify: 364,000
  • Total debt forgiveness: $7.1 billion

The total and permanent disability (TPD) discharge program offers student debt relief for borrowers who are totally and permanently disabled. 

Qualified borrowers no longer have to repay their federal student debt, including Direct Loan Program loans, Federal Family Education Loan (FFEL) Program loans and Federal Perkins Loans. They also are not required to complete a TEACH Grant service obligation to have their loans forgiven.

Previously, borrowers had to apply for a TPD discharge, but the Education Department announced in August 2021 that these borrowers would automatically qualify for relief through an existing data match with the Social Security Administration (SSA). This resulted in about $5.8 billion in automatic student loan discharges during that time.

The Biden administration also reinstated $1.3 billion in TPD discharges in March 2021 for 41,000 borrowers who had not reported earnings information as part of this program. 

If you have a total and permanent disability but haven’t qualified for a TPD discharge, you may be able to apply for the program on the Federal Student Aid (FSA) website by providing documentation from your physician. And if you still don’t qualify for a TPD discharge, visit Credible to compare alternative student loan repayment programs like refinancing. You can browse estimated student loan rates from private lenders in the table below.

WHAT TO DO IF YOUR STUDENT LOAN SERVICER IS SHUTTING DOWN

Closed school discharge

  • Borrowers who qualify: 133,000
  • Total debt forgiveness: $1.6 billion

Student loan borrowers who attended a school that closed while they were enrolled or shortly after they graduated may qualify to have their federal student loans forgiven under the closed school discharge program.

The Education Department announced in June 2021 that 18,000 borrowers who attended the now-defunct ITT Technical Institute would have $500 million worth of student loans discharged under this program. Then in August 2021, the department extended an additional $1.1 billion in relief to 115,000 borrowers who left ITT on or after March 21, 2008, without completing their degree.

The Biden administration made these changes after a review of problems leading up to ITT’s closure. The department found that the school had been misrepresenting the “true state of its financial health,” allegedly misleading students into taking private student loans that were portrayed as grants.

“For years, ITT hid its true financial state from borrowers while luring many of them into taking out private loans with misleading and unaffordable terms that may have caused borrowers to leave school,” U.S. Secretary of Education Miguel Cardona said in a statement.

Private student loans aren’t grants, but they are a viable borrowing option for select student loan borrowers who have met the federal loan limits. You can learn more about these loans and compare estimated interest rates for free on Credible.

REFINANCING YOUR STUDENT LOANS CAN SAVE YOU $250+ ON YOUR MONTHLY PAYMENTS

Borrower defense to repayment

  • Borrowers who qualify: 92,000
  • Total debt forgiveness: $1.5 billion

The borrower defense to repayment program is available to students who were misled by a school involved in misconduct while they were enrolled. About 7,000 borrowers who received a closed school discharge also qualified for student loan forgiveness under the borrower defense to repayment program. 

The Education Department approved an additional 1,800 borrower defense claims in July 2021 for students of Westwood College, Marinello Schools of Beauty and the Court Reporting Institute. This resulted in approximately $55.6 million in relief, bringing the total borrower defense loan cancellations under the Biden administration to more than $1.5 billion for 92,000 borrowers.

The department is currently reviewing future rulemaking regarding borrower defense, holding public hearings to receive feedback in June 2021. You can apply for borrower defense on the FSA website. 

12 LENDERS TO CONSIDER FOR STUDENT LOAN CONSOLIDATION

Public Service Loan Forgiveness

  • Borrowers who qualify: 22,000
  • Total debt forgiveness: $1.74 billion

The Public Service Loan Forgiveness program (PSLF) offers federal student loan relief as an incentive for borrowers who work in a government or nonprofit profession. Eligible borrowers may have the remainder of their federal loan debt discharged after making 120 consecutive qualifying payments.

But the PSLF program came under fire for its abysmally low approval rate — 98{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of PSLF applications were rejected since the beginning of the program. The Biden administration opened a public inquiry into PSLF, where borrowers called the program “broken” and “confusing.”

After conducting a review of PSLF, the Education Department announced a significant overhaul to the program in October 2021. This limited waiver makes it easier for public servants like nurses and special education teachers to qualify for the program, as long as they move their federal loans into a Direct Consolidation Loan by Oct. 31, 2022.

The policy resulted in 22,000 borrowers becoming immediately eligible for $1.74 billion worth of loan forgiveness. An additional 27,000 borrowers will need to verify their employment to qualify for up to $2.82 billion worth of student loan relief.

LONGER STUDENT LOAN FORBEARANCE IS NEEDED, 40{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} OF BORROWERS SAY IN SURVEY

The department estimates that more than 550,000 borrowers will be, on average, two years closer to a loan discharge under PSLF thanks to these actions. In addition, borrowers who were previously denied PSLF are eligible to have their cases reviewed. 

To meet the PSLF eligibility requirements, borrowers must work for a qualifying employer in a nonprofit organization or federal, state, local or tribal government setting. You can use the PSLF Help Tool to see if you’re eligible. If you don’t qualify for PSLF, you may be able to repay your student loan debt on better terms by refinancing. 

Keep in mind that refinancing your federal loans into a private student loan would make you ineligible for PSLF in the future. You can learn more about student loan refinancing by contacting a knowledgeable loan officer at Credible.

ACA CALL CENTER WORKERS CAN BARELY AFFORD THEIR OWN HEALTHCARE, REPORT FINDS

Have a finance-related question, but don’t know who to ask? Email The Credible Money Expert at moneyexpert@credible.com and your question might be answered by Credible in our Money Expert column.

Syracuse unveils new loan program for small city businesses. (Some loans will be forgiven)

Syracuse unveils new loan program for small city businesses. (Some loans will be forgiven)

Syracuse, N.Y. – Modest business enterprise owners in Syracuse can apply for very low-interest loans starting currently under a $1 million program managed by the metropolis of Syracuse’s economic improvement arm.

The revenue could go rapid. Programs ought to be submitted to the Syracuse Economic Progress Corp. by no later than Dec. 31, Mayor Ben Walsh stated. Walsh is asserting the system at a news conference this early morning.

There are 3 types of financial loans centered on the sizing and form of enterprise. Financial loans for the smallest organizations – ‘’micro-enterprises’’ with 10 or fewer personnel – are forgivable under selected conditions. The loans can be applied for a broad wide variety of uses such as money upgrades, acquire of materials and stock and more.

In this article are 3 basic types:

Micro-company Fund: Financial loans of up to $5,000 are available at an interest charge of 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, repayable in two many years. The financial loans can be forgiven if the company retains its workforce, stays current on home taxes and satisfies other circumstances. To qualify, a company ought to have 10 or less workers.

Modest Organization Aid Fund: These financial loans of up to $25,000 are for enterprises that have 50 or fewer workforce and professional a decrease in sales during 2020 or 2021 or are positioned within just an eligible Census tract (see map). The fascination amount is 1.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, repayable in 5 decades.

Neighborhood Effects Fund: Organizations, nonprofit businesses, or enhancement entities with 50 or fewer staff members can implement for up to $200,000 for creating renovations or other authentic estate improvements inside a skilled Census tract. The interest rate is 2{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for 15 several years.

ARPA tracts

The spots outlined in black are Census tracts eligible for exclusive guidance below the federal American Rescue Strategy Act. Some actual estate advancement jobs in these parts are are suitable for SEDCO financial loans.

The Syracuse Financial Progress Corp., or SEDCO, is a regional enhancement company established by the metropolis. To utilize for a loan, business proprietors should finish a two-phase course of action:

1st, fill out an on the internet questionnaire at the SEDCO site. Then, a metropolis consultant will get hold of the small business to present an application variety for the ideal bank loan fund. Applications and supporting paperwork have to be submitted by noon Dec. 31.

Cash for the loans arrives from the $123 million Syracuse been given this year in federal stimulus money.

Between SEDCO and the Syracuse Industrial Improvement Agency, metropolis officials had previously offered $1.3 million in grants and financial loans to businesses recovering from the Covid-19 pandemic.