Biden student loans proposal is misguided. Income caps will be a nightmare.

Biden student loans proposal is misguided. Income caps will be a nightmare.

This weekend more than 460 gals will get unconventional letters in the mail: “We are composing to you with great information: Bennett College or university, in collaboration with the Rolling Jubilee Fund, has canceled the remaining unpaid equilibrium you previously owed immediately to the university.”

Bennett Faculty is a tiny liberal arts school in Greensboro, North Carolina, and a single of the country’s two Historically Black Faculties and Universities for gals. All advised, a lot more than $1.7 million of tuition-associated financial debt was erased for former college students, some of whom had balances in excessive of $20,000. Now, just about every solitary account the school experienced in collections has been wiped out as a no-strings-connected present.  

Implies testing and linked restrictions audio honest in idea. In observe, the results are like taxes, where by the privileged are improved in a position to hire accountants, navigate complexity, and enjoy connected rewards.

Why did the Rolling Jubilee Fund do this? The Rolling Jubilee is an initiative of the Personal debt Collective, the country’s initial union for debtors, which I assisted uncovered. For approximately 10 yrs, we’ve been primary the motion to force the government to terminate all university student debt. We made a decision to lover with Bennett School to get in touch with focus to the disproportionate affect the university student personal debt disaster is acquiring on Black girls and to force President Joe Biden to retain his campaign assure on pupil financial debt elimination for the country’s 45 million debtors.

But student mortgage holders are continue to ready for relief. Biden ought to be wiping out federal university student financial loans by means of an government purchase. He could ship letters like the one we just sent to former Bennett students, only to each and every one borrower in the state, lifting a crushing body weight from their shoulders. 

Most people today look to have overlooked that the president pledged as a applicant to remove a “minimum” of $10,000 for each individual single borrower, in addition to vowing to cancel all undergraduate federal loans for persons who attended community faculties and universities as nicely as personal HBCUs and minority serving institutions for people today who make considerably less than $125,000 a calendar year.

Sad to say, the White Dwelling appears identified to move the goalposts. This month, in speaking about personal loan cancellation, Biden reported probably $10,000 tied to an individual’s revenue would be forgiven for those people who generate less than $125,000. Debt cancellation is the appropriate detail to do. But $10,000 is nowhere close to enough, and it really should not be implies-examined in any way. In fact, these provisions are recipes for catastrophe. 

There are simply just no convincing factors to restrict aid to $10,000 or to exclude borrowers above an arbitrary cash flow threshold. Analysis reveals that most economic and social benefits circulation from canceling all university student credit card debt and to generating that cancellation universal: The improve for the economic system will be larger, the racial prosperity hole will correspondingly slim, and more life will be significantly improved.

For thousands and thousands of debtors, $10,000 will not make a dent in the enormous curiosity that has accrued on their balances. A modern analysis in Forbes confirmed that the total could have “little or no benefit” for several of the 9 million debtors at present on Money driven reimbursement strategies, which are developed to enable battling people today by reducing month to month payments and spreading their loans out for a longer period. Nevertheless these are some of the nation’s neediest borrowers.

Targeting student financial debt cancellation by implementing an income cap will only hurt the most vulnerable debtors — overwhelmingly people today who are low revenue, women and individuals of coloration — mainly because debtors will have to utilize and establish that they qualify somewhat than the cancellation taking place quickly. As a result, hundreds of thousands possible won’t know that they are entitled to relief, or how to get it. 

Education Office officers have themselves warned, indicates-testing cancellation (tying cancellation to earnings) is significantly simpler mentioned than accomplished. For instance, the Instruction Office does not have access to IRS information and many very poor people today are nonfilers, which signifies they can battle to verify their incomes as part of any application procedure. 

Instruction Division fiascos are all also prevalent. Just very last thirty day period a damning Authorities Accountability Workplace report in depth the failures of cash flow pushed reimbursement strategies: Despite the truth that thousands and thousands have been enrolled above nearly 3 a long time, only 157 lucky persons have been authorized for the forgiveness. The report identified that countless numbers of persons have been arbitrarily denied aid, with a lot of much more established up to are unsuccessful by a confusing and onerous process.

This is the fact the Biden administration have to facial area: Indicates testing and associated limitations sound reasonable in principle. In practice, the benefits are like taxes, the place the privileged are much better equipped to employ the service of accountants, navigate complexity and enjoy associated benefits.

The limits on loan forgiveness are doubly nonsensical given that almost every person would be screened in under the contemplated money cap. Only 5 per cent of scholar debtors are calculated to make much more than $125,000, and a lot of of these superior-earning borrowers nevertheless have reduced or negative internet prosperity

That signifies there is no need to have for the Biden administration to create elaborate systems to exclude wealthy men and women from cancellation. Definitely wealthy individuals do not have scholar loans since they (or, more possible, their dad and mom) can shell out the charge of tuition with no borrowing income. In other words, cancellation is currently suggests-analyzed: If you have financial debt, it signifies you require reduction.

Why is the president so resistant to this point? The remedy seems to lie in his stubborn and mistaken perception that a sizeable amount of debtors are white elite graduates of Ivy League institutions. But Ivy Leaguers make up significantly less than fifty percent of 1 p.c of all scholar debtors and are inclined to graduate personal debt-totally free thanks to a blend of comparatively affluent upbringings and generous college endowments. Student debtors are considerably far more probably to go to for-financial gain educational facilities or HBCUs.

As a substitute of lending credence to conservative talking points, Biden should really make an unapologetic circumstance for cancellation. Republicans and proper-wing pundits are spreading the lie that canceling scholar credit card debt is “regressive” — that it can help the prosperous. The president must contact their bluff. If pupil credit card debt cancellation in fact assisted the rich, Republicans would have carried out it by now.

The Biden administration can not afford to fritter away a historic option by turning a profitable plan into a political and bureaucratic fiasco — a Health care.gov 2.. Only this time, it won’t be stories of a crashing web site. It will be a self-imposed and avoidable bureaucratic, ethical and political disaster that further more excludes and disappoints the extremely people today Biden promises to care about and to whom he owes his 2020 victory.

Certain people are getting their student loans forgiven. Here’s how to see if you qualify

Certain people are getting their student loans forgiven. Here’s how to see if you qualify

Lawmakers have been producing promises for several years on scholar mortgage forgiveness.But for some Cincinnatians, it can be taking place correct now.Dr. Anisa Shomo is aware of all too nicely the superior price tag of a bigger training.She’s a family members drugs doctor at the College of Cincinnati Wellbeing.Receiving her diploma was a extensive, high priced course of action.”As millennials, the cost of training truly increased in a shorter total of time, so it was definitely excellent news when I was in healthcare college that there was this pathway,” Shomo, a relatives medicine medical doctor at UC Wellbeing, mentioned.Shomo was equipped to use the Community College student Personal loan Forgiveness Application, developed in 2007.Individuals like her who meet up with specific demands, such as doing work in a community or nonprofit sector for 10 yrs, are suitable to have their loans forgiven.And for Shomo, that instant just came.”And so I took the letter off the table and I opened it up and it reported ‘congratulations!'”Just like that far more than $53,000 compensated off.”It claims I have contented my obligation and no added payments are needed on these loans,” reported Shomo.Shomo is aspect of the very first wave of employees who are receiving these letters.”I’m just seriously grateful for the reason that I have carried out the do the job for the earlier 10 years I’ve labored with the group that I have needed to perform with and it is really truly terrific to be rewarded for this sort of perform. It truly is not quick. You might be typically working in underfunded health clinics and not with all the means that you will need,” claimed Shomo.Now, this isn’t some application in which they are handing out absolutely free income.The eligibility demands are stringent — and they start with in which you work.You have to have a career for federal, state, area or tribal authorities or for a qualifying nonprofitYour work has to be full-timeYou have to get out immediate loansYou have to be generating an hard work to repay them — by making use of an cash flow-driven repayment planYou have to make 120 qualifying payments on time.Shomo explained anyone who utilized from 2016 to 2020 and did not get it really should utilize yet again.

Lawmakers have been producing guarantees for several years on college student mortgage forgiveness.

But for some Cincinnatians, it really is taking place appropriate now.

Dr. Anisa Shomo is aware of all as well very well the substantial cost of a larger schooling.

She’s a relatives drugs medical doctor at the University of Cincinnati Health.

Having her degree was a prolonged, highly-priced process.

“As millennials, the selling price of instruction definitely increased in a quick sum of time, so it was definitely fantastic information when I was in professional medical college that there was this pathway,” Shomo, a loved ones drugs medical professional at UC Health and fitness, explained.

Shomo was equipped to use the Public Student Mortgage Forgiveness Application, established in 2007.

People like her who fulfill certain needs, including performing in a community or nonprofit sector for 10 a long time, are suitable to have their financial loans forgiven.

And for Shomo, that instant just came.

“And so I took the letter off the table and I opened it up and it said ‘congratulations!'”

Just like that extra than $53,000 compensated off.

“It claims I have content my obligation and no more payments are essential on these loans,” claimed Shomo.

Shomo is aspect of the initially wave of personnel who are having these letters.

“I am just really grateful for the reason that I have finished the work for the past 10 many years I’ve worked with the neighborhood that I have wanted to perform with and it’s seriously fantastic to be rewarded for this sort of perform. It really is not easy. You are usually doing work in underfunded health clinics and not with all the means that you need,” claimed Shomo.

Now, this just isn’t some application in which they are handing out cost-free dollars.

The eligibility prerequisites are strict — and they get started with where you work.

  • You have to have a task for federal, state, neighborhood or tribal governing administration or for a qualifying nonprofit
  • Your career has to be whole-time
  • You have to acquire out direct loans
  • You have to be producing an hard work to repay them — by working with an profits-pushed compensation strategy
  • You have to make 120 qualifying payments on time.

Shomo mentioned any one who utilized from 2016 to 2020 and failed to get it should utilize all over again.

Biden plunges into the risky politics of student loans

Biden plunges into the risky politics of student loans
Placeholder while article actions load

The news had just emerged that President Biden was moving toward canceling at least some student loan debt, and Donald Trump Jr., in the final days of campaigning for U.S. Senate candidate J.D. Vance in Ohio last month, did not mince words as he excoriated the idea at rallies.

“Biden essentially wants blue-collar workers like truck drivers — who didn’t have the luxury of going to college to get drunk for four years — to bail out a bunch of upper-middle-class kids who chose to spend tens of thousands of dollars that they didn’t have on worthless gender study degrees,” Trump told The Washington Post later, elaborating on his message to voters.

Sen. Mitt Romney (R-Utah), a more moderate Republican, jumped in as well, suggesting the move was little more than a political payout to win votes. “Other bribe suggestions: Forgive auto loans? Forgive credit card debt? Forgive mortgages?” he wrote on social media.

With Biden now moving closer to an executive order canceling some portion of student debt, Republicans are seizing on the issue to burnish their favored portrait of the two parties: Democrats, they say, champion the privileged elites, while Republicans support America’s down-to-earth workers. It’s a message that reflects the turbulent, risky politics of student debt for Biden, who has expressed both support and skepticism about student loan forgiveness.

Liberals respond that a sweeping loan cancellation program would provide critical help for struggling Latino, Black and young people amid a tough economy. Still, even some Democrats are wary of a critique that their party is aiming to help people who chose to take on debt at the expense of those who didn’t.

The issue of high college tuition costs emerged as a major plank in Sen. Bernie Sanders’s 2016 presidential campaign, when the progressive leader urged supporters at his campaign events to call out how much debt they were carrying. In the 2020 campaign, Sen. Elizabeth Warren (D-Mass.) pushed slashing student debt, and even Senate Majority Leader Charles E. Schumer (D-N.Y.) has now taken to prodding Biden on the issue.

But Biden has not been quick to embrace it as president, at times also raising fairness issues. At a CNN town hall early in his presidency, he referred to the “billions of dollars in debt for people who have gone to Harvard and Yale and Penn” and asked rhetorically, “Is that going to be forgiven, rather than use that money to provide for early education for young children who come from disadvantaged circumstances?”

Biden at odds with some Democrats over student loans

More recently, Biden has signaled that any debt forgiveness plan would include sharp limits, for example erasing no more than $10,000 in debt for any individual and benefiting only those who make less than $125,000 a year.

The conservative-liberal divide on the issue is more than a policy dispute; it reflects contrasting world views, at a time when those with a college degree are more likely to be Democrats and those without such degrees lean Republican. Some conservatives increasingly portray college as leftist, elitist and useless; liberals, on the other hand, describe it as a vital, if overpriced, path of advancement for the underprivileged.

When The Post reported late last month that Biden had suggested to a group of Latino lawmakers that he was now open to canceling student debt, the Ohio Republican primary for the Senate was in its final days, and the candidates seized on the issue to flaunt their anti-establishment credentials.

One GOP hopeful, former Ohio Republican Party chair Jane Timken, said at a campaign event that forgiving college debt was part of an “extreme left” agenda, adding: “How is that fair to the kids who never went to college, who are working as welders and plumbers? They should have to pay for those kids who can’t get a job or won’t get a job?”

Vance, who ultimately won the nomination, tweeted that loan forgiveness is “a massive windfall to the rich, to the college educated, and most of all to the corrupt university administrators of America.”

In an interview, Sen. John Thune (R-S.D.), the second-ranking Senate Republican, predicted that Biden would court a backlash if he follows through on loan forgiveness.

“I think you’d have a revolt,” Thune said. He professed himself baffled by the political calculation, saying, “I understand they’re maybe trying to help a certain constituency, but I think the constituency that is going to have major heartburn over this is significantly larger, and is going to meet that kind of announcement with a lot of hostility.”

Some Democrats stressed that any loan cancellation program would have to be carefully crafted. “I’d be open to some of it,” said Cheri Beasley, a Democrat running for Senate in North Carolina. “But I think it’s really important to be thoughtful about the impact on our economy.”

Others said that because it would probably take the Education Department several months to implement such a policy, the political benefits could be limited.

Progressives contend that the idea has far broader support than opponents admit. In January, an Economist/YouGov poll found that 49 percent of Americans supported forgiving student loan debt from public schools, while 35 percent were opposed. As for adults under 30, a Harvard Kennedy School poll in April found that 85 percent supported some form of government action on student debt, though only 38 percent favored total cancellation.

All told, 45 million Americans held $1.6 trillion in federal student loans as of December, the latest available data from the Education Department. Canceling $10,000 would wipe clear the balances of roughly a third of borrowers, while leaving another 20 percent of people with less than half of what they owe.

And Democrats believe they’ll be rewarded for wiping out at least some of that debt.

“We desperately need to motivate young people to vote to have a chance to win this election,” said Mike Lux, a Democratic political strategist who is in contact with the White House. “They are the people who are most likely to be burdened by student debt, the people most likely to see those bills coming. I think they would be far more motivated to vote if they saw something tangible to help them.”

Such thinking may be playing into Biden’s calculus. A few hours before he told Hispanic lawmakers that he was ready to move on student debt, a half-dozen of Biden’s top advisers gathered in the Roosevelt Room at the White House to hear from two Harvard students who had studied the political views of young Americans.

Among the attention-grabbing findings of Alan Zhang and Jing-Jing Shen, the chair and former chair of the Harvard Public Opinion Project: Even among those who had not attended college, 57 percent favored debt cancellation.

That seemed to resonate with those listening, including White House Chief of Staff Ron Klain, presidential counselor Steve Ricchetti, senior adviser Cedric L. Richmond and Deputy Chief of Staff Jen O’Malley Dillon. Afterward, the two students were called into the Oval Office by the president, where they chatted for about a half-hour about problems facing the country and their personal aspirations.

Progressive leaders hope to motivate voters like Philip Beechler, a 32-year-old Democrat in Atlanta, who noted that Biden promised during his campaign to forgive at least some student debt. “I know every campaign promise is not going to come to fruition,” said Beechler, a data analyst. “But why have people waiting for nothing?”

If Biden does not follow through, he added, “I’m not going to go vote Republican. But maybe I won’t vote for the first time in 13 years.”

Beechler, who said he’s carrying nearly $80,000 in federal student loans, disputed the Republican characterization of borrowers as spoiled and entitled. He received no family support when pursuing his bachelor’s degree in political science, he said, so he worked two minimum-wage jobs. He started at the College of Charleston in South Carolina and completed his bachelor’s at the University of North Carolina at Charlotte, and said his loan balance is so high in part because he frequently placed his loans in forbearance when he was struggling.

Ultimately, it took him seven years to complete his degree, and even then it has not been easy to gain his financial footing and repay his loans. “I’m not lazy, not terrible with money and I work really hard,” Beechler said. “I just want the same things that other generations had — financial security.”

To many liberals, the problem is not selfish students, but an American higher education system that is prohibitively expensive, with the poor and minorities facing especially high hurdles and the most prestigious colleges often out of reach for middle-class students.

Among the fastest-growing categories of student loan borrowers over the past two decades are Black students and people ages 50 and older, according to the most recent Federal Reserve data. The median income of households with student loans is $76,400, and 7 percent of borrowers are below the poverty line.

Rep. Mondaire Jones (D-N.Y.) said he had “a lively debate” with Biden on debt forgiveness several weeks ago during a presidential meeting with progressive lawmakers. “I noted that it wasn’t just an issue of racial justice and gender justice, but also LGBTQ+ justice,” Jones said. “And I found him to be very sympathetic.”

Jones argued that while college costs have soared in recent years, wage stagnation means that even graduates of top institutions are often making less than many think. And like other liberals, he objected to the idea of limiting loan forgiveness to people below a certain income level, saying government initiatives aimed at specific groups often become less popular.

“That approach of means-testing — of pitting Americans against one another — has proven to be ineffective at building popular support for the transformative social programs in this country,” Jones said. “The reason Social Security and Medicare have such broad support is because they are not means-tested, they are universal.”

The most conservative Democrat in the Senate, Joe Manchin III of West Virginia, who represents a state with many Trump voters who are not college educated, urged Biden to be cautious in offering any broad loan forgiveness program.

“I hope the president and all of his advisers look at that very carefully before they do it,” Manchin said. “I think we all want to do something, and we should do something. We can do something, but more in a responsible way.”

Why there’s a push to forgive student loans but not other debt

Why there’s a push to forgive student loans but not other debt

Activists hold a college student bank loan forgiveness rally near the White Household on April 27, 2022.

Anna Moneymaker | Getty Visuals News | Getty Illustrations or photos

All through the discussion around college student mortgage forgiveness, 1 commonly requested query is why terminate education and learning credit card debt, and not, say, credit rating card financial debt or home loans?

What is so distinctive about scholar financial loans?

In some strategies, nothing at all. People borrow for their education for the same reasons they borrow for something else — they are not able to find the money for the product or services on their have.

But there are some meaningful explanations that explain why you can find been these a sturdy, unified and widening movement to get student loans canceled. Here are 4 of them, in accordance to authorities.

1. The system is ‘broken’

Even before the pandemic, and when the economic climate was booming, reimbursement difficulties ended up widespread between federal pupil financial loan debtors.

The country’s remarkable education and learning financial debt equilibrium exceeded $1.7 trillion and posed a more substantial load to households than credit history card or automobile debt. Roughly a quarter of bank loan holders — or 10 million men and women — were estimated to be in delinquency or default.

About a fifth of federal pupil bank loan debtors attended for-earnings colleges, a lot of of which have come underneath fireplace for deceptive college students and failing to deliver them with a quality education and learning. Fifty percent of pupils who go away these educational facilities end up defaulting on their loans.

The U.S. Department of Education and learning has also not built fantastic on quite a few of its claims, mentioned Persis Yu, policy director for the Student Borrower Security Center.

A lot more from Particular Finance:
Here is how to invest in new operate garments on a finances
These are the very best and worst U.S. locations to die
Be absolutely sure to deal with this chance as you in the vicinity of retirement

Tens of millions of people today enrolled in courses that are intended to lead to personal debt forgiveness just after a sure interval of time, which include revenue-pushed repayment plans and the preferred community service mortgage forgiveness software, have been stuck continuing to pay and rejected for the reduction, normally for technological and confusing causes.

The businesses that service federal college student financial loans have been accused of providing debtors erroneous and incomplete information.

“There have been decades of mismanagement, abusive techniques and common incompetence, which has resulted in thousands and thousands of debtors missing out on numerous of the crucial programs and benefits afforded less than the legislation,” Yu said.

2. Most financial loans will not be repaid in any case

One particular of the arguments for forgiving college student loans is that tens of millions of borrowers will in no way fork out off their credit card debt anyway. In the meantime, they deal with a host of outcomes from acquiring tens of hundreds of pounds on their own equilibrium sheets, like difficulty shopping for a residence and starting off a enterprise.

In accordance to a tough estimate by bigger education and learning specialist Mark Kantrowitz, prior to the pandemic, just about 50 percent of federal scholar loan debtors, or 20 million men and women, had been in reimbursement — the relaxation were in deferments or forbearances or had stopped spending their loans altogether.

3. There is certainly (essentially) one particular creditor

Federal student financial debt is much from the only personal debt burdening American households. Domestic financial debt, including the balances on credit score cards and mortgages, exceeds $15 trillion.

Canceling any other sort of personal debt other than federal pupil financial loans, even so, would be a lot much more logistically and monetarily difficult. Hundreds of banks underwrite credit playing cards and automobile loans, whereas it really is mainly just a single celebration — the U.S. federal government — that owns federal student credit card debt.

With the ache of inflation hitting households and panic that a economic downturn could be on the horizon, advocates level to university student personal loan forgiveness as a fairly easy way for President Joe Biden to provide aid to the nation, particularly immediately after most of his social shelling out agenda has been derailed by Congress.

“In contrast to money owed held by private collectors, the president has the authority to eliminate federal scholar financial loan financial debt with the stroke of a pen,” Yu claimed.

4. Schooling is a general public fantastic

Although credit rating card personal debt, automobile loans and residence mortgages are mostly a non-public profit, “a greater schooling is component of the cloth of modern society, with equally a general public and personal benefit,” Kantrowitz reported.

Higher education graduates spend much more than twice the federal cash flow tax of higher school graduates, he included. “It’s not just a very good financial commitment for the federal governing administration — there is no superior investment decision.”

Those people who graduate college or university also have decrease unemployment premiums and are much less likely to want community benefits these as Medicaid and food stuff stamps, Kantrowitz included, “decreasing the load on modern society.” They also vote and volunteer at larger concentrations than individuals devoid of a bachelor’s degree.

Continue to, tuition at faculties has skyrocketed about time, though condition assist and grants have declined. As a final result, the value of greater schooling has more and more been put on people.

The average bank loan equilibrium at graduation has tripled to $30,000 from $10,000 in the 1990s. Around 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of college student bank loan debtors owe much more than $100,000.

“It really arrives down to this concept that credit card debt-free faculty is a public excellent, and just as we assume about K-12 education and learning as serving the community desire, the wellbeing of our overall economy and the well being of our democracy, so, as well, should really we assume about better education,” previous Schooling Secretary John King told CNBC not long ago.

COVID-19 relief fraud led to billions in taxpayer-funded Paycheck Protection Program loans lost

COVID-19 relief fraud led to billions in taxpayer-funded Paycheck Protection Program loans lost

Officers nevertheless are not able to say precisely how numerous billions of pounds in Paycheck Safety Method loans fraudsters built off with in the past couple of many years, but they know it is a ton.

Reports and estimates range, but a number of inspectors common have said the total benefit of the fraudulently obtained financial loans as a result of the Paycheck Defense Method is very likely to complete in the billions. A total of $800 billion was earmarked for relief by the Tiny Enterprise Administration throughout the early days of the COVID-19 pandemic.

“I are not able to rule out that the fraud could be not only in the tens of billions, but possibly, as some have believed, upwards of $100 billion,” Division of Justice Inspector Normal and Pandemic Reaction Accountability Committee (PRAC) Chair Michael Horowitz informed Fox News. “But it truly is also early for me to explain to you how higher that amount is going to go. I know it can be in the billions.”

PPP FRAUD Prices Introduced Against CEOS, Famous people IN Georgia

Fox News spoke with Inspector Common Horowitz in his ability as chair of the Pandemic Reaction Accountability Committee, exactly where he leads a roundtable of the government’s inspectors standard on chasing down fraud and inefficiencies in pandemic relief plans. The team is functioning on amassing knowledge and building government-large suggestions to steer clear of squander and criminality in long term crises.

“PRAC has 21 inspectors standard doing the job with each other. We satisfy routinely, we assess notes, we share details, we share means,” Horowitz said. “It has been, I imagine it is really truthful to say, for us as a local community, a recreation changer. But by creating certain we are collaborating and working proficiently, sharing details, sharing details, sharing means. You won’t be able to oversee $5 trillion with just a handful of individuals.”

Horowitz explained there are key spots in which the federal government failed to initially enact safeguards from fraud in the PPP financial loan application.

“Nicely, I think first and foremost, confirm the id of the individual who’s implementing. Identification theft has been a very major trouble, and what we discovered was that essential techniques to determine identification weren’t undertaken,” Horowitz said.

He provides that a essential verification examine that runs purposes against the Treasury Department’s “do not spend” program, which flags men and women and entities who have indicators of fraud, was overlooked all through the early times of the system.

ARCHEGOS Proprietor Invoice HWANG, Former CFO Billed WITH FRAUD AND Hit WITH SEC Grievance

“It turned out 57,000 financial loans ended up compensated out in individuals to start with couple of months to men and women who ended up on the do not spend listing,” he informed Fox Information. “There was not a check on it. Which is a process that was by now in area that could have very easily been checked.”

He also cited the Social Security Administration’s deceased individual’s checklist as a database that could’ve been applied to suppress some cases of fraud in the program.

Horowitz is not the only watchdog elevating flags on pandemic-relief fraud. Fox News spoke to many authorities officials included with coming up with, implementing and accounting for massive federal government investing to counter the worst financial results of the pandemic.

TENNESSEE Guy PLEADS Guilty TO Applying COVID-19 Support FOR HIMSELF

“We issued three white papers earning positive that folks understood the importance of setting up the correct interior control framework to assure that, whilst we have these factors shifting speedily, that the control construction could stand the exam of fraud,” Small Enterprise Administration Inspector Basic Hannibal “Mike” Ware advised Fox Information. “We understood that fraud was heading to come about regardless. Simply because this considerably cash, shifting that rapidly, the fraudsters would be lining up at the doorway, which is what we observed.”

Ware was 1 of the 1st oversight officials to alert Congress and other governing administration officials about what was envisioned to be rampant fraud in a amount of pandemic-aid applications. The Smaller Enterprise Administration was in demand of dispersing the PPP loans, and Ware said the agency processed “14 years’ worth of lending inside of 14 times.”

Gene Sperling Biden adviser

Gene Sperling, a senior adviser to President Biden who earlier served beneath the Clinton and Obama administrations. (White Dwelling)

“It was unquestionably a prevalent issue from the start off of the plan,” Ware stated. “… If these controls are not in location, they’re likely to be susceptible to a big amount of fraud risk.”

Gene Sperling is a particular adviser to President Biden and the architect of the American Rescue System, the administration’s flagship COVID-aid laws. He mentioned the latest administration inherited significant quantities of preventable fraud from the Trump-period pandemic-reduction designs.

“It was no top secret that we were being inheriting substantial fraud in small business loans and unemployment that took put in 2020, specifically at the onset of the pandemic,” Sperling instructed Fox Information.

Guy PASSES OUT IN NORTH CAROLINA COURTROOM Upon $1.7 MILLION COVID FRAUD Responsible VERDICT

Sperling stated he’s labored closely with PRAC and the SBA to understand and apply fraud controls for present and long run crisis reduction systems. He’s designed tips to numerous organizations and is drafting an executive get to deal with id theft, which fueled a lot of the PPP loan fraud.

“Whilst it was understandable that the emphasis in 2020 was on acquiring small company relief out as quickly as doable, I believe that long run emergency laws and administrative action can totally do much better in trying to keep basic guardrails even in emergencies,” Sperling reported.

By earning the PPP mortgage resources widely obtainable with no implementing front-finish safeguards versus improper payments, Congress, which eventually passed the pandemic-aid laws, opened the flood gates for fraudulent activity.

PPP FRAUD CAN BE Discovered, TRACKED ON Internet site Produced BY Software package ENGINEER

The unofficial enforcement design adopted by the program’s architects is recognized as chase and pay, the place the income is dispersed promptly with the knowledge that fraud is possible to take place, and regulation enforcement businesses examine and go after criminals later on. Watchdogs say the alternative in between pace of dispersal and verification guardrails is a wrong a person.

“I don’t believe that a suitable managed setting has to be sacrificed at the altar of pace,” Ware mentioned. “I imagine that they could go hand in hand if thought out beforehand.”

Tom Schatz, president of the Citizens Against Governing administration Waste, has been raising the flag on governing administration inefficiency and incompetency for many years. He is not astonished that the PPP financial loan program was ridden with fraud. The exact failures in pandemic-relief verification have existed across govt for yrs.

BITCOIN Case: Fulfill THE Pair WHO ALLEGEDLY Scammed $4.5B IN CRYPTO

“The federal govt, they are however working with paper. They really don’t confirm, they’re in a rush to get it out, they are not skilled sufficiently,” Schatz told Fox News. “So just about every thing that could go incorrect does go wrong. And when the pandemic came along, they were being fully unprepared for the scope of what necessary to be done.”

With billions of taxpayer income taken out of governing administration coffers and place into the pockets and lender accounts of fraudsters, the government has experienced no scarcity of investigations to undertake. In California, two cases are illustrative to the type of brazen fraud and lavish dwelling observed so normally in PPP mortgage fraud circumstances.

According to court documents received by Fox Information, the Ayvazyan spouse and children labored collectively to defraud the Paycheck Defense Software of up to $18 million. They ended up caught and positioned on home arrest. With prison on the horizon, Richard Ayvazyan and his spouse Marietta Terabellian reduce off their ankle displays and fled to Montenegro, leaving their two teenaged young children at the rear of.

Ayvazyan has been sentenced in absentia to 17 a long time in jail his wife has been sentenced to six decades. Both of those are awaiting extradition to the United States.

The Ayvazyan household worked to defraud the Paycheck Safety Software of around $18 million and are at this time awaiting extradition. 

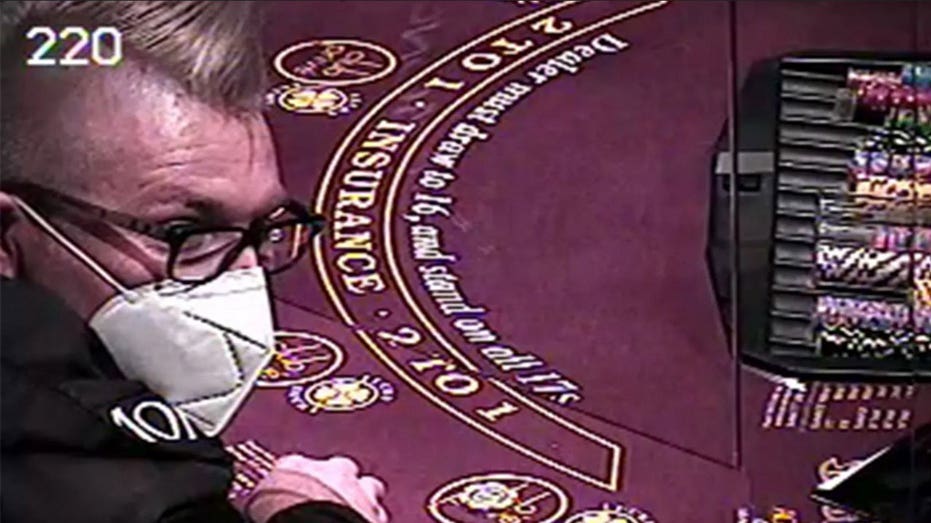
In yet another scenario, Andrew Marnell adopted fake identities to fraudulently obtain up to $8.5 million in PPP financial loans. He applied the cash to fund risky inventory marketplaces and are living big in Las Vegas casinos and inns. He has pleaded responsible and is scheduled to be sentenced in July.

Fraud in the Paycheck Defense Application isn’t constrained to career criminals and wannabe stock market traders. In some conditions, properly-recognized and prosperous individuals couldn’t resist the option to defraud the government out of a several million dollars.

Previous NFL huge receiver Joshua Bellamy, who was at first drafted in 2012, carved out an eight-12 months vocation in the league, earning above $8 million.

Andrew Marnell used different phony identities at casinos to fraudulently get $8.5 million in PPP loans. (Justice Department)

It’s alleged that he bilked the PPP Personal loan System for $1.2 million and put in some of the dollars on luxurious jewelry and stays in Florida casinos. He pleaded guilty to conspiracy to dedicate wire fraud and was sentenced to a few years in prison.

The scamsters operated freely while respectable little organization entrepreneurs had problem in securing funds to keep their personnel during the worst of the pandemic.

Nancy Calamusa owns New Jersey Pediatric Feeding Associates, a non-public health-related treatment facility that allows feed infants with health care problems that preclude them from ingesting on their very own. She suggests she was at first denied 7 moments for PPP financial loans. Her organization was ready to stay afloat, but not devoid of downsizing of her employees and availability of expert services.

“I followed the policies. I did what I was meant to do. I was instructed that I could only, you know, use for X amount of bucks, which is what I did,” Calamusa informed Fox Information. “I did not acquire far more than I was permitted to. I didn’t defraud the govt by lying and saying I had additional workforce.”

INDIANA EX-On line casino MAGNATE PLEADS Guilty TO TAX FRAUD INVOLVING CONTRIBUTIONS TO POLITICAL Action COMMITTEE

“It is really the tiny individuals. It can be minority enterprise owners. It’s gals business enterprise entrepreneurs. It’s all of us who are having difficulties.”

The divide in between regular economical establishments, which the bulk of authentic small organizations count upon, and huge tech monetary corporations is a different driver of fraud in the Paycheck Protection System. Banking companies would often have ongoing relationships with enterprise entrepreneurs and their very own electronic verification techniques that served stymie fraud makes an attempt in advance of they attained the SBA.

Watchdogs say this is not the case for some economical know-how companies. Congress is presently investigating 4 organizations, BlueVine, Kabbage, Cross River Bank and Celtic Lender. All four have been cited by numerous experiences as facilitating a substantial amount of money of fraud in the application.

The PPP program unquestionably saved many American modest businesses afloat for the duration of the worst of the pandemic. It also without doubt lined the pockets and financial institution accounts of felony fraudsters to the tune of $100 billion or more.

“It truly is systematic failure both in the executive branch and in Congress, where the genuine obligation lies with receiving this under management,” Schatz explained. “… These reviews just sit in a pile or they come up for hearings and then nothing’s completed.”

Simply click Below TO Read through Much more ON FOX Business

The problems from fraud in the Paycheck Security Plan is completed and the plan has considering the fact that ended. Still, Horowitz is aware of that regulation enforcement investigations and authorities initiatives to recoup the money will be ongoing for decades.

“So, to the common taxpayer, I say we as oversight IG’s, as inspectors general, we are on the situation,” Horowitz claimed. “We’re receiving facts out there to the public. We imagine transparency is the ideal disinfectant.”

Biden’s 3 choices on student loans

Biden’s 3 choices on student loans

In advance of abortion legal rights seized the countrywide spotlight this 7 days, college student loans, and competing proposals for how to cope with the practically $1.7 trillion of debt owed by much more than 40 million People, have been at the top of the White House’s agenda. President Joe Biden would seem to be warming up to a program to cancel at minimum some amount of financial debt prior to the present pause on bank loan payments expires in September — just weeks prior to the midterm elections.

Biden was never a big supporter of employing the presidency to cancel debt, but soon after meeting with users of the Congressional Hispanic Caucus final 7 days and facing plummeting approval scores in an election year, stories counsel that motion is coming. His push secretary and chief of staff have each mentioned that he’ll announce a approach, or lengthen the current payment pause once more to have more time to make a decision.

Biden has presently extended the pause 4 situations (former president Donald Trump issued the to start with pause, then extended it two times), amounting to about $200 billion value of personal savings, but force from liberal activists and Democratic lawmakers is setting up. College student loan experts advised Vox it’s crucial to use two frames to comprehend what variety of personal debt reduction is coming: the amount of cash that would be forgiven and who gets that forgiveness.

Progressives want Biden to go large, pushing for the greatest amount of forgiveness with the lightest eligibility requirements. They say the stakes are significant for Biden and his celebration, provided the significant chance that Democrats get rid of manage of Congress after elections this year—in section since of small turnout from Democratic voters in midterm elections and lackluster enthusiasm from activist-minded young voters and other members of the celebration foundation.

The initial state of affairs: Biden cancels up to $10,000 of student financial loans

This seems to be a likely selection. In the 2020 Democratic primaries, Biden stated he supported congressional motion to get rid of up to $10,000 of pupil loans, even though his rivals to the remaining argued for more bold proposals. Reports recommend he has considering the fact that develop into much more amenable to employing government motion to terminate federal loans, but he doesn’t appear most likely to put into practice this alternative without the need of some conditions.

“[T]he goal, suitable, is to make absolutely sure it is specific at people who require enable the most,” White Property push secretary Jen Psaki mentioned very last 7 days. Administration officials have been debating all those eligibility necessities, which could contain an money-based mostly restrict employing tax returns or pay back stubs (most likely to be a $125,000 income cap), regardless of whether the institution a borrower attended was a community or private faculty, the form of bank loan that was taken out, and whether or not the personal loan was made use of for undergraduate or graduate reports.

The move would surely give aid, canceling out personal debt for about 32 p.c of borrowers, or about 13 million men and women, according to an analysis geared up for Sen. Elizabeth Warren (D-MA) by students for the Roosevelt Institute, a progressive think tank. Two million Black borrowers would see their credit card debt erased, and among the those people borrowers who now owe a lot more than they did when they took out a mortgage, this level of aid would zero out the credit card debt of 14 percent of those debtors.

But the normal pupil debt that Individuals keep is about $30,000 — that means the extensive majority of credit card debt holders would nevertheless be on the hook for payments. Any total of forgiveness is unpopular with conservative figures, and progressives like Rep. Alexandria Ocasio-Cortez (D-NY) argue that the figure would not make a significant volume of change for several men and women. And the $10,000 determine would charge about $373 billion to roll out— about as considerably as the amount the federal govt has used on welfare (the Momentary Assistance for Needy Households method) in the very last 20 decades.

Even now, this transfer has broad assistance, together with among younger people, and if canceling any quantity of scholar financial debt contributes to inflation, this option inflicts the minimum problems.

The 2nd scenario: Biden cancels in between $10,000 and $50,000 of college student loans

This choice appears to be a little considerably less probably, but not out of the query. Biden has reported he is searching at under $50,000 of forgiveness per individual, about what Warren and Senate Majority Chief Chuck Schumer (D-NY) have demanded.

Biden probable wouldn’t go to the optimum greenback volume below and would in all probability adhere to the $125,000 revenue cap, experts explained to me. But any added $10,000 in relief more than the 1st $10,000 would make enormous variances for the the very least properly-off debtors, in accordance to the Roosevelt authors: “Every greenback of scholar financial debt cancellation counts, but bigger is superior for advancing racial fairness and economic stability,” Charlie Eaton, an assistant professor at UC Merced, and 4 other students produce.

With $20,000 of reduction, university student personal loan credit card debt for fifty percent of debtors, about 20 million folks, would be erased. Every single additional $10,000 increase benefits in approximately an added 10 per cent increase in financial debt-free of charge borrowers. But that comprehensive $50,000 determine would expense about $1 trillion — a lot more than has been invested on Pell Grants or housing guidance because 2000 — and has decreased while wide aid amid Democrats, independents, and young people. It would also very likely worsen inflation somewhat, while not as substantially as full debt cancellation.

The third state of affairs: Biden cancels all pupil personal loan credit card debt for every person, or for borrowers with extra than $50,000 of debt

This possibility has exceptionally small odds of happening, not only simply because Biden has claimed that much more than $50,000 of aid is off the desk. The whole $1.7 trillion value tag would be a lot more than the federal governing administration has spent on both the earned cash flow tax credit rating or unemployment insurance coverage given that 2000, and would maximize the inflation price by involving .1 and .5 share factors in excess of a 12-thirty day period interval, according to the fiscally conservative Committee for a Responsible Federal Finances. Universal debt cancellation would also disproportionately advantage a ton of the wealthiest Individuals, because much more than 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of outstanding personal debt is owed by individuals with graduate levels.

Still, progressives are pushing for this choice most difficult, and teams like the Scholar Credit card debt Crisis Center are contacting for a suspension of any eligibility specifications or purposes. Herein lies a pressure: Targeting relief at all goes a very long way towards generating absolutely sure the most affordable-cash flow borrowers get the bulk of the enable, but the Office of Instruction lacks the signifies to apply a massive screening exertion to evaluate applications. Right now, the Division is currently having difficulties to carry out more compact, qualified reduction attempts the Biden administration has already rolled out, according to Adam Minsky, an impartial pupil financial debt attorney.

“Even if it’s rather wide [requirements], there are a lot of respectable problems that some kind of suggests tests or other mechanisms to limit eligibility could be a enormous dilemma administratively,” he explained. “The Division of Training is presently strapped trying to quickly put into practice all of these variations, and you’re going to insert one thing else on leading of that that probably could impression tens of millions and millions of borrowers.”

Inaction appears unlikely, but any of these moves is a political gamble. Although some variety of reduction polls well, it is not the major worry of most voters. As the Atlantic’s David Frum has written, pupil-personal loan forgiveness carries the chance of getting witnessed as “a tax on the voters whom the Democratic Social gathering most desperately wants to get back,” non-college or university-educated and doing work-course Us residents, although also slowing attempts to combat inflation and only leaving some of the most progressive users of his social gathering joyful.

No matter of which route is picked out, Natalia Abrams, the president of the College student Personal debt Crisis Middle, told me progressives will have gained at the very least a person battle. The president’s legal authority to cancel university student credit card debt is an open issue, but “if this happened, President Biden will be agreeing that the President and the Department of Training do have the authority to cancel college student credit card debt,” Abram mentioned. “We can proceed to push for extra. We can agree that this is a lever and if they can cancel $10,000, they can cancel $50,000. And then they can cancel all of it.”