Biden administration cancels $5.8 billion in student loans. More borrowers could see relief soon

Biden administration cancels $5.8 billion in student loans. More borrowers could see relief soon

The U.S. Department of Schooling canceled about $5.8 billion in excellent scholar financial loans for much more than 560,000 borrowers in the premier one personal loan forgiveness action taken by the governing administration to date, the division introduced Wednesday. 

The cancellation applies to all those people who attended colleges operated by the now-defunct Corinthian Schools, one particular of the major for-earnings education and learning businesses that submitted for Chapter 11 bankruptcy in 2015. 

Corinthian Colleges has faced quite a few lawsuits because its founding in 1995 — but maybe the most noteworthy is from 2013, when Vice President Kamala Harris sued Corinthian although she was legal professional normal of California for “deceptive and bogus promoting and recruiting” between other allegations, according to the department.

“As of right now, each student deceived, defrauded, and pushed into debt by Corinthian Schools can relaxation assured that the Biden-Harris administration has their back again and will discharge their federal scholar loans,” U.S. Secretary of Education and learning Miguel Cardona explained in a assertion.

Qualifying debtors will not likely need to fill out the application to receive the reduction, either: it will be automated, and they are predicted to be notified in months, the office explained. 

Wednesday’s information comes as the Biden administration considers broader scholar financial loan forgiveness for tens of millions of debtors — so much, the administration has permitted $25 billion in bank loan forgiveness for about 1.3 million borrowers.

Although some politicians and economists hailed the shift as a move in the appropriate course towards addressing the $1.7 trillion student debt disaster, hundreds of thousands of debtors have yet to see relief and are thinking when, and if, their financial loans will be forgiven. 

This is what to be expecting with pupil personal loan forgiveness in the coming months: 

The federal university student financial loan pause will probable be extended as a result of the end of 2022

White Residence officers are zeroing in on canceling $10,000 for all borrowers who gain significantly less than $150,000 for every calendar year, CNBC reports, but the administration has nonetheless to validate this kind of options. 

In April, the Department of Instruction extended the pause on university student mortgage repayment, curiosity and collections by way of Aug. 31, 2022, but Michelle Dimino, a senior schooling coverage chief at Third Way, predicts the payment pause will be prolonged still once more by the conclusion of the calendar year, at the very least till right after the midterm elections. 

A new poll from Knowledge for Progress and Rise identified that voters may well be considerably less very likely to vote in the midterms if the Biden administration fails to provide adequate relief to borrowers.

Cardona and other best Biden officials have also built it obvious that they are snug extending the pause throughout interviews. “We are going to proceed to monitor it,” Cardona advised Cox Media Group in April. “Appropriate now, we have August 31 and as you have seen in the past, we’ve been comfy moving that day if needed.”

Additional debtors could see reduction faster

In the meantime, however, Dimino expects that far more defrauded borrowers will see their debt canceled or reduced before long, primarily these with pending borrower protection statements or who qualify for a shut faculty bank loan discharge, which signifies your school closed even though you had been enrolled, or you couldn’t comprehensive your system simply because of the closure. 

“The a person point we can, and do, hope from this administration at this level is a continued, concerted effort and hard work to help debtors who are struggling the most and provide focused relief,” Dimino adds. “The Department of Education and learning is truly charging forward to get by that backlog of defrauded borrowers and give them the overdue reduction that they are entitled to.”

Verify out:

With scholar mortgage payments frozen right until Might, this is how to use that cash for a economic reset

If you despise budgeting, try the 80/20 rule to conserve funds without the need of monitoring every single one expense

Inspite of substantial-profile team cuts, the task market stays ‘burning hot’ for personnel

Indicator up now: Get smarter about your money and job with our weekly publication

NJ college graduate pays off $70K in student loans by starting used book business

NJ college graduate pays off $70K in student loans by starting used book business

NEWYou can now hear to Fox News articles!

When President Biden has floated the plan of canceling “some” pupil bank loan personal debt — an idea both equally GOP and Democrat lawmakers alike are alarmed by, declaring it would price tag the authorities as well a lot cash and incorporate to inflation — some college graduates with hefty debt financial loans aren’t waiting around for a person or a thing to bail them out. 

They are pushing ahead, carrying out what is actually appropriate — and figuring out a way to pay back off their have debt. 

And for 1 Rutgers University graduate, that concerned a novel concept. 

New Jersey native Pathik Oza graduated in 2018 with a B.A. from Rutgers College — he analyzed psychology and biology — with $70,000 in pupil financial loans, he told Fox Information Digital in an job interview.

OHIO Few, Moms and dads OF TWO, GET Large Scholar Mortgage Credit card debt Guiding THEM

And even though Oza began pursuing one more diploma ahead of his approach to go to health care school, he also identified a passion for rehoming made use of and discarded guides.

“I was strolling around one working day throughout the summer months, and I observed textbooks lying there, and I assumed there would be an option,” he said. 

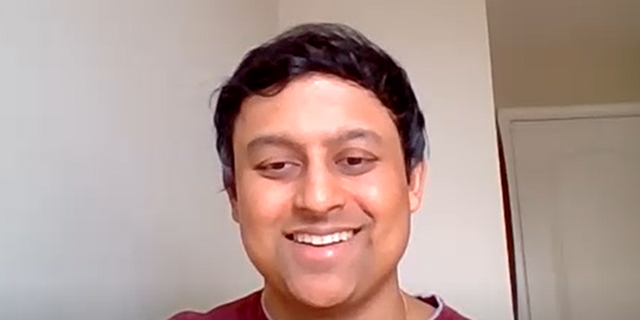
O3 Books founder Pathik Oza of North Brunswick, N.J., during a recent Zoom interview with Fox News Digital about paying down his student debt. "I just started this volunteer work where I would collect unwanted books," he said. 

O3 Textbooks founder Pathik Oza of North Brunswick, N.J., in the course of a new Zoom interview with Fox Information Electronic about having to pay down his scholar credit card debt. “I just started off this volunteer do the job where by I would acquire undesired guides,” he claimed. 
(Fox Information Electronic)

“Why would textbooks be thrown absent? They could be redistributed to someone who may well want them. So I just started off this volunteer perform exactly where I would gather undesired publications,” he told Fox Information Digital.

What commenced as a variety gesture and a prospect to give back to area libraries, schools, shelters and children’s hospitals turned into a sparkling new enterprise possibility. 

An expanding range of requests for publications and a significant need for his providers grew to become a little something significantly too substantial for just Oza and his Toyota RAV4 to deal with. 

Pathik Oza designed the selection to flip reselling books into a successful business enterprise.

So Oza built the decision to change reselling publications into a enterprise. He commenced off by opening an Amazon account. 

He termed his enterprise O3 Guides.

FLORIDA-Primarily based Mom PAYS OFF $40K IN Student Debt Immediately after Dwelling ‘PAYCHECK TO PAYCHECK’

“The gain would maintain coming in, and it stored rising,” he said. “[In about] a month or so, I experienced all around 1,000 to 2,000 textbooks in Amazon warehouses. So it was rather awesome to see the expansion in the organization.”

Oza ongoing to develop by launching a web page and opening an Etsy shop, which “blew up” when the planet was locked down for the duration of the coronavirus pandemic. 

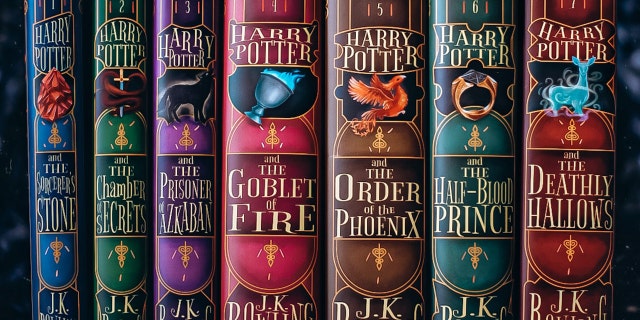
O3 Books' original dust jacket designs for J.K. Rowling's "Harry Potter" book series are shown here. (Pathik Oza/O3 Books)

O3 Books’ unique dust jacket models for J.K. Rowling’s “Harry Potter” book series are proven here. (Pathik Oza/O3 Guides)

He also identified that there was especially superior demand for his décor e-book sets and redesigned dust jackets he moved in that course to assistance spruce up the backgrounds of function-from-dwelling Zoom meetings.

By the end of 2020, Oza had created $115,000 from his facet enterprise — which lined his scholar financial loans in complete, and then some.

Oza figured out “a ton about finances,” he reported, by paying out off his loans and by fueling his very own smaller enterprise at the similar time.

Oza claimed he learned “a great deal about finances” by spending off his financial loans and by fueling his personal business at the similar time.

OHIO Author Paid out OFF $48K IN Scholar Financial loans IN 14 MONTHS: IT WAS ‘AN ADVENTURE’

Today, the 25-12 months-outdated stated he would truly feel “more cozy” getting on different sorts of borrowing in the potential centered on the economical know-how he’s accrued.

The achievements of O3 Books is now having to pay for Oza’s next diploma in total, doing away with the burden of needing to get out another personal loan. 

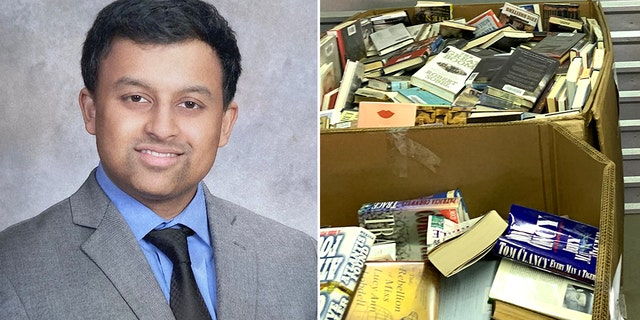
Pathik Oza of N.J. started O3 Books — and used the money he made from his new business to completely pay off his student loan debt. 

Pathik Oza of N.J. began O3 Guides — and utilised the funds he created from his new business to wholly shell out off his pupil personal loan credit card debt. 
(Pathik Oza)

The modest business enterprise proprietor has considering the fact that switched career paths. 

He is been pursuing a degree in personal computer science, though the assumed of hefty med school financial loans maybe in his long run gave him an further raise to consider treatment of debt he previously had.

“I felt it was urgent to pay people off,” he mentioned.

HOW TO Come to a decision WHICH Pupil Financial loans TO Fork out OFF Initial

For other pupils with personal debt who are seeking for a way to pay down their loans, Oza mentioned weighing the alternative of starting a little enterprise is a fantastic thought. He particularly encouraged using gain of on-line marketplaces like Amazon and Etsy.

“Any enthusiasm you’ve started off, there is undoubtedly a industry for it,” he said.

“You only will need a compact part [of the population] to [help] produce income in product sales. As extensive as you have 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the buyers, you have a whole-fledged business,” he included. “There is generally a market for anything.”

Expanding his own small business has supplied Oza a boost in terms of monetary literacy, so he also suggested that saving and investing one’s money is usually the “very best option.”

ROWE: Idea OF CANCELING Pupil Financial loan Personal debt ‘MAKES ME CRAZY’

“Make positive to understand finances and how you can greatest allocate your income,” he explained. “Loans are a stress no one would like — but you will get rid of them.”

O3 Books founder Pathik Oza shared ideas for other students with debt to pay down their loans. "Social media has opened up many opportunities to market your skills and allow you to create a side or potentially full-time income," he said.

O3 Textbooks founder Pathik Oza shared concepts for other pupils with debt to pay out down their loans. “Social media has opened up numerous prospects to industry your skills and make it possible for you to develop a side or possibly full-time revenue,” he mentioned.
(Pathik Oza)

Oza hopes one day to depart O3 Publications with his parents — as a continual outlet for supplemental money. In other terms, he desires it to keep in the family.

“This is an incredible side money I’ll keep endlessly,” he reported. “I built a model all over it. I developed a neighborhood close to it. So, it’s a little something I simply cannot allow go.”

“There is a market for your talent and there are numerous platforms you can use to showcase your skill.”

Oza also shared added tips for any individual needing excess earnings or cash to pay out down their scholar personal debt.

“I would suggest obtaining a section-time task — and if you do not have that much time, then use all those accessible several hours to make funds with a ability you have,” he mentioned. 

Click on Below TO Sign UP FOR OUR Lifestyle Publication 

“It could be nearly anything like advertising and marketing, art, world wide web design and style, application improvement or training … There is a industry for your expertise and there are a lot of platforms you can use to showcase your ability.”

“For example,” he added, “Instagram is an superb place for artists to showcase their artwork … The greatest section about this is you can operate when you are accessible.” 

Click on In this article TO GET THE FOX Information Application

Claimed Oza, “Social media has opened up quite a few possibilities to current market your expertise and allow you to create a facet or probably total-time revenue from a passion or talent you have. Once again, if your circumstance lets you to do this, consider to decrease your investing charges as substantially as achievable.”

Interest rates on new federal student loans going up for 2022-23

Interest rates on new federal student loans going up for 2022-23

Two years ago, federal pupil mortgage debtors appreciated the lowest desire costs at any time on their loans. This drop, prices for undergraduate debtors will be almost double what they were in 2020-21.

The fascination rates for new undergraduate immediate federal university student financial loans are established to raise to 4.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for the 2022-23 academic year, up from 3.73{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} previous yr and 2.75{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in 2020-21. The fascination prices on graduate direct loans are also set to boost to 6.54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} mum or dad and grad As well as loans will increase to 7.54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Due to the fact the new fascination premiums go into result beginning July 1, any new financial loans taken out ahead of then will have the desire premiums from the 2021-22 educational 12 months.

2021-22 interest fees

2022-23 desire prices

Undergraduate immediate mortgage

3.73{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

4.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Graduate direct bank loan

5.28{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

6.54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Plus mortgage

6.28{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

7.54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Growing rates make college or university far more pricey

Higher interest fees necessarily mean shelling out off loans will be more costly. For a dependent very first-year undergraduate student, a $5,500 personal loan — the maximum this scholar could borrow — will value $6,997 in excess of the conventional 10-calendar year repayment term with an desire fee of 4.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. At the 2020-21 amount of 2.75{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, this bank loan would price $6,297.

People getting on graduate immediate and Plus financial loans will see the cost of borrowing swell even far more. On top rated of larger fascination fees, As well as loans carry an origination charge of 4.23{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and don’t have any borrowing boundaries.

In accordance to the Hechinger Report, a nonprofit centered on instruction concerns, the typical As well as bank loan in 2019 was close to $14,000. That financial loan volume, taken on with the standard 10-12 months phrase and future year’s interest amount of 7.54{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, will expense $19,977 more than the life of the loan, like $5,977 in curiosity.

Interest charges for federal college student financial loans are set by the Treasury Department’s May possibly auction of 10-12 months notes. The fascination rate on the May 10-12 months notes, 2.94{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, is extra to margins set by Congress, and these margins differ concerning styles of federal student loans.

For undergraduate immediate financial loans, 2.05 share factors are additional to the curiosity amount graduate scholar financial loans have 3.6 factors added and 4.6 points for As well as financial loans.

Post the FAFSA and think about the payoff

Raises to the federal student personal loan fascination costs make it even far more important to consider the payoff of college and whether or not any personal debt you choose on is really worth it.

Nonetheless, even with enhanced interest premiums, federal college student loans are the very best option to finance your education if you require financial loans. Submit the No cost Application for Federal Student Support, or FAFSA, to be eligible for federal, condition and college-centered assist.

Submitting the FAFSA also lets you to be regarded as for grants and other support you really do not have to repay, these kinds of as the Pell Grant. When you’ve taken edge of any assist you really don’t have to repay, exhaust all of the federal scholar financial loans made available to you prior to opting for personal college student loans. Federal scholar loans offer you more borrower protections.

The payoff of attending college or university will change dependent on your major, the price of attendance and the total of debt that you have to consider on to finance your schooling. If the payoff isn’t obvious for you, take into consideration choices to school or beginning at a community faculty in advance of transferring to a four-year college to attain your bachelor’s degree.

Far more From NerdWallet

Colin Beresford writes for NerdWallet. E-mail: cberesford@nerdwallet.com.

The post Curiosity Premiums on New Federal Student Financial loans Going Up for 2022-23 initially appeared on NerdWallet.

Will Biden Cancel Student Loans? Here’s What the Public Wants.

Will Biden Cancel Student Loans? Here’s What the Public Wants.

Text measurement

Former minister accuses Starling Bank over Covid loans | Banking

Former minister accuses Starling Bank over Covid loans | Banking

Previous Tory minister Theodore Agnew has introduced a community assault on Starling Lender, dragging the on-line financial institution into the Covid loans scandal by declaring it did not run ample checks on debtors right before handing out taxpayer-backed financial loans.

Through the pandemic, the United kingdom governing administration relied on higher street and on line financial institutions to hand out £47bn to compact enterprises under the bounce again bank loan scheme, which supplied up to £50,000 a company. The Treasury promised to include 100{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the losses if borrowers failed to repay. In the rush to distribute cash, critics say nominal checks ended up designed to reduce fraud and the value to the taxpayer could be as a lot as £5bn.

Lord Agnew, who quit as the anti-fraud minister in January above the government’s “woeful” attempts to manage fraud, spoke publicly on Wednesday night to say banks must be “very careful” right before tapping the govt promise.

Nevertheless, he singled out Starling Lender and accused the loan company of utilizing the scheme for its very own gain. “With negligible facts, I are not able to analyse the complete extent of the misdemeanours, but I’d like to get in touch with out a single of these banks that I imagine has acted against the government’s and taxpayer’s pursuits: this is Starling Lender,” he told visitors at an anti-fraud event in Westminster.

Starling Bank’s main executive and founder, Anne Boden, reported she was “shocked” by Agnew’s responses, and has questioned the former minister to withdraw his statements. Boden explained Starling had been open up and transparent about its technique to bounce-again loans and was one of the “most active and helpful banking companies battling fraud”.

Agnew pointed to a substantial rise in the bank’s lending balances considering that the plan went dwell. Back in November 2019, ahead of the pandemic, Starling experienced only lent £23m , excluding financial loans purchased from other organizations. By June 2021, according to a organization buying and selling update, it had distributed £1.6bn worth of bounce-back again loans.

The lender disbursed a even further £640m less than the larger sized coronavirus enterprise interruption loan scheme, which provided up to £5m a borrower.

The former Tory minister, who has pushed for greater transparency all around the scheme, stated from “what very little data” he was capable to get although in authorities, Starling “were a single of the worst when it came to validating the turnover of companies or distributing suspicious exercise reports”.

“It seems to me that they took this as a God-despatched prospect to swell their harmony sheet by a aspect of 50 times in hardly considerably less than a calendar year, with no danger to on their own and 100{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} possibility to the taxpayer,” Agnew stated. He claimed that it was a “cost-free of charge marketing training to establish their financial loan guide and so their corporation valuation”.

Boden said on Thursday that the lender experienced released more checks including for sole traders, and experienced excluded all non-active businesses, and those that had been included after 1 March 2020 – the reduce-off point for accessing the Covid loans – from the scheme.

“The comments elevated by Lord Agnew about not examining the turnover of corporations or submitting suspicious action stories are totally and totally mistaken and I have to question him to withdraw the assertion,” stated Boden.

Though Starling’s bounce-back personal loan fraud price was bigger than other banking companies, at 3.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of cash lent, this was only owing to the point that Starling had been “better and quicker” at determining fraud than its friends. “On duplicate loans, for instance we uploaded lending facts inside days. Some other financial institutions took months,” she stated.

“I concur with Lord Agnew that we need to safeguard taxpayer’s dollars,” Boden included. But “directing his anger at Starling is just improper – we were being the bank that was singled out for criticism by Treasury officials, ministers and MPs, for rejecting so quite a few possible fraudsters”.

Indicator up to the everyday Business Today e-mail or adhere to Guardian Business on Twitter at @BusinessDesk

The bounce-back again bank loan programme, which was introduced by the Treasury and overseen by the British Business enterprise Lender, scrapped added credit rating checks and allowed debtors to self-certify their earnings in order to ensure money was distributed to businesses promptly at the height of the pandemic. Whilst big banking institutions including NatWest and HSBC restricted bounce-back again loans to existing prospects as a end result, smaller banks these kinds of as Starling have been regarded a lifeline for sole traders that did not have accounts with big banking institutions.

“We could not go away our tiny enterprise shoppers without access to these loans,” Boden explained.

Bounce-back again loans ended up being the largest scheme in the Covid mortgage programme, distributing a full of £47bn to 1.6 million recipients.

Agnew explained before this calendar year that 87{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the bounce-back again loans that ended up paid out to previously dissolved businesses – regarded as a variety of fraud – came from just 3 loan companies, and that two banking institutions were liable for 81{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of circumstances exactly where loans were being granted to firms incorporated just after the pandemic strike. He did not divulge the names of the banking companies in concern.

Bolt Financial’s loans come due

Bolt Financial’s loans come due

One particular-click on checkout enterprise Bolt Economical yesterday laid off 1-3rd of its workforce, just months immediately after increasing $355 million in VC funding at nearly an $11 billion valuation.

Why it issues: For some, the financial ramifications go perfectly beyond the loss of potential wage.

  • In February, we discussed how Bolt provided loans to workers who wanted to acquire vested shares.
  • We also famous that when the goal was laudable, in that it could help personnel decreased upcoming tax expenses, the personal loan framework could also put employees in hock to their employer. And that unbalanced trade-off was also hazardous (no make any difference how much “schooling” was furnished).

Now we know a lot more:

  • Bolt’s loans ended up 51{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} recourse, which indicates they are collateralized by employee’s personal property, whilst 49{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} were being secured by the shares. Any loans tied to masking taxes were 100{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} recourse.
  • Moreover, if an staff stops operating at Bolt — for any rationale — the mortgage should be repaid in 90 times. Visualize possessing your manager hand you a pink slip and then attain into your pocket, since that is just what is actually taking place to some folks who worked at Bolt.

A Bolt spokesperson says that only a “solitary digit” number of laid-off workers took out the financial loans, irrespective of a lot more than 200 persons losing their jobs, and that the aggregate sum was underneath $200,000. What’s more, she says the corporation programs to “get the job done with” those people people.

  • Certainly, it truly is welcome information that the gap isn’t deeper. Significantly considering the fact that Bolt founder and then-CEO Ryan Breslow the moment tweeted that in excess of 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of eligible staff members took out loans. It’s possible the layoffs ended up primarily of newer, unvested staff members. Breslow, for what it truly is truly worth, has absent radio silent on me considering the fact that yesterday afternoon.
  • But some remaining workers will have to be freaking out, specifically offered that Bolt is all of a sudden scaling way back again, is being sued by a top lover and is an e-commerce enabler heading into what could be a economic downturn. There is some solace that the financial loans aren’t now underwater presented the delta between 409a valuations and venture valuations, nor is Bolt charging desire, but it truly is a demanding time for optimism.
  • The exceptions may be workers who, rather than getting out a mortgage, took benefit of a distinctive Bolt give to lengthen their work out period of time (the size of which was dependent on tenure).

There also was some social media discuss yesterday that a independent business tied to Breslow provided the loans, but Bolt’s spokesperson claims that’s untrue (which can make perception, due to the fact these have been cashless transactions).

She adds that Nasdaq Non-public Market managed the course of action. NPM to begin with declined comment, but sent a assertion subsequent to this story’s preliminary publication: “Nasdaq Private Industry delivers both of those technologies methods and market trading solutions for private firm fairness. Providers leverage NPM’s engineering for a variety of bespoke remedies, together with possibility extensions and agreement administration workflows. Currently NPM does not offer loans or any lending expert services.”

The major image: This tale is about Bolt, but a startup attorney tells me that it’s hardly the only startup supplying out these recourse financial loans. Furthermore, some of them now are even coming with “forfeiture clauses” for financial loans tied to early physical exercise of unvested shares, whereby the firm doesn’t repay at cost if the personnel leaves (Bolt did not have a forfeiture clause).

The bottom line: Many dotcom-era vets warned modern business people that these loans were a poor strategy, notably offered that the unicorn herd was just about specific to be thinned. They have been appropriate.