Pressures aligning on Biden, Democrats to forgive student loans

Advocates and lawmakers are stepping up the pressure on President BidenJoe BidenMcConnell: Rounds ‘told the truth’ about 2020 election Abrams thanks Biden for Ga speech, backs connect with for Senate regulations transform Overnight Wellbeing Treatment — Biden officials just take heat at Senate listening to Far more to act on scholar bank loan forgiveness, concentrating on it as a major problem some alert Democrats could pay back for at the ballot box in the upcoming midterm elections.

Biden has been named on to do the job with Congress on the problem and offer a lot more transparency about his authority to wipe out all federal scholar financial debt for hundreds of thousands of Americans. The extension as soon as yet again of the pupil personal loan reimbursement pause amid record spikes in COVID-19 situations produced advocates optimistic that extra motion will occur out of the White Residence. 

“I consider the administration needs to interact much more with Congress on this simply because I think there’s real worry,” Sen. Bob CaseyRobert (Bob) Patrick CaseySenate Democrats mature considerably less self-confident in Manchin Senate Democrats push for details on nursing home boosters Senators urging federal investigation into Liberty University’s dealing with of sexual assault statements Far more (D-Pa.) explained to The Hill.

Wide-based mostly college student loan forgiveness has acquired help amid Democratic leaders like Senate Vast majority Leader Charles SchumerChuck SchumerClyburn on updating election legislation: ‘What is genuine right now was not legitimate then’ Biden eulogizes Reid as a fighter ‘for the The usa we all love’ Like it or not, all roadways ahead for Democrats go via Joe Manchin More (D-N.Y.), who are on the lookout to Biden for assist on the issue as the bash prepares for a significant election year.

“Pressure is mounting from all fronts. It is mounting from grassroots, it’s mounting from the community, and it’s mounting from users of Congress. And the actuality of the economic system, the midterms, there are a number of pressures that are aligning. They definitely have to produce,” explained Thomas Gokey, an organizer with the Debt Collective.

Federal university student mortgage payments were initially paused less than a moratorium enacted less than then-President TrumpDonald TrumpMcConnell: Rounds ‘told the truth’ about 2020 election Abrams thanks Biden for Georgia speech, backs call for Senate policies improve Kerik to sit for ‘voluntary interview’ with Jan. 6 panel, attorney suggests A lot more in March 2020. The freeze has been prolonged various periods since under each the Trump and Biden administrations.

Biden previous prolonged the maintain final thirty day period amid a mountain of force from progressives and borrowers to forgo the previously established Jan. 31 date to lift the forbearance on university student loans. At the time, Biden prolonged the momentary pause on federal student financial loans and interest accrual as a result of the begin of Might.

A White Household spokesperson instructed The Hill that the extension was a recognition “that whilst our work restoration is 1 of the strongest at any time, tens of millions of college student financial loan debtors are nevertheless coping with the impacts of the pandemic and want some far more time in advance of resuming payments.” 

The extension marked a shorter-time period victory for advocates who experienced been urging Biden to lengthen the pandemic moratorium, when pointing to the surge in coronavirus cases fueled by the distribute of the very contagious omicron variant. 

But the action did minor to quell the quite a few phone calls by progressives who have urged the president for months to go more and use his government electrical power to unilaterally terminate college student mortgage credit card debt.

“If he has the authority to pause college student personal loan payments, he has the authority to cancel, and he ran on canceling at least $10,000,”  Rep. Jamaal Bowman (D-N.Y.) told The Hill. “We’re pushing him to completely cancel it, and that is what we hope he decides to do.”

Natalia Abrams, president and founder of the Scholar Personal debt Crisis Middle, warned of the political implications of Biden resuming bank loan payments in an election calendar year.

“It’s absolutely been this odd center ground by extending this pause. If he carries on to extend the payment pause until they’re completely ready to cancel the pupil financial debt, we’ll be Ok. Somewhat than turning payments on in a midterm calendar year when debtors are not all set,” she mentioned.

Throughout his 2020 presidential operate, Biden campaigned on forgiving at minimum $10,000 in federal university student financial loans per person.

The Personal debt Collective warned that if Biden doesn’t forgive up to $50,000 in federally held scholar financial debt for every borrower, which progressives have termed for, he will eliminate voters, citing discussions with debtors on a grassroots amount.

“This is not just the midterms, this is about the relaxation of their life,” Gokey mentioned. “A Democrat could not be elected dog catcher if they flip pupil personal loan payments again on.”

But as prime Democrats go on to simply call on Biden to go bigger or wipe out college student mortgage financial debt totally, disagreements have also bubbled up around irrespective of whether the president has the electric power to do just that by govt motion.

Lawmakers and advocates have been waiting months to see a memo that Biden asked for from the Office of Training in April to establish his authority to cancel pupil personal debt.

“I really do not know why it would be held onto this long,” stated Abrams. “No matter what aspect of the aisle you’re on, we all really should see that in terms of transparency and that way borrowers and lawmakers can move on correctly.”

When questioned if the Instruction Section is performed with the memo asked for by the president, a spokesperson for the agency mentioned it is working with the White Property to “review choices with respect to personal debt cancellation.”

“It’s intriguing to me that they are not even acknowledging that they have the memo, that they’ve been sitting down on it,” Gokey mentioned, including that he thinks the president has the authority to forgive college student loans.

The White Home, when requested for remark on the memo, pointed to steps the administration has taken, like offering almost $13 billion in qualified mortgage reduction to much more than 640,000 borrowers and supplying $5.8 billion for permanently disabled borrowers. 

A spokesperson mentioned the White Property will “put forth regulatory enhancements to earnings-driven repayment, borrower protection to compensation, and shut college discharges” in the coming months and months.

But additional than 8 months considering that the memo was asked for by the White Household, persistence has been putting on thin among the several borrowers ahead of the impending Might deadline, incorporating to issue amongst lawmakers. 

“I do think they want to make confident that they’re crossing all the T’s and dotting all the I’s for the reason that they know you will find gonna be a great deal of political pushback on it … I get their apprehension, but they will need to shift at some level when they get a clear resolve,” Rep. Ruben GallegoRuben GallegoOvernight Protection & Countrywide Security — Nation marks 1 12 months since Capitol riot Hispanic Democrats slam Republicans in Jan. 6 marketing campaign ad Gallego rips ‘feckless’ Garland about Jan. 6 response Far more (D-Ariz.) explained to The Hill.

Sen. Raphael WarnockRaphael WarnockRepublicans threaten flooring takeover if Democrats weaken filibuster  Juan Williams: American democracy will die except voting legal rights are shielded Democrats skeptical of McConnell’s offer to speak on election legislation Far more (D-Ga.) echoed calls by advocates who have pushed for popular student financial debt forgiveness as a way to assistance “address the racial prosperity gap,” as details has proven debtors of colour, in particular Black and Hispanic graduates, carry a disproportionate load. 

“If we ended up equipped to get some student personal debt forgiveness offer, I consider it would go a extended way,” he said. “I imagine it would be a huge elevate on the private economies of these debtors, but it would be a great lift to the economy.”

Research unveiled by the Brookings Institution in 2016 confirmed that Black and Hispanic graduates owe more on normal than white graduates, and are much more probable to default in the four several years following graduation. 

A May perhaps 2021 analysis from The American Affiliation of College Women also found that Black women owed roughly 20 per cent additional pupil debt than white women of all ages, carrying a bigger considerable personal debt stress than other gals of colour borrowers.

Last year, a Coloration of Improve poll launched in February located that 84 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Black voters, a voting bloc that was vital to encouraging Biden gain the election in 2020, help entire or partial personal debt cancellation. The poll also discovered that 40 per cent of Black voters broadly mentioned they would not back again a applicant that does not assist doing away with college student credit card debt.

Other polls have also indicated acceptance surrounding the drive for some type of scholar personal debt forgiveness has grown. A modern poll unveiled by the Morning Consult with/Politico in December identified over 60 percent of voters surveyed assistance pupil debt forgiveness.

Schumer escalates pressure on Biden to cancel student loans in 2022

The Senate bulk leader has called on the Biden administration to terminate scholar financial loans in a collection of Twitter posts in excess of the earlier many months. Although some borrowers have certified for a financial loan discharge by the PSLF program, most debtors haven’ (iStock)

To kick off the new yr, Senate Greater part Leader Chuck Schumer explained he thinks it is “a great working day” for the Biden administration to cancel university student personal debt — one thing he also stated about 20 periods on Twitter in December by yourself.

This is WHO HAS Competent FOR Student Bank loan FORGIVENESS Beneath BIDEN

For the earlier numerous months, Schumer has been ramping up strain on President Joe Biden to forgive up to $50,000 worthy of of federal university student mortgage financial debt making use of govt action. Although Biden advocated for broad student financial debt cancellation as a presidential applicant, he has not delivered on his campaign assure because taking business. 

Though Schumer and a number of other outspoken progressives have been advocating for Biden to lean on his govt authority to forgive student loans, the White Residence lately stated that the president is waiting around on Congress to produce on college student forgiveness laws. 

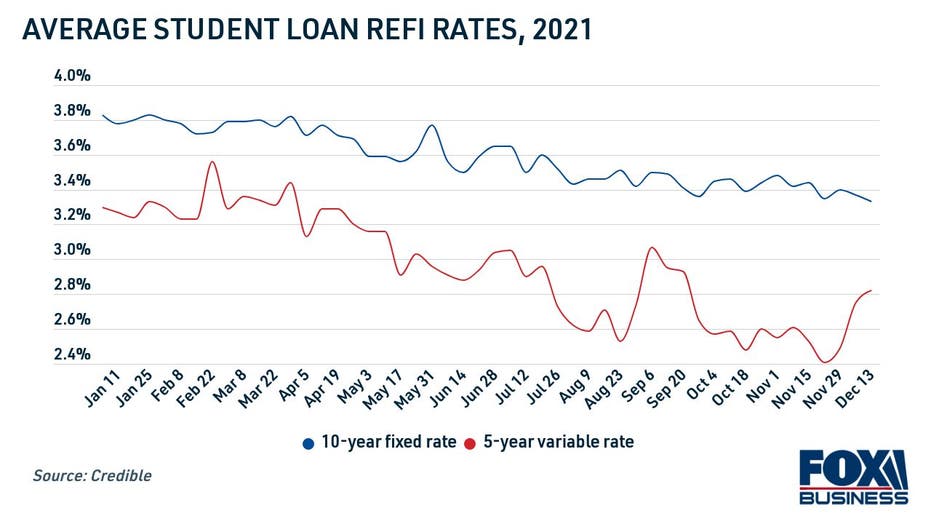
Keep reading through to find out a lot more about the likelihood of widespread pupil financial loan forgiveness, as effectively as your alternate loan compensation choices like refinancing. You can see your estimated student loan refi prices on Credible for free of charge with no impacting your credit rating rating.

Community Assistance Personal loan FORGIVENESS System JUST Got Less difficult FOR 550,000 Borrowers

Can Biden forgive scholar loans with an govt purchase?

In accordance to the Higher Training Act of 1965, the Secretary of Training has the legal authority to “implement, pay out, compromise, waive, or release any right” to accumulate on federal financial loans, but it truly is unclear no matter if that includes common personal debt forgiveness.

While Schumer and other popular lawmakers like Rep. Alexandria Ocasio-Cortez and Sen. Elizabeth Warren have urged Biden to terminate student bank loan personal debt, not all Democrats are in settlement that the president can do so. 

Biden himself has solid doubt on his electric power to terminate university student loans — White Dwelling push secretary Jen Psaki not long ago instructed reporters that the president was waiting around on a monthly bill from Congress. She also added that Biden’s presidential authority to terminate college student financial loans was “beneath review.” Residence Speaker Nancy Pelosi has also beforehand claimed that the president does not have the authority to forgive university student loans, incorporating that it “has to be an act of Congress.” 

Passing college student mortgage forgiveness legislation via a divided Congress would be a tough task. Democrats maintain a narrow 50-50 vast majority in the Senate, which suggests they would want the support of moderates like Sens. Joe Manchin and Kyrsten Sinema in order to cancel pupil personal debt. 

Plus, federal college student personal loan forgiveness wouldn’t apply to private university student financial loans, which make up 8.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of all scholar financial loan personal debt, according to the Training Details Initiative. Personal college student loan debtors could alternatively take into consideration refinancing on Credible even though prices are at file lows. 

SCHUMER Phone calls ON BIDEN TO Extend University student Personal loan PAYMENT PAUSE AMID OMICRON VARIANT

3 approaches to deal with your student bank loan personal debt

About 43.2 million People in america have scholar bank loan personal debt, with an average harmony of $39,351, in accordance to the Education Data Initiative. If you are battling to control your scholar loans, contemplate the pursuing alternate financial debt repayment choices:

  1. Profits-driven compensation ideas. Enrolling in earnings-driven compensation (IDR) will restrict your federal university student financial loan payments to 10-20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of your discretionary revenue, relying on the sort of financial loans you have. You can get started off on the Federal Pupil Aid (FSA) web-site.
  2. Further federal forbearance. Federal pupil loans are at present in administrative forbearance till May 2022, but debtors could be eligible for up to 36 extra months of college student loan reduction via economic hardship or unemployment deferment.
  3. Student loan refinancing. It may well be possible to reduce your month-to-month pupil personal loan payments by refinancing to a decreased charge as a result of a private financial institution. Set college student bank loan refinance prices are now at document lows, producing it a superior time to lock in far better conditions.

BIDEN’S Training Section HAS CANCELED $1.5B IN Scholar Loans By means of BORROWER Defense

Be informed that refinancing federal scholar financial loans into a personal bank loan will make you ineligible for govt rewards, including the present-day federal pupil loan payment pause, IDR ideas and pick out college student financial loan forgiveness plans.

If you you should not prepare on having benefit of these federal advantages — or if you happen to be a person of the millions of debtors with non-public pupil personal loan personal debt — then scholar mortgage refinancing may possibly enable you pay back off debt speedier, reduced your month-to-month payments and help save money on fascination about time. Look through present-day pupil bank loan charges in the table underneath, and visit Credible to see delivers customized to you. 

47K VETERANS AND Lively-Responsibility Assistance Customers Mechanically Get College student Personal loan Reduction

Have a finance-similar concern, but don’t know who to request? Electronic mail The Credible Dollars Qualified at moneyexpert@credible.com and your dilemma may well be answered by Credible in our Revenue Skilled column.

The end of student loans

When it will come to scholar loans, President BidenJoe BidenPelosi on eve of Jan. 6: Capitol rioters ‘lost’ bid to halt tranquil transfer of energy MyPillow CEO Mike Lindell sues Jan. 6 panel above subpoena for mobile phone documents Overnight Protection & National Stability — Nation marks 1 12 months because Capitol riot Extra is acting like Lucy removing the soccer just as naïve Charlie Brown is persuaded to kick it. Every single time the president sets a new day to resume college student payments, he takes it away. Student debtors speculate when payments will begin all over again and if they do, the place they will find the funds they prolonged considering the fact that used.

Delaying payments is not a coverage it is the absence of a policy. But it does make practically specific that pupil loans will go unpaid. A mortgage with out self-control, with out enforced regulations, is just silly. The college student personal loan plan usually was. It was lending to 17-calendar year-old young children without the need of any credit score checks based mostly on a hope and a prayer that the young children would locate a way to repay it in the future devoid of possessing any plan what principal and desire, tenors and defaults definitely suggest.

Now, the administration desires to salvage what it can. Just like it experienced to retreat to the airport in Kabul, it has to acknowledge personal loan forgiveness. Let us not ignore, he campaigned on forgiving “a minimal of $10,000/man or woman of federal scholar loans.”

If the administration doesn’t acknowledge this reality, it may go through prevalent defaults on the new reimbursement day on Might 1. Of course, it could ramp up enforcement by its debt collectors. But wherever will it place all the automobiles they seize from the delinquent pupil debtors? 

Meanwhile, Vice President Harris is contacting for new thoughts all around college student financial loans, for thinking out of the box. When she was jogging for president, Harris advised bank loan forgiveness for people borrowers who begun corporations in deprived places. Its emphasis on entrepreneurship was commendable but it was rarely a thorough resolution. It experienced some similarities to the system of general public provider forgiveness wherever men and women pick out occupations not on their drive or skill but as a usually means to stay clear of credit card debt. These prescriptions test to relieve pupils out of a problem they never ought to have had in the initial put and put them in a different if they really don’t like remaining a instructor or authorities attorney.

But the vice president is right about contemplating out of the box. The fantastic news is that it is possible to clear away the stress on pupils and conserve the larger-schooling system. For instance, how about no for a longer time charging college students desire but rather investing their principal payments to receive the return. Or why not have companies match the college student financial debt payments of their personnel like they do for social protection payroll deductions. Following all, they immediately advantage from what the pupils master in college or university. And let’s have the federal government begin treating people like adults by sending them the funds their youngsters borrow fairly than skipping in excess of them to send it to the colleges like they do now. If the college students and households are mature enough to repay the financial debt, aren’t they experienced ample to receive the dollars in the initial area? If the govt set the money into tax-advantaged 529 accounts, it could also really encourage persons to save. With a part of this revenue people could even employ the service of counsel to negotiate tuition with faculties. Just as unions combat for greater wages, families could battle to decrease university charges.

These days, all of these commonsensical strategies lie scattered outside the house the box. But none of them are new. Like Lego pieces, they could develop into building blocks to make a shiny new way to finance higher education.

Robert Hildreth is a former International Financial Fund economist whose experienced get the job done involved restructuring South American credit card debt and advertising sovereign debt loans. He launched the Hildreth Institute focused to restoring the assure of bigger education.

The CFPB’s Arbitrary Attacks on Payday Loans

The new director of the Consumer Monetary Safety Bureau,

Rohit Chopra,

has began rattling his interventionist saber only two months after his Senate affirmation. From pushing the Federal Deposit Insurance policy Corp. to block financial institution mergers to attacking lender overdraft fees, Mr. Chopra is transferring aggressively. If the CFPB’s inquiries into “Buy Now Pay Later” credit score and pawn loans are a leading indicator, it looks only a issue of time right before Mr. Chopra revisits the perpetual progressive irritant—payday financial loans.

A review we a short while ago finished thoughts the knowledge and legality of the CFPB’s last try to regulate payday financial loans, a rule from 2017. This rule supplies the template for efforts to regulate payday financial loans out of existence. That huge rule confined payday-bank loan buyers to no additional than 6 loans a calendar year unless they could meet up with a rigid governing administration-mandated means-to-repay standard.

Our effects present that the CFPB’s tactic to payday financial loan regulation is unwell-conceived and wants adjustment. We identified that the CFPB’s emphasis on the allowable range of payday financial loans is not a realistic consumer defense plan.

We examined details from 2013 on 15.6 million payday financial loans, designed to 1.8 million unique borrowers, to establish whether the range of loans a purchaser takes in a 12 months is a meaningful evaluation of client welfare. We examined payday-loan terms and use and approximated the results on people if they ended up prohibited from taking much more than six financial loans in a calendar year. We targeted on the conversation of this limitation with two typical means states control payday financial loans: restrictions on allowable loan fees and on loan quantities.

Our results will startle the rule writers at the CFPB. Opposite to the investigation cited in the CFPB’s 2017 rule, which claimed that “loans are almost generally manufactured at the highest fee permitted,” we observed that neither charges compensated nor personal loan quantities inexorably rose to utmost allowable degrees when all those allowable ranges were fair.

We located that two or else similar people in unique states could choose out a distinctive amount of financial loans to purchase the sum of credit rating they will need, just due to the fact point out laws vary as to the amount a shopper can legally borrow on 1 financial loan. If a customer in a condition with a $500 financial loan amount of money cap wants $600, the borrower will have to take out two loans. With no a cap, just one loan would do.

We uncovered that borrowers in states with minimal permitted bank loan quantities ($500 or a lot less) acquire out about 50{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} a lot more loans than debtors in states with significant permitted bank loan amounts (extra than $500 or no personal loan quantity cap). In reduced-amount of money states, debtors took out an ordinary of 9.31 financial loans. In significant-amount states, debtors took out an regular of 6.27 loans.

Additionally, inspite of the stricter borrowing limits on mortgage amounts at any given time, debtors in reduced-amount of money states ended up borrowing the exact complete sum in the course of the yr as people in superior-sum states. In the end, people in lower-sum states experienced to consider out far more financial loans to meet their requires. Total, our study reveals the arbitrary mother nature of the CFPB’s obsession with the quantity of financial loans as a handy measure of client welfare.

The CFPB’s concern in 2017 was borrowers who continuously “roll over” their loans. A rollover occurs when a buyer borrows, say, $500 with a assure to repay the complete volume in two weeks. In two months, however, if the borrower does not repay the financial loan in comprehensive, the loan can be “rolled about,” simply by paying out the price (commonly about $19 to $21 per $100). The rigid capacity-to-repay typical and six payday loans per yr look, to us at least, to stem from rollovers by payday borrowers. Rollovers signify a significant selection of loans but are designed by a minority of debtors.

Luckily, cooler heads prevailed, and in 2020 the CFPB underneath Director

Kathleen Kraninger

rolled back again the skill-to-repay provision in the 2017 rule. The CFPB estimates that had the rule absent into outcome totally, it would have eliminated 59{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 80{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of all payday financial loans.

Sad to say, the intense scrutiny of little-dollar financial loans is back on the CFPB’s enforcement menu. But our investigation is abundantly obvious: The CFPB really should stop its efforts to impose one particular-measurement-fits-all regulation on payday financial loans. People are considerably much better at handling their funds than Washington bureaucrats believe that.

Mr. Miller is a professor of finance at Mississippi State University and a senior investigate fellow at Consumers’ Exploration. Mr. Zywicki is a professor at George Mason University’s Antonin Scalia Legislation University and a exploration fellow at the Law and Economics Heart.

Journal Editorial Report: Kyle Peterson, Mary O’Grady, Dan Henninger and Paul Gigot foresee what is actually coming in 2022. Photos: AFP/Getty Pictures Composite: Mark Kelly

Copyright ©2021 Dow Jones & Enterprise, Inc. All Legal rights Reserved. 87990cbe856818d5eddac44c7b1cdeb8

‘Buy Now, Pay Later’ Loans May Soon Play Bigger Role in Credit Scores

Francis Creighton, the president and chief government of the Shopper Info Business Association, a trade group for the credit history reporting industry, explained it was important to have pay-later on loans reflected on credit rating studies so loan companies could have a legitimate photograph of a bank loan applicant’s overall credit score profile. But simply because the loans are structured in different ways from classic loans, he explained, the credit bureaus initial had to solve “technical” difficulties to add them. “We have to make positive we do it suitable,” he said.

At the exact time, the federal Purchaser Economical Safety Bureau has stepped up scrutiny of pay out-later companies. In mid-December, the bureau opened an inquiry, asking 5 corporations to supply information about their enterprise methods by March 1. The bureau, citing the “explosive growth” of shell out-later through the pandemic and through the holiday buying year, claimed it desired to fully grasp the possible gains and threats to customers improved. The agency mentioned it was also involved about how the firms use the knowledge they acquire from consumers.

The company pointed out that if customers use the loans for numerous purchases, they could have difficulties retaining keep track of of payments. “Because of the simplicity of acquiring these loans,” the agency mentioned, “consumers can close up investing much more than expected.”

Installment payments are ordinarily deducted automatically from debit playing cards, so shoppers may well be charged overdraft costs if they do not have plenty of money in their accounts to address the payments. If customers spend the installments with a credit history card, they may possibly operate up further debt and desire expenses on their card if they never spend their installment equilibrium in total.

Also, the consumer company explained, spend-later financial loans carry fewer protections than standard credit score cards, like the correct to dispute a charge if a product or service is faulty.

Associates of Congress, as perfectly as customer groups, have called for a lot more oversight of the organizations, noting that because the installment financial loans do not use traditional credit history checks, it is not crystal clear whether debtors have the skill to repay many loans.

Below are some inquiries and answers about invest in now, fork out afterwards credit rating:

Ms. Saunders stated buyers really should be confident that they will be in a position to make the essential installments in the time allotted. With standard credit history playing cards, clients have a regular payment agenda and a assertion summarizing all rates, but anyone with numerous pay back-later financial loans may possibly have to juggle a number of owing dates. “They unquestionably want to make guaranteed they are trying to keep monitor of their payments,” she mentioned.

If Your Student Loans Were Forgiven, Here’s What You Should Do Next

Kameleon007 / iStock.com

Kameleon007 / iStock.com

Beneath President Joe Biden, additional than 638,000 borrowers have experienced their scholar mortgage debt forgiven or are in the process of getting their student financial loans forgiven, NPR noted. If you drop into this class, you may perhaps now have some much more wiggle area in your funds — so what ought to you do with these excess resources? I spoke to money professionals to get their very best tips.

Save Additional: Unplug These Appliances That Hike Up Your Energy Bill
Read through Additional: 40 Funds Behaviors That Can Depart You Broke

Deal with All Needed Fees

“To prioritize all those extra resources, seem at necessities, this sort of as housing, groceries, transportation and instruction,” explained Stacey MacPhetres, university student financial loan qualified and senior director of education and learning finance at EdAssist Alternatives. “Recognize how extra dollars in your pocket can much better oneself and your household.”

See: Motives You are Still Living Paycheck to Paycheck

Spend Down Other Debts

If you have credit rating card credit card debt or other non-mortgage loan personal debt, aim on having to pay this down with the money you had previously been placing toward university student personal loan payments.

“For individuals whose personal harmony is skewed towards liabilities, we would advocate continuing to pay down credit card debt and suitable-size their own accounts with the new financial debt forgiveness,” said Adam Inexperienced, co-founder and CEO of Yeildx.

Focus on paying out down superior-interest financial debt to start with, reported Katie Ross, government vice president at American Consumer Credit Counseling.

“For people who now have extra wiggle home in their spending plan, it could be a good concept to deal with substantial-fascination credit score card credit card debt, in particular for those who went over-price range with holiday getaway buying and will be receiving their credit score card expenditures that may perhaps be even bigger than predicted,” she mentioned. “The ordinary credit history card fascination rate is just about 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, so for individuals who really do not fork out their bill in whole each and every thirty day period, that personal debt can include up speedily.”

Go through: 19 Successful Techniques To Deal with Your Price range

Even if you don’t have vacation buying debt, you may possibly nevertheless be carrying in excess of debt from a complicated couple of years.

“Recent info from Tally, the credit card debt payoff app, found that additional than 50 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of individuals with credit score card credit card debt improved that credit card debt all through the pandemic,” claimed Bobbi Rebell, CFP and own finance professional at Tally. “Any aid in scholar debt is an option to consider handle of credit score card credit card debt if that is you.”

As for which credit card to shell out off very first, “start with your optimum curiosity price to your cheapest interest rate,” mentioned John Rampton, founder of Due.

Having to pay down financial debt can support you prevent a monetary disaster and give you additional money adaptability, claimed Julie Rains, author and publisher at Investing to Prosper.

“The much less obligations you have with your funds and the more cash you have, the a lot more you can stay away from issues — like not owning enough cash or credit score to pay for an unexpected medical expenditure or huge car repair invoice — and just take benefit of chances, these kinds of as placing down a deposit on a new apartment so you can acknowledge a new work in a new city,” she stated.

“More specially, if you have received substantial-fascination credit-card financial debt, loans with a smaller stability and college student financial loans with fascination forbearance, it tends to make perception to prioritize personal debt payments and accelerate these payoffs,” Rains continued. “Then, immediately after your debt has been eradicated, you are going to have money offered for preserving and investing.”

Discover: Discounts Methods From Standard Men and women Who Are Sitting on Millions

Make Up an Crisis Fund

Once you have paid down non-house loan debt, your following priority need to be your crisis cost savings, mentioned Barbara Friedberg, investment decision qualified and owner of Robo-advisor Execs and Barbara Friedberg Particular Finance.

“Set up an unexpected emergency fund equal to 6 months of residing bills,” she claimed. “COVID should really remind you of why this is critical!”

Owning six months of fees saved in an emergency fund “does two issues,” said Derek Sall, owner and blogger at Lifetime And My Funds. “It presents you stability when an crisis comes up, and it will retain you from producing dumb decisions on any presented day because you really do not ever have any revenue.”

If six months look far too lofty of a objective, commence with $1,000.

“Save it as quick as you can,” stated George Kamel, a Ramsey persona. “This will aid you if a little something unexpected arrives up.”

Discover: The 8-Step Plan To Obtaining Fiscal Liberty

Save for Retirement

If you have paid out down debts and have a adequate crisis fund, prioritize conserving for the prolonged time period.

“Allocate additional towards your ‘endgame,’” reported Nicole Lapin, money expert and author of “Miss Impartial: A Very simple 12-Action Prepare to Start out Investing and Increase Your Very own Prosperity.” “The endgame is exactly where you squirrel money into what your potential self will thank you for like cost savings, investments and retirement.”

“Fund your office 401(k) or 403(b) with as considerably dollars as you can,” Friedberg added. “If which is not accessible, open up an IRA at a robo-advisor. The greatest robo-advisors for inexperienced persons offer you minimal minimums, financial advisors and easy set up.”

Katelyn Murray, CFP, economic planner and marriage manager at Kendall Funds, suggests putting the further resources into a Roth IRA.

“As lengthy as you at the moment have gained money, you can open up a Roth IRA and conserve the lesser of 100{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of your acquired profits or $6,000 ($7,000 if you’re more than age 50) 12 months over calendar year. Considering the fact that you’re saving to a Roth IRA, these funds are regarded as ‘after-tax’ retirement cost savings, that means that you can extract all principal and earnings 100{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} tax-no cost when you are in excess of 59 ½.”

Even though you may well not sense the have to have to prioritize saving for retirement just however, getting begun early is key.

“Money established apart now will have far more time to develop,” Rains mentioned.

Find out: 12 Essential Money Suggestions for Just about every Section of Your Money Everyday living

Make Inflation-Combating Investments

“To battle back versus the present amount of inflation, I would target on investing in Ideas or I-Bonds that are currently shelling out 7.12{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550},” explained Bob Lotich, qualified educator in private finance and founder of SeedTime.com.

You really should aim to commit on the other hand substantially you utilised to owe in every month college student personal loan payments.

“Take the precise amount you experienced beforehand been spending to service your student financial debt, and hold creating those payments per year, besides into an investment decision car or truck that can take advantage of the basic principle of compounding returns,” explained Bobby Matson, CEO of Payitoff. “Here’s some primary math. If your scholar personal loan payment was $400, if you had been to simply just commit that similar amount of money of money, every month, in the stock current market (let us say the S&P 500), in 30 several years you are going to have a portfolio truly worth $1,121,808 (if you carry on to reinvest your gains, and if the market place proceeds identical general performance more than the up coming 30 many years as it has above the earlier 100). Which is a fairly effective detail to grasp — $400 a thirty day period ultimately makes you a millionaire. Considering that you never ever anticipated to have your personal debt forgiven, you may possibly as properly pretend it has not been, and hold making these regular payments — besides as a substitute of paying out them to a lender, shell out them to your self.”

Additional From GOBankingRates

Gabrielle Olya contributed to the reporting for this short article.

This short article originally appeared on GOBankingRates.com: If Your College student Financial loans Have been Forgiven, Here’s What You Really should Do Up coming