Please help! My brother took out $20,000 in student loans in my father’s name without his consent. My parents refuse to take action

Expensive Quentin,

Remember to enable! I am incredibly worried for both of my dad and mom. I’m quite sure my brother took out university student financial loans below my parents’ names without their being aware of and I really do not consider they comprehend that they are liable for shelling out the money back again (not my brother) even nevertheless this was accomplished with no their consent.

I’m not guaranteed how my brother did this, but we uncovered out a pair of many years back when my father obtained a letter in the mail from the Department of Schooling. Wondering it experienced to do with my brother’s financial help, he opened it to obtain out that “he” had taken out thousands of bucks in loans to spend for my brother’s college training. 

‘They are also so shut to lastly paying off their home loan, I’d loathe to see them extend their retirement due to the financial loans or, even even worse, drop the residence they worked so tough for.’

At initially he was stunned, but when I stated it to him, he pretended to know what was heading on. Considering that then he has basically ignored the financial loans right up until recently, when he acquired a further letter notifying him that his financial loans are getting transferred to a new servicer (with new loans extra, full sum now becoming above $20,000). 

My mom keeps ignoring the loans because they had been not taken out less than her name. When I instructed them I meant to confront my brother about it, they informed me to remain out of it. But I cannot continue to be out of it. I treatment about both of those of my parents, and I don’t think it is correct for them to pay back back again credit card debt that was by no means theirs.

Both of those of my mothers and fathers are about to change 60 shortly and they are setting up to believe about retirement. They are also so close to finally paying off their house loan, I’d dislike to see them lengthen their retirement due to the loans or, even worse, shed the house they worked so hard for. 

If my brother could not afford the school with financial loans beneath his identify he ought to have by no means gone there. Is there any way we can swap the financial loans to my brother’s name so he pays again his credit card debt? And can the financial loans affect my mom because my mother and father are married?

Concerned Daughter

Pricey Daughter,

If you are absolutely sure that your brother took these financial loans out with no your parents’ consent, and solid their signatures on the bank loan paperwork, you could put your brother on observe that he faces serious penalties if he fails to spend off the personal loan in a well timed manner. It may possibly or might not gentle a fireplace under him to at the very least make guaranteed selection organizations really don’t knock on your parents’ doorway.

You just can’t power your mothers and fathers to choose motion, of study course, unless of course you described the alleged financial loan fraud to the police — and even then, your moms and dads could say they authorised the bank loan, generating any upcoming claim hard. The for a longer period your mother and father know about the loans taken out in their name and continue on to do practically nothing about it, the much more difficult the case for discharging them becomes.

An unpaid university student-loan debt could turn out to be a drain on your parents’ joint money and price savings the federal government could garnish tax refunds for a federal personal loan and if your father’s credit rating suffers, that has an effect on your mom really should they need to refinance their home because of to clinical emergencies or other unexpected events. If they dwell in a group-home state, they may possibly each be responsible for the bank loan.

If they needed to discharge this credit card debt? They would probable have to have to file an id-theft assert. Yet again, that would call for a law enforcement report and/or a court conviction. But it would seem like they do not want to place your brother — or themselves — by this sort of a traumatic system. In that scenario, they have no choice but to spend the financial debt if your brother defaults, and take it out of his inheritance.

You can e mail The Moneyist with any financial and ethical issues related to coronavirus at qfottrell@marketwatch.com, and abide by Quentin Fottrell on Twitter.

Verify out the Moneyist non-public Facebook team, the place we seem for answers to life’s thorniest money problems. Viewers produce in to me with all types of dilemmas. Write-up your issues, inform me what you want to know a lot more about, or weigh in on the most recent Moneyist columns.

The Moneyist regrets he are not able to reply to queries independently.

A lot more from Quentin Fottrell:

• My married sister is serving to herself to our parents’ most treasured belongings. How do I stop her from plundering their residence?
• My mom experienced my grandfather sign a belief leaving tens of millions of dollars to two grandkids, shunning everybody else
• My brother’s shortly-to-be ex-wife is embezzling revenue from their business enterprise. How do we locate concealed accounts?
• ‘Grandma just lately passed away, leaving powering a 7-figure estate. Pointless to say, factors are getting messy’

Easy Way to Tax Billionaires That Would Actually Work: Tax the Loans

  • The ultra-wealthy prevent paying taxes by working with inventory as collateral for financial loans and deferring the sale of assets.
  • Reasonable and effective tax coverage would treat significant individual loans for the rich equivalent to recognized earnings.
  • Tax policy should goal consumption and the “invest in, borrow, die” tax avoidance schemes of the wealthy. 
  • Emil Skandul is an view writer on economic policy and is the founder of a digital innovation firm, Capitol Foundry.
  • This is an feeling column. The ideas expressed are those of the author. 

With the infrastructure invoice now having passed Congress, the debate about the distinct tax insurance policies to fund the infrastructure invoice around the previous a number of months has come to a non permanent quietus. The bill is with out a immediate enhance on taxes, and the ultra-wealthy keep on being unscathed — at minimum for now.

Continue to, pressure has mounted on billionaires so substantially that Elon Musk has tried to handle the difficulty head on. “Significantly is manufactured currently of unrealized gains currently being a implies of tax avoidance, so I propose advertising 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of my Tesla inventory,” he tweeted earlier this thirty day period. The selection was finally built by polling his followers — all-around 4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of his holdings have now been liquidated.

For the several impractical tax techniques released by economists and associates of Congress, none have resolved how the wealthiest Individuals prevent shelling out taxes to start with: They get out financial loans to dwell on employing their stock as collateral. In point, the probably inspiration for Musk to sell off some of his Tesla shares was to pay back off these loans.

So if reduced-fascination financial loans are employed by rich people to keep away from offering shares and spending


cash gains

taxes, the resolution ought to be clear: Specifically tax the fundamental loans that are handled as individual profits.

A slew of negative tax policy

Wealth taxes are a plan debate that has grown ferociously louder over the a long time, and it has mounted the affluent in the crosshairs of legislators and the community. In latest many years, it has come to be a central concept in strategies, political messaging, and information tales about growing money inequality.

Considerably of America’s knowing of why earnings inequality is unavoidable and how it has achieved the best amounts considering the fact that the Gilded Age can be attributed to the French economist Thomas Piketty’s “Cash in The 20-First Century,” which laid the groundwork for the arguments for increasing taxes on the rich. There is a greater return on cash than on labor, and the larger a fortune, the more rapidly it will grow. Fortunes of the top rated 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} are consistently significantly less diversified, and often accumulate exclusively in a single or two companies.

The quantities discuss for them selves. The best 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Americans these days have accumulated 27{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of full wealth. Even far more glaringly, given that the start of the pandemic, additional than half a trillion dollars has been extra to the net value of billionaires, whose numbers have elevated by 13.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. When web well worth has amplified more than the past decade, this benefit remains locked up in the corporations owned by these folks, unless of course shares are offered or borrowed towards. From taxing unrealized gains to applying an once-a-year wealth tax, a amount of haphazard proposals have attempted to concurrently fund public investments and seize these unrealized gains in prosperity.

Senator Elizabeth Warren’s 2{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} annual wealth tax for individuals men and women with a net worth over $50 million was a person tax response. Nevertheless, when this plan was applied in France, it led to 10,000 French nationals leaving the country in purchase to steer clear of staying taxed. The economists guiding the prepare, Gabriel Zucman and Emmanuel Saez, argue that mobility and expatriation taxes are distinct in the US than in Europe — so the exact same state of affairs would be unlikely. But in a highly globalized and mobile globe, there would unquestionably be some attrition. The decline of even a fraction of the US’s most ambitious and entrepreneurial minds together with their funds would be terrible for the US financial system and is not value the downsides of a tax experiment that has been attempted ahead of. 

Even far more recently, a proposal by Senate Finance Chair Ron Wyden bundled a prepare to tax unrealized gains. Billionaires are capable to stay clear of extensive-expression capital gains taxes of 23.8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} by under no circumstances selling shares in the firms they have if the expectation is that the shares will boost in value. This approach has permitted the rich to just take out loans, which are later refinanced as a stock’s benefit increases in order to pay back again earlier loans. This can be carried out ad infinitum as a stock’s benefit boosts, which means the borrower never ever has to offer shares to pay out again the loans. 

Even so, taxing an unrealized acquire leads to a by no means-ending sequence of queries regarding fairness and implementation. When exactly do you execute the tax if someone’s net worth is fluctuating because of a volatile inventory selling price? If a stock is worth $3 nowadays and $1 tomorrow, and no inventory sale has transpired, is it honest to successfully accumulate the remaining quantity due to the fact it was worthy of $3 yesterday?

Moreover, there is the problem with


liquidity

as Musk’s new sale has revealed. Providing any substantial range of shares in a organization will signify there will have to be consumers for these shares, and if not, then a big sale will noticeably minimize the selling price of the inventory as it did for Tesla, the cost of which in the beginning fell 15.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to get better 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. Furthermore, for other illiquid assets, these types of as actual estate and art, how do you collect on the appreciation in price?

Handle huge financial loans as realized revenue

The equation for prosperity preservation may be greatest summed up as: “obtain, borrow, die.” In spite of this, tax policy has put “borrowing” in a blind place — a financial loan is viewed as a debt, not an asset.

Possession of a corporation or a stock only has worth if it can generate dollars flow or has resale benefit to other individuals. But when shares are employed as collateral to attract a line of credit and stay clear of a taxable party, it creates immediate price for the operator. Honest and productive tax plan would handle big individual loans comparable to realized cash flow, because the price from the inventory is being extracted, even if impermanently, by the operator.

By positioning a tax of 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} on big financial loans that are drawn towards present assets, the knock-on impact may perhaps also involve superior web-value people to voluntarily provide their assets to deal with the expenses of the principal and interest, thus triggering a bigger funds gains tax. This tax plan would correctly lessen this popular tax avoidance scheme used by the wealthy all-around the planet. It would ensure that the benefit that is captured by borrowing in opposition to property is taxed — a worth that grows larger every 12 months. According to some estimates, the wealthiest Individuals prevent paying out $163 billion in taxes each and every calendar year, and financial debt is the most important software utilised to escape tax burdens. 

Indirectly taxing intake — the prosperity derived from own loans — and inheritances is an technique to the dilemma of hyper-wealth accumulation that Musk, shockingly, would concur with. Combined with other prudent tax procedures like targeting trusts and foundations as nicely as loopholes in estate taxes, an uncomplicated tax framework emerges that taxes individuals right after offering, borrowing, and dying. It really is this route of minimum resistance to making sure taxes are gathered that will demand concentrating on the techniques like asset-based lending that have enabled the extremely-wealthy to eschew paying taxes. 

Black neighborhoods in Chicago targeted by high-interest loans

Pointing out that high-interest loans proliferate in non-white Chicago neighborhoods is a bit like saying the sky is blue or the grass is green, but a consumer group says it’s proving it for the first time with hard numbers.

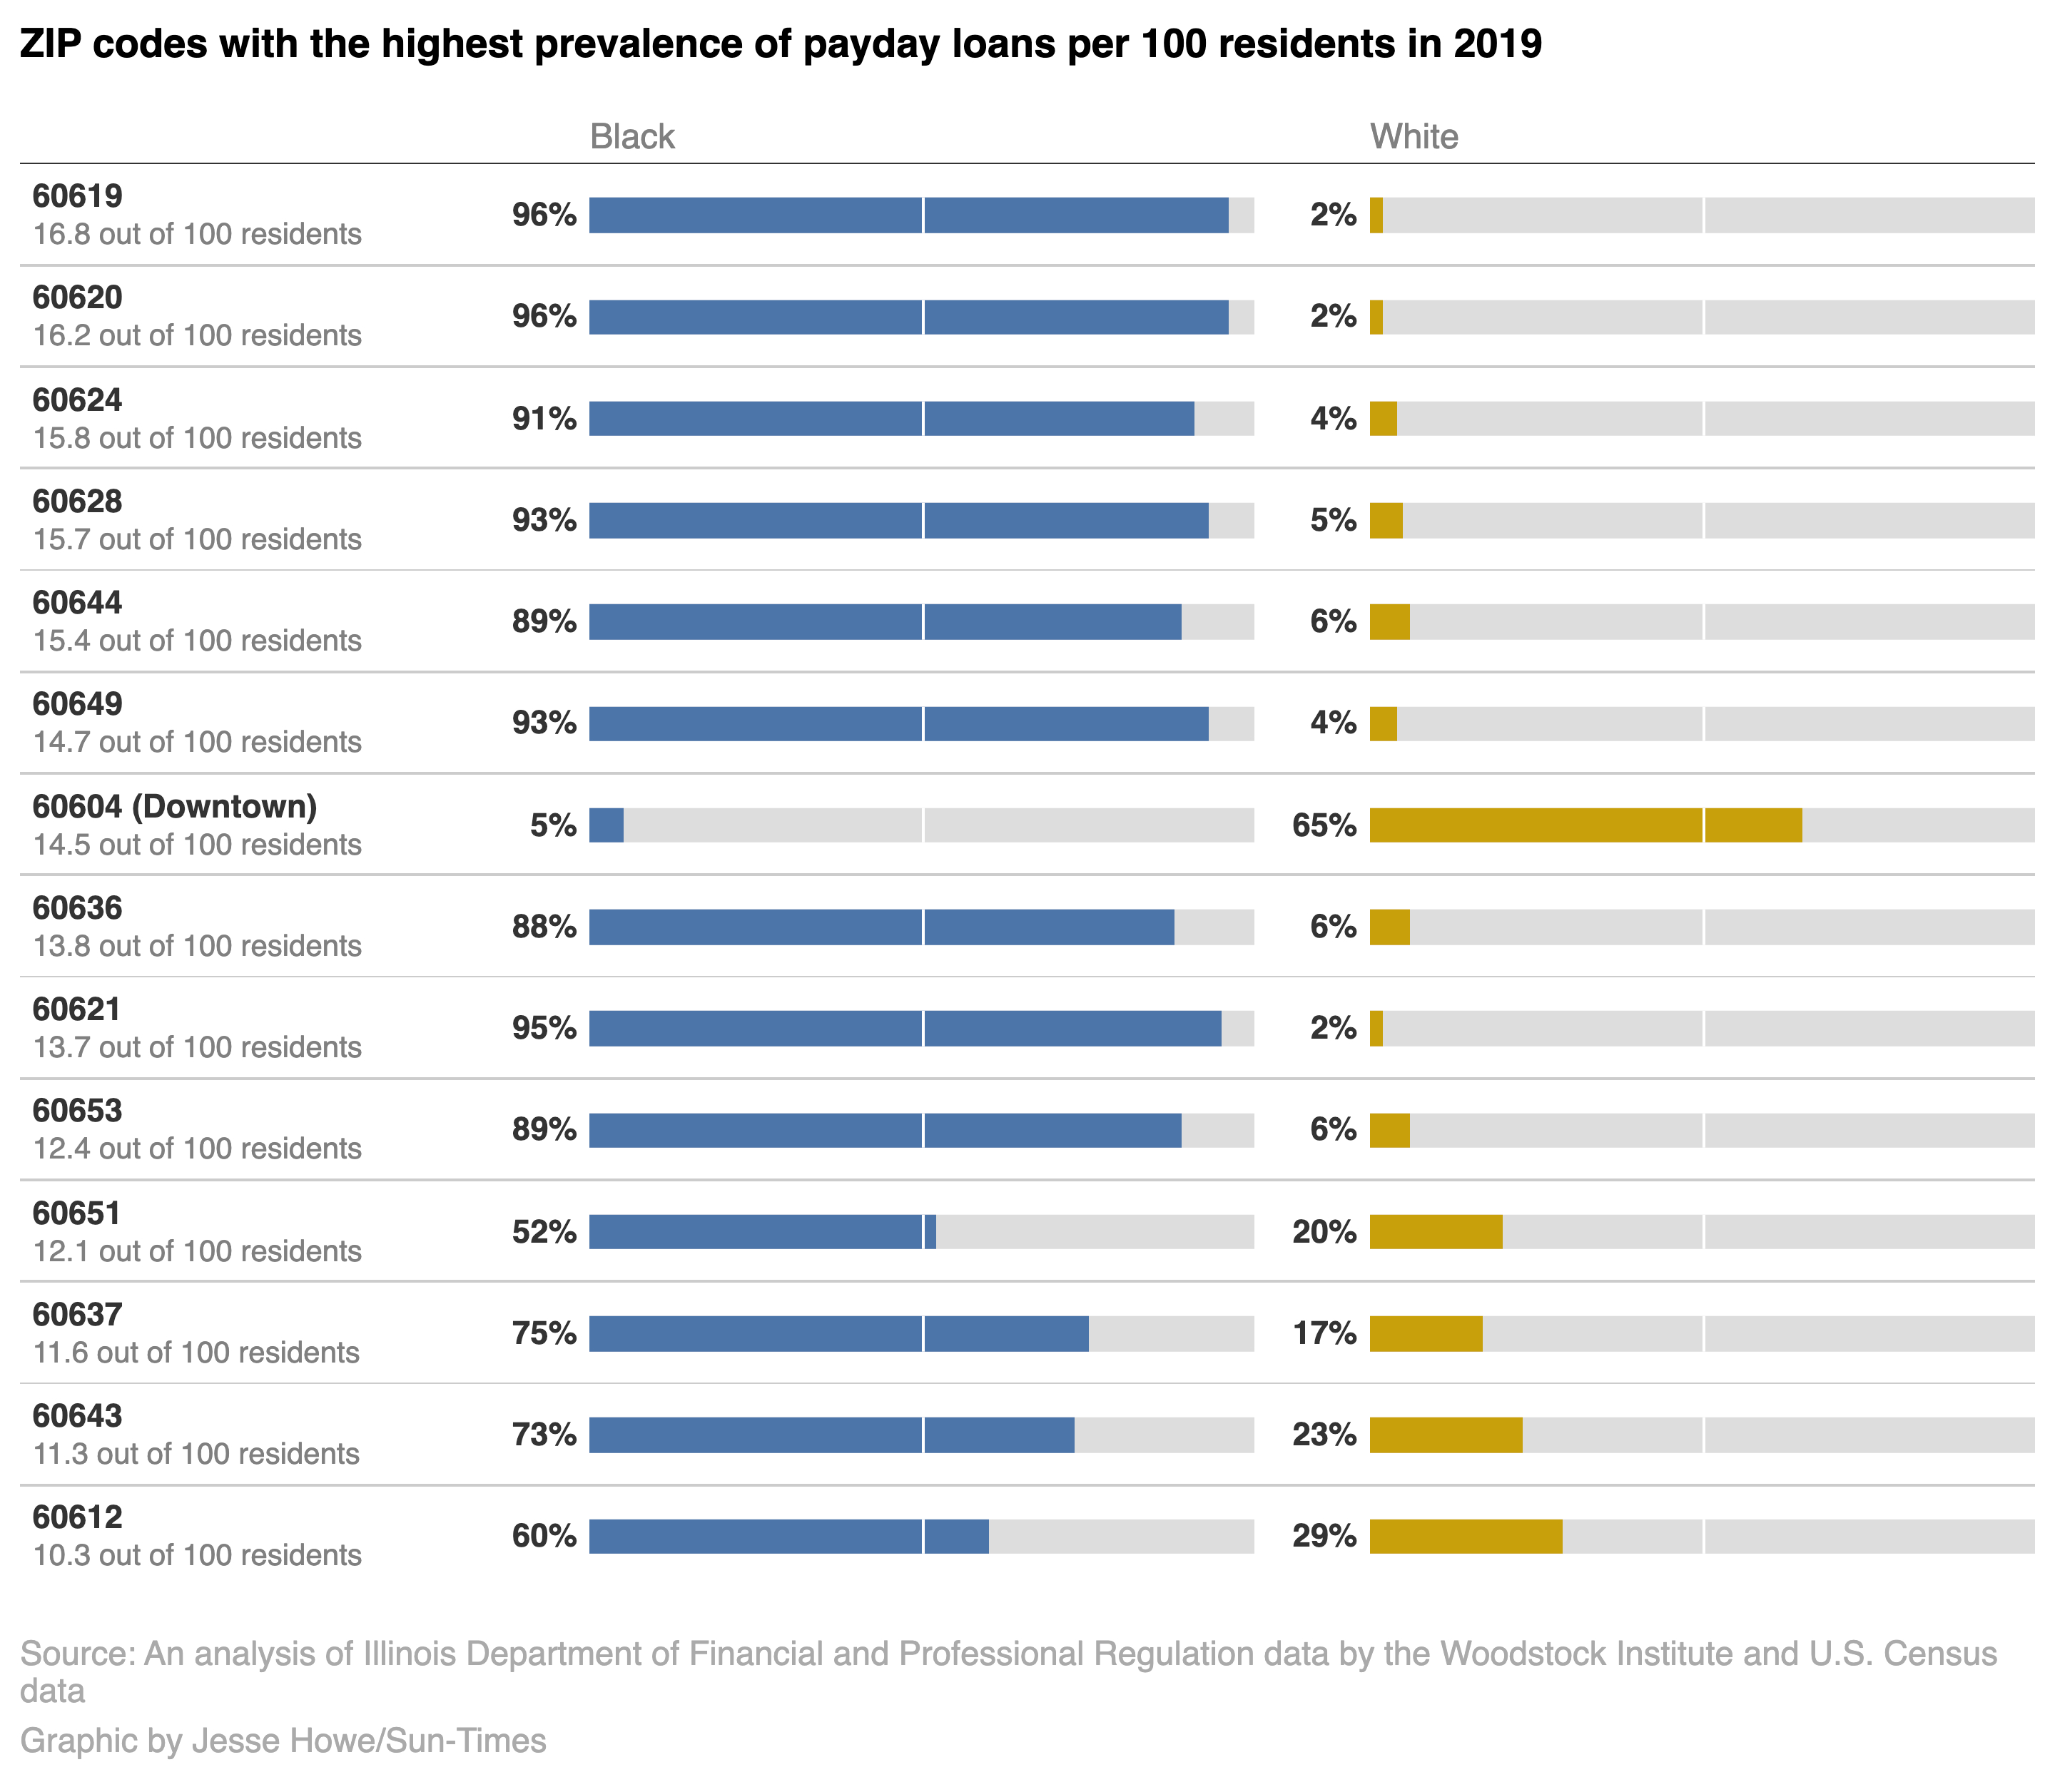
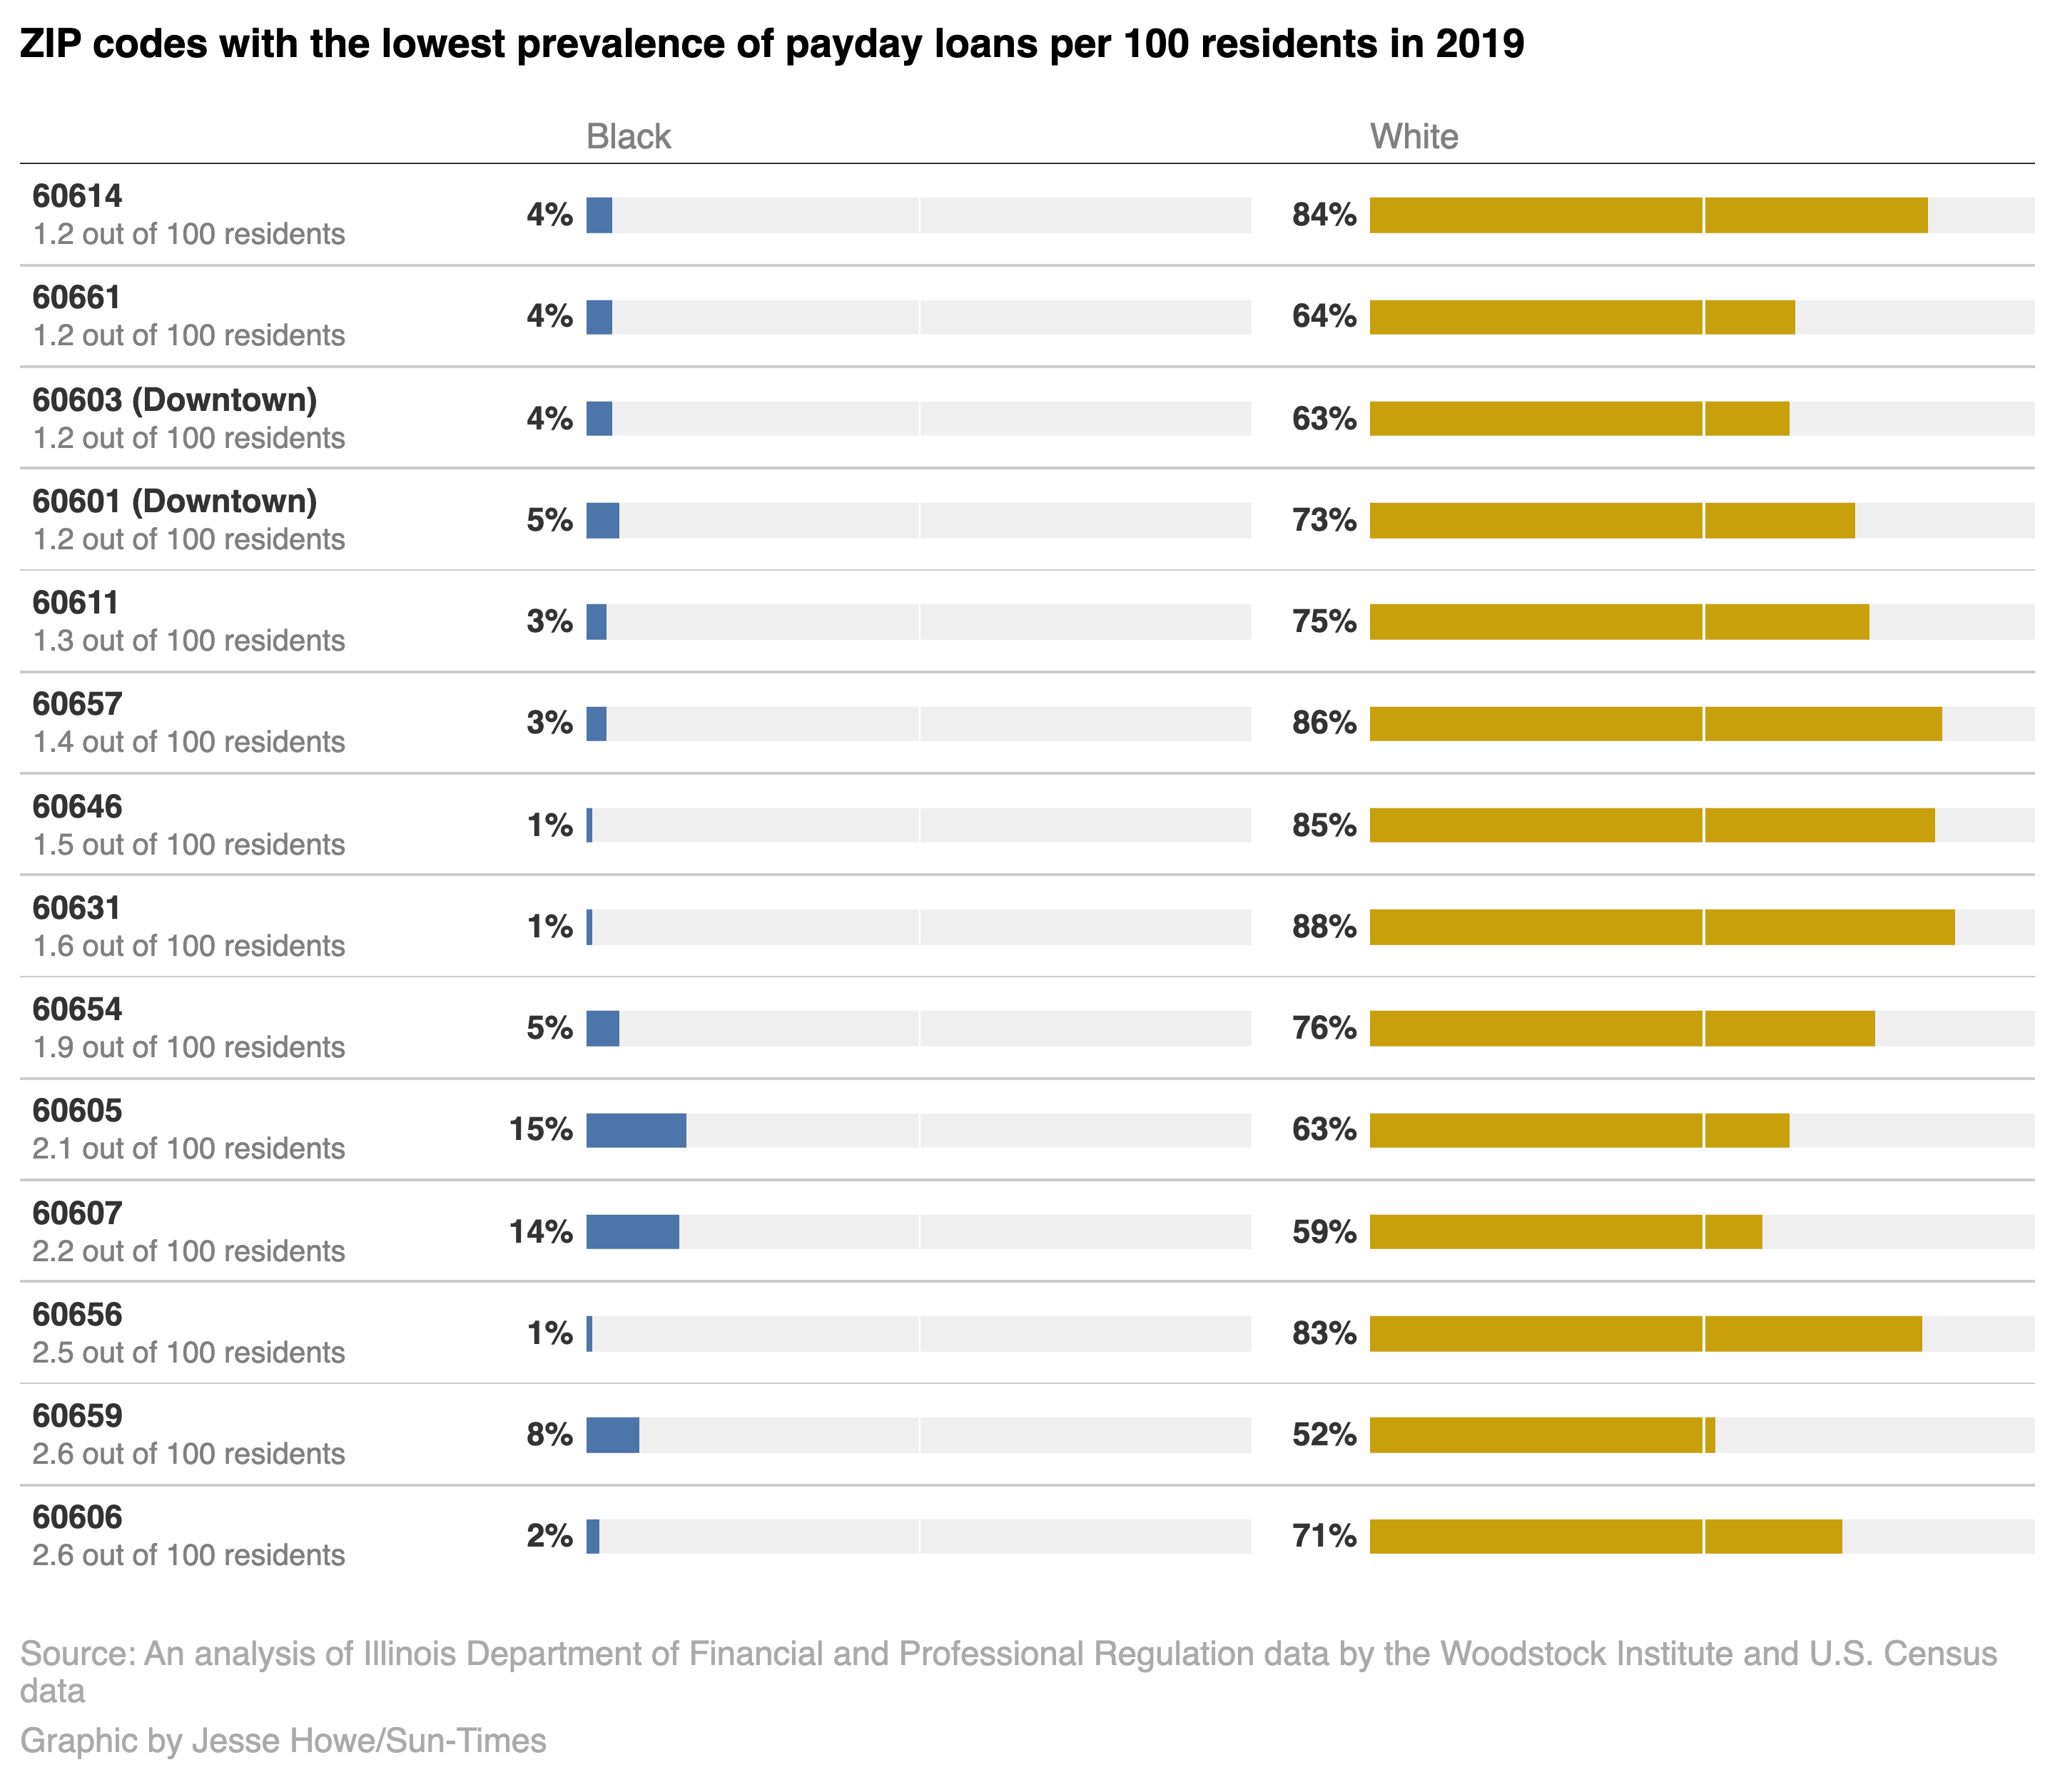
Using 2019 borrower loan data obtained from state regulators, the nonprofit Woodstock Institute found the top ZIP codes for payday loans, excluding the Loop, were majority-Black, including:

  • 60619 and 60620 on the South Side, which include parts of Chatham, Burnside, Avalon Park and Greater Grand Crossing, Auburn Gresham and Washington Heights. Those ZIP codes had more than 16 payday loans per 100 people and are both 95.7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} Black.
  • 60624 on the West Side, which includes parts of West Garfield Park, East Garfield Park and Humboldt Park and which had 15.8 payday loans per 100 people. That ZIP code covers an area that’s 90.7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} Black.

In contrast, ZIP codes with the lowest incidence of payday borrowers were mostly white, such as 60614 in Lincoln Park. That area had 1.1 payday loans per 100 people in a ZIP code that’s 84{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} white.


The analysis included ZIP code data for borrowers with payday loans and payday installment loans, which largely disappeared as of March 23, when a new interest rate cap took effect in Illinois. The nonprofit group obtained the data through a records request to the Illinois Department of Financial and Professional Regulation.

Data from 2020 — though a strange year for lending due to the COVID pandemic — was similar, with the top two ZIP codes 60619 and 60620, followed by 60628, which covers parts of Roseland, Pullman, West Pullman and Riverdale, and which is 93.1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} Black.

Brent Adams, senior vice president of the Woodstock Institute and IDFPR director under former Gov. Pat Quinn, called it “statistical significance on steroids.”

“These loans very specifically target Black communities,” Adams says, adding that high-interest lending perpetuates a status quo “that is riddled with racial and economic inequities.”

Headshot of Brent Adams, senior vice president of the Woodstock Institute.

Brent Adams, senior vice president of the Woodstock Institute.
Provided

Studies have shown Black Americans have an average net worth that’s about one-tenth that of white Americans, largely due to past discriminatory practices that hindered the accumulation of family wealth, including denial of home mortgages.

The industry says it provides a necessary service for people who don’t have the credit history or collateral to qualify for traditional bank loans.

In Illinois, as of March 23, payday loans, title loans and installment loans must abide by a 36{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} cap on the annual percentage rate of interest. The Illinois Predatory Loan Prevention Act also forces vehicle financing to adhere to the cap.

Tiffany Moore of Forest Park turned to an installment lender for the first time when the coronavirus hit and a tenant at her investment property couldn’t make rent. Her loan, for $9,500, had a term of five years and an interest rate of 35.989{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Even with a rate under 36{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, she realized she’d be paying back more than twice what she borrowed. So Moore paid it off early.

“I was like, I’ve got to get rid of this,” she says. “How can you get ahead if they’re charging all that interest?”

Tiffany Moore is seen in a photo from the shoulder up, standing outside near some colorful fall foliage. The Forest Park woman turned to an installment loan with an interest rate just under 36{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} during the pandemic. She says she almost immediately realized it was a bad deal.

Tiffany Moore of Forest Park turned to an installment loan with an interest rate of just under 36{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} during the pandemic when a tenant at her investment property couldn’t make rent. She says she almost immediately realized it was a bad deal.
Brian Ernst/Sun-Times

Ed D’Alessio, executive director of INFiN, a trade group that counts small-dollar lenders among its members, says the Woodstock analysis is “nothing more than a thought experiment that distracts from the real challenges facing borrowers today.”

D’Alessio says many borrowers are “underserved, overlooked or left behind by other financial institutions.”

The 36{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} cap has already caused some payday and small-dollar lenders to shutter their Illinois locations, he says.

Samantha Carl of Palatine says the storefront lender she used in the suburbs has since closed. She got a $700 loan before the 36{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} cap that had an APR of 399{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. She paid it off in a matter of months, but it still cost her about $1,200, she says.

“It helped when I needed it, but the interest rate is crazy,” says Carl, who relies on monthly disability checks and was hit with a sudden car repair.

Ed McFadden, spokesman for the American Financial Services Association, which represents installment lenders but does not include payday or auto title lenders, says the new law may have unintended consequences.

He points to a 2015 Federal Reserve survey in which lenders said they cannot break even on loans under $2,532 at 36{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} APR.

“The rate cap may make policymakers and interest groups feel good about themselves, but it leaves many consumers who are already struggling out in a credit desert,” he says.

But Adams says there are alternatives, such as the Capital Good Fund, which lends to underserved consumers and charges an average interest rate of 13{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Everything you need to know about adoption loans

Our goal here at Credible Operations, Inc., NMLS Number 1681276, referred to as “Credible” below, is to give you the tools and confidence you need to improve your finances. Although we do promote products from our partner lenders who compensate us for our services, all opinions are our own.

Adoption loans and grants can help you cover the costs of adopting a child. Learn more about lenders and other organizations that offer them. (iStock)

Deciding to grow your family through adoption is exciting, but it can also be expensive. Adoption-related expenses vary widely depending on whether you’re adopting a child from foster care, going through a private agency, or adopting internationally. 

Adopting a child from foster care involves very little expense because federal and state adoption assistance programs help offset costs. But a private adoption can cost anywhere from $20,000 to $45,000, and an intercountry adoption averages between $20,000 and $50,000, according to the Child Welfare Information Gateway.

Fortunately, adoption loans can help you finance these costs. Here’s what you need to know about adoption loans.

Check out Credible to compare personal loan rates and find one that’s right for you.

Can I get a loan to finance an adoption?

In short, yes. Many prospective parents turn to adoption loans to help pay for the cost of adoption. In fact, adoption loans come in several different forms. Some lenders offer loans specifically for adoption. But you may also be able to use a personal loan to finance your adoption costs.

Lenders that offer adoption loans 

The following 13 Credible partner lenders offer personal loans that can be used for adoption expenses.

Avant

  • Loan amounts: $2,000 to $35,000
  • Loan terms: 2 to 5 years
  • Best for: Borrowers who don’t have good credit

Axos

  • Loan amounts: $5,000 to $35,000
  • Loan terms: 1 to 5 years
  • Best for: Borrowers with good to excellent credit

Best Egg

  • Loan amounts: $2,000 to $50,000
  • Loan terms: 2 to 5 years
  • Best for: Borrowers with lower income and fair credit

Discover

  • Loan amounts: $2,500 to $35,000
  • Loan terms: 3 to 7 years
  • Best for: Borrowers who want fast funding

FreedomPlus

  • Loan amounts: $10,000 to $35,000
  • Loan terms: 2 to 5 years
  • Best for: Borrowers who want to choose their own payment date

LendingClub

  • Loan amounts: $1,000 to $40,000
  • Loan terms: 3 or 5 years
  • Best for: Borrowers with a strong credit score and low debt-to-income ratio

LendingPoint

  • Loan amounts: $2,000 to $36,500
  • Loan terms: 2 to 4 years
  • Best for: Borrowers with fair credit

LightStream

  • Loan amounts: $5,000 to $100,000
  • Loan terms: 2 to 7 years
  • Best for: Borrowers who want longer repayment terms

Marcus

  • Loan amounts: $3,500 to $40,000
  • Loan terms: 3 to 6 years
  • Best for: Borrowers who want tailored monthly payments

Prosper

  • Loan amounts: $2,000 to $40,000
  • Loan terms: 3 or 5 years
  • Best for: Borrowers who want to pay off their loan early

SoFi

  • Loan amounts: $5,000 to $100,000
  • Loan terms: 2 to 7 years
  • Best for: Borrowers with excellent credit

Upgrade

  • Loan amounts: $1,000 to $50,000
  • Loan terms: 2 to 7 years
  • Best for: Borrowers who are building credit

Upstart

  • Loan amounts: $1,000 to $50,000
  • Loan terms: 3 to 5 years
  • Best for: Borrowers who don’t have strong credit but have an excellent education or job history

Interest-free adoption loans

Some nonprofits and religious organizations offer interest-free adoption loans to adoptive families who meet their criteria. Here are a few options to consider:

  • ABBA Fund The ABBA Fund offers loans designed to cover up to one-third of the overall cost of an adoption, usually in the range of $6,000 to $8,000. Application approval for a zero-interest adoption loan takes six to eight weeks.
  • Hebrew Free Loan Hebrew Free Loan is a nonprofit organization that provides interest-free loans of up to $20,000 to help Jewish individuals and couples in Northern California cover the cost of adoption. To qualify, you must be a Jewish resident of Northern California or working for a Jewish organization in Northern California.
  • Lifesong for Orphans Lifesong for Orphans provides no-interest loans only to traditional two-parent Christian families who are U.S. citizens. The application review process takes four to six weeks.
  • Pathways for Little Feet Pathways for Little Feet provides interest-free loans of up to $8,000. Priority is given to families with the greatest financial need. Applicants must work with a licensed adoption agency.

If you don’t qualify for one of these adoption loans, you can compare personal loan rates for adoption expenses using Credible.

What’s the difference between adoption loans and grants?

Both adoption loans and grants offer funds to help adoptive parents cover the cost of adoptions, but there’s a crucial difference: Adoption loans must be paid back, whereas adoption grants are gifts that don’t have to be repaid.

Because they don’t have to be repaid, there can be a lot of competition for adoption grant resources. It’s a good idea to apply for a variety of adoption grants to improve your chances of getting some financial assistance.

Here are a couple adoption grants to consider:

  • Gift of Adoption Fund The Gift of Adoption Fund offers grants of up to $15,000 to help individuals complete a relative, domestic, or international adoption. Grants are awarded without regard to race, religion, age, marital status, or sexual orientation. Applicants must submit two letters of reference and a $50 application fee with their completed application.
  • HelpUsAdopt.org HelpUsAdopt.org provides adoption grants between $500 and $15,000 to couples and individuals regardless of race, religion, gender, ethnicity, marital status, or sexual orientation. At least one applicant must be a U.S. citizen, and applicants must use a licensed adoption agency in the U.S. The organization prioritizes applicants without children or with failed or disrupted adoption placements.

What are some adoption loan alternatives?

Adoption loans and grants aren’t the only options for financing your adoption costs. Here are some alternatives to consider:

If a personal loan for adoption costs is right for you, visit Credible to compare personal loan rates in minutes.

Personal loans for non-U.S. citizens: What you need to know

Our goal here at Credible Operations, Inc., NMLS Number 1681276, referred to as “Credible” below, is to give you the tools and confidence you need to improve your finances. Although we do promote products from our partner lenders who compensate us for our services, all opinions are our own.

Lenders that offer loans for non-U.S. citizens typically require a valid work visa and proof of employment. (iStock)

Moving to a new country and establishing residency there can be expensive. Covering the cost of travel, housing, and setting up your life in the United States can quickly deplete your savings account or force you to go into debt.

Personal loans can be a good option to cover some of these expenses or consolidate other high-interest debts, but for noncitizens in the U.S., getting a personal loan can be difficult. 

Lenders may worry that non-U.S. citizens will leave the country without paying, leaving the lender on the hook if they don’t repay the loan. Some lenders also shy away from providing loans to Deferred Action for Childhood Arrivals (DACA) recipients because the laws could change at any time, and the DACA recipient could be deported, leaving the bank unable to recover its money.

Despite this hesitancy, it’s possible for noncitizens to take out a loan in the United States. Here’s what you need to know about personal loans for non-U.S. citizens. 

With Credible, you can compare personal loan rates from multiple lenders in minutes.

Can I get a personal loan as a non-U.S. citizen?

Non-U.S. citizens can get personal loans. But not all financial institutions and lenders offer loans to noncitizens, and the requirements vary by lender.

Some lenders require a high credit score, while some don’t have a minimum credit score, instead looking at other factors, such as your income and education.

11 best lenders that offer personal loans to non-U.S. citizens

Not all lenders offer personal loans to non-U.S. citizens, but some do. The following 11 lenders are Credible partners.

Axos Bank

Axos Bank doesn’t charge a prepayment penalty, so it’s a good option for borrowers who want to pay off their personal loans early.

  • Loan amounts: $5,000 to $35,000
  • Loan terms: 1 to 5 years
  • Minimum credit score: 740
  • Time to fund: As soon as the next business day
  • Best for: Fast loan funding

Best Egg

Best Egg personal loans are available in all states except Iowa, Vermont, West Virginia and the District of Columbia.

  • Loan amounts: $2,000 to $50,000
  • Loan terms: 2 to 5 years
  • Minimum credit score: 600
  • Time to fund: As soon as 1 to 3 business days after successful verification
  • Best for: Credit card refinancing or debt consolidation

Discover 

Discover offers personal loans for a variety of uses, including auto repair, credit card refinancing and debt consolidation. 

  • Loan amounts: $2,500 to $35,000
  • Loan terms: 3 to 7 years
  • Minimum credit score: 660
  • Time to fund: As soon as the next business day after acceptance
  • Best for: Longer repayment terms

FreedomPlus

FreedomPlus doesn’t have a minimum income requirement for personal loan applicants.

  • Loan amounts: $10,000 to $50,000
  • Loan terms: 2 to 5 years
  • Minimum credit score: Does not disclose
  • Time to fund: As soon as 2 business days
  • Best for: Larger loan amounts

LendingClub

LendingClub offers peer-to-peer lending, matching borrowers with investors who lend money.

  • Loan amounts: $1,000 to $40,000
  • Loan terms: 3 or 5 years
  • Minimum credit score: 600
  • Time to fund: Usually about 2 days
  • Best for: Borrowers with a low debt-to-income ratio

LendingPoint

With a minimum credit score requirement of 580, LendingPoint makes personal loans available to applicants with less-than-perfect credit.

  • Loan amounts: $2,000 to $36,500
  • Loan terms: 2 to 4 years
  • Minimum credit score: 580
  • Time to fund: As soon as the next business day
  • Best for: Borrowers with lower credit scores

Marcus

Marcus has a higher minimum credit score but allows you to defer a monthly payment after making 12 on-time payments.

  • Loan amounts: $3,500 to $40,000
  • Loan terms: 3 to 6 years
  • Minimum credit score: 660
  • Time to fund: As soon as 3 days
  • Best for: Borrowers who want tailored monthly payment options

PenFed

PenFed offers personal loans to applicants with good to excellent credit.

  • Loan amounts: $600 to $50,000
  • Loan terms: 1 to 5 years
  • Minimum credit score: 660
  • Time to fund: 2 to 4 business days after verification
  • Best for: Small loan amounts

SoFi

SoFi offers large personal loans to borrowers with high credit scores.

  • Loan amounts: $5,000 to $100,000
  • Loan terms: 2 to 7 years
  • Minimum credit score: Does not disclose
  • Time to fund: 3 business days
  • Best for: Borrowers with excellent credit

Upgrade

In addition to fast funding for its personal loans, Upgrade offers free credit monitoring.

  • Loan amounts: $1,000 to $50,000
  • Loan terms: 2 to 7 years
  • Minimum credit score: 560
  • Time to fund: Within a day of clearing necessary verifications
  • Best for: Borrowers who are building credit

Upstart

Upstart is a good option for borrowers with below-average or no credit because the lender considers other factors, such as education and job history, as part of overall eligibility.

  • Loan amounts: $1,000 to $50,000
  • Loan terms: 3 to 5 years
  • Minimum credit score: 580
  • Time to fund: As soon as 1 business day
  • Best for: Borrowers with a strong work or education history

Check out Credible to compare personal loan rates from various lenders and find the right one for you.

Other lenders to consider

The following two lenders are not Credible partners, so you won’t be able to easily compare your rates with them on the Credible platform. But they may also be worth considering if you’re looking for a personal loan as a non-U.S. citizen.

Earnest

Earnest can match you with loan options in less than 60 seconds.

  • Loan amounts: $1,000 to $250,000
  • Loan terms: 6 months to 12 years
  • Minimum credit score: Does not disclose
  • Time to fund: Does not disclose
  • Best for: Longer repayment terms

Stilt

Stilt specializes in personal loans for immigrants and other underserved markets and doesn’t require applicants to have a Social Security number or credit history.

  • Loan amounts: $1,000 to $35,000
  • Loan terms: 1 to 3 years
  • Minimum credit score: None
  • Time to fund: As soon as the next business day
  • Best for: Borrowers with no Social Security number

Methodology

Credible evaluated the best personal loan lenders based on factors such as customer experience, minimum fixed rate, maximum loan amount, funding time, loan terms, and fees. Credible’s team of experts gathered information from each lender’s website, customer service department, and via email support. Each data point was verified to make sure it was up to date.

What are the eligibility requirements for loans for non-U.S. citizens?

The exact requirements for personal loans for non-U.S. citizens vary by lender. Some common eligibility guidelines include:

  • U.S. residence
  • A U.S.-based bank account and U.S.-based phone number
  • A green card or valid work visa (E-2, E-3, H-1B, J-1, L1, or O-1)
  • Proof that you’re currently employed or have accepted a job offer
  • U.S. credit history or credit history in your home country
  • Proof of on-time payments on a mortgage, rental, or utilities in the U.S.

What will I need for my application?

You’ll need specific documents and information when applying for a personal loan as a non-U.S. citizen. While the exact documentation requirements vary by lender, at a minimum, you may need to provide:

Personal information

You’ll need to provide some basic personal information to apply for a personal loan, including your name, date of birth, physical address, email, phone number, Social Security number (or Individual Taxpayer Identification Number), employer, and income.

You may also need to provide documentation to confirm this information, such as a utility bill to verify your address, a copy of your valid driver’s license or other government-issued identification, and copies of bank statements and tax returns.

Credit check

Lenders typically check your credit score, even if you don’t have a U.S. credit score or a Social Security number. 

Proof of income

The lender will usually ask for specific paperwork to verify the income information included on your loan application, such as a copy of your recent pay stubs.

Loans for non-U.S. citizens FAQs

If you’re getting ready to apply for a personal loan, you likely have a million questions running through your head. To help you out, here are the answers to some common questions about personal loans for non-U.S. citizens.

What types of personal loans can I apply for as a non-U.S. citizen?

Lenders offer personal loans for many different uses. For example, you may be able to get a personal loan to consolidate other debts, make home improvements, cover auto repairs or medical bills, start a business, or make a large purchase. Be sure to check that your lender offers funds for your needs before you accept the loan.

Can I get a personal loan without a Social Security number?

Yes. Lenders that work with non-U.S. citizens know that most noncitizens aren’t eligible for a Social Security number. Instead, lenders may require you to have an Individual Taxpayer Identification Number, which is a tax-processing number assigned by the IRS to certain nonresidents and resident aliens.

Can a nonresident get a personal loan?

Personal loans are typically only available to nonresidents who plan to stay and work in the U.S. longer than their loan’s term. If you don’t plan on staying in the U.S. that long, lenders likely won’t approve your application.

Also, expect the lender to require documentation supporting your continued employment and income, such as your employment authorization form, details on your visa, and an employment contract.

How much can non-U.S. citizens borrow?

The amount you’re able to borrow depends on your unique financial situation, but Credible’s partners offer personal loans of up to $100,000 to non-U.S. citizens. If you can’t qualify for that much on your own, you may be eligible to borrow a larger amount with a cosigner who has good or excellent credit.

Do I need a cosigner?

Whether you need a cosigner depends on your unique financial circumstances and the lender’s requirements. Some lenders don’t require a cosigner, while some lenders require borrowers without a valid visa to apply with a cosigner with good to excellent credit and who’s a U.S. citizen or permanent resident. Other lenders may only require a cosigner if you don’t have a good credit history or don’t earn enough income to qualify independently.

Applying with a cosigner could benefit you if it helps you qualify for lower interest rates.

If you’re ready to apply for a personal loan, visit Credible to easily compare personal loan rates.


Navy sailors forced to take out loans after being shorted on pay

Some U.S. Navy sailors have been forced to take out loans over months-long delays in pay to some service members who earned increases in their housing allowances this year due to recent marriages or moving somewhere with a higher cost of living. 

“This is happening a little bit of everywhere,” Navy-Marine Corps Relief Society Vice President Gillian Gonzalez said in an interview with Military.com. “It doesn’t seem to hit one geographic area more than another.” 

Gonzalez recounted that her group has seen an uptick in loan applications from sailors who are struggling to keep up with living expenses but did not have an exact figure on the increase.

NAVY SAILORS WHO REFUSE COVID-19 VACCINE WILL BE DISCHARGED, FACE OTHER ADMINISTRATIVE ACTIONS

The U.S. Navy is looking to develop amphibious vessels that work in the sea and air, according to budget materials submitted for the fiscal year of 2022. (iStock)

The U.S. Navy is looking to develop amphibious vessels that work in the sea and air, according to budget materials submitted for the fiscal year of 2022. (iStock)

Cmdr. Matt Knight, public affairs officer at Navy Personnel Command, told the outlet that the Department of Defense requires the Navy to process Basic Allowance for Housing change requests within 30 days, but noted delays can happen. 

“Navy Personnel Command and our subordinate commands take every measure to ensure the volume of transactions does not exceed our capacity, but occasionally backlogs do occur due to a variety of reasons. These backlogs are resolved as quickly as possible to limit the impacts to sailors,” Knight said.

US NAVY SET TO BOOT SAILORS WHO REFUSE COVID VACCINE

He declined to provide details to the outlet on how many sailors are affected by the delays. 

Gonzalez said that one sailor was not paid for three months due to an enlistment extension and pay error, and was forced to use up savings. Navy-Marine Corps Relief sent the sailor $2,500 to the sailor at home due to them being under COVID-19 quarantine.

Other sailors have spoken out about the issues on social media. One sailor posted on Reddit that she and her husband were married in July but had not received basic allowance for housing in the Washington, D.C., area. They took out commercial loans as a temporary fix, according to the post reported by Military.com. 

U.S. Navy sailors (Credit: iStock)

U.S. Navy sailors (Credit: iStock)
(iStock)

ARMY OFFICER RESIGNS OVER BIDEN VACCINE MANDATE, ‘MARXIST TAKEOVER OF THE MILITARY’

“My case has been open for over a month with NO action … I am just … Beyond frustrated,” the sailor wrote.

A personnel specialist first class told Military.com that the problem comes down to the consolidation of personnel support and customer support detachments that began in 2017. 

“Shutting down dozens of processing centers took that transaction load and dropped it in one building’s worth of people,” the anonymous petty officer told Military.com. “Our only means of communication with them is through [MyNavy Career Center, or MNCC], which isn’t always great because it’s [mostly] civilians with a knowledge database … all they can do is look up tickets and give a status.”

WASHINGTON, DC - SEPTEMBER 17: Members of the Navy Ceremonial Guard stand for the national anthem during a ceremony for National POW/MIA Recognition Day, at the U.S. Navy Memorial on September 17, 2021 in Washington, DC. The ceremony honored all military personnel who were prisoners of war or who are still missing in action. (Photo by Kevin Dietsch/Getty Images)

WASHINGTON, DC – SEPTEMBER 17: Members of the Navy Ceremonial Guard stand for the national anthem during a ceremony for National POW/MIA Recognition Day, at the U.S. Navy Memorial on September 17, 2021 in Washington, DC. The ceremony honored all military personnel who were prisoners of war or who are still missing in action. (Photo by Kevin Dietsch/Getty Images)
(Kevin Dietsch)

The petty officer added that the 30-day timeline is “laughable” due to personnel specialists working on a sailor’s pay package and sending it to a processing system that has 30 days to work on it. The system then typically takes another 30 days to process, which is followed by another 30 to 45 days for review. 

CLICK HERE TO GET THE FOX NEWS APP

“In a Hershey and Hallmark world, 30 days would be great,” he told Military.com.