Best emergency loans of 2021

Our goal here at Credible Operations, Inc., NMLS Number 1681276, referred to as “Credible” below, is to give you the tools and confidence you need to improve your finances. Although we do promote products from our partner lenders who compensate us for our services, all opinions are our own.

Emergency loans are typically unsecured personal loans that you can apply for and receive within a few business days.  (iStock)

When you’re facing a financial emergency, a personal loan can help you get the cash you need quickly. Whether you need to fix water damage from a flooded dishwasher or pay an urgent bill, an emergency loan with fast funding may be a great option. This article covers the best emergency loans, how quickly you can get them and how they affect your credit.

With Credible, you can easily compare personal loan rates to find the best emergency loan for you.

What are emergency loans?

An emergency loan is an unsecured personal loan that you can get quickly to cover unexpected expenses. Unsecured loans don’t require collateral, meaning your property won’t be at risk if you fail to make your payments. Personal loans are typically paid back with fixed interest rates, so your monthly payment will stay the same for the life of the loan. While interest rates may be higher than those for secured loans, like a home equity loan, they’re generally lower than what you’d pay on a credit card. And you typically don’t have to pay a prepayment penalty if you repay the loan ahead of schedule.

You can get an emergency loan from banks, credit unions and online lenders. After accepting an emergency loan, the loan funds are typically deposited directly into your bank account. If your loan has an origination fee, it’ll be deducted from the total loan amount you receive.

Best emergency loans 

The following 11 Credible partner lenders offer emergency loans.

Avant: Best for bad credit borrowers

You can get a personal loan with Avant even if your credit score isn’t great, but be aware that the lender charges some fees.

Axos: Best for good credit borrowers

Axos Bank has a fast application process, but you’ll need good credit to qualify for a loan.

  • Loan amounts: $5,000 to $50,000
  • Loan terms (years): 3 to 6
  • Minimum credit score: 700
  • Time to fund: Within 2 days
  • Fees: Does not disclose

Best Egg: Best for larger loans

Best Egg offers both unsecured and secured personal loans of up to $50,000.

  • Loan amounts: $2,000 to $50,000
  • Loan terms (years): 3 or 5
  • Minimum credit score: 600
  • Time to fund: 1 to 3 business days
  • Fees: Origination fee of 0.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 5.99{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}; late payment

Discover: Best for longer repayment terms

Discover offers loan terms of up to seven years, which is ideal if you need more time to repay your loan.

  • Loan amounts: $2,500 to $35,000
  • Loan terms (years): 3 to 7
  • Minimum credit score: 660
  • Time to fund: As soon as the next business day
  • Fees: Late payment

LendingPoint: Best for fair credit borrowers

LendingPoint has a simple online application and can offer you a rate quote with no effect on your credit score — even if you only have fair credit.

  • Loan amounts: $2,000 to $36,500
  • Loan terms (years): 2 to 5
  • Minimum credit score: 580
  • Time to fund: As soon as the next business day
  • Fees: Origination fee of up to 6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

LightStream: Best for same-day funding

LightStream may be able to fund your loan as soon as the same day you’re approved, making it a good option if you’re in a tight spot.

  • Loan amounts: $5,000 to $100,000
  • Loan terms (years): 3 to 6
  • Minimum credit score: 660
  • Time to fund: As soon as the same day
  • Fees: None

OneMain Financial: Best for borrowers without credit

With no credit score requirement, OneMain Financial might be a good option for people with little to no credit history.

  • Loan amounts: $1,500 to $20,000
  • Loan terms (years): 2 to 5
  • Minimum credit score: None
  • Time to fund: As soon as the next business day
  • Fees: Origination fee (flat fee of $25 to $500 or 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of loan amount); late payment; insufficient funds

Prosper: Best for joint borrowing

If you don’t qualify for a personal loan on your own, Prosper allows you to apply with a cosigner with better credit. This might also improve your rate.

  • Loan amounts: $2,000 to $40,000
  • Loan terms (years): 3 or 5
  • Minimum credit score: 640
  • Time to fund: As soon as the next business day
  • Fees: Origination fee of 2.41{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Universal Credit: Best for small loans

Universal Credit has a minimum loan amount of just $1,000, making it a good option if you only need a small loan to cover an emergency.

  • Loan amounts: $1,000 to $50,000
  • Loan terms (years): 3 to 5
  • Minimum credit score: 560
  • Time to fund: Within 1 business day
  • Fees: Origination fee of 4.25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}; late payment

Upgrade: Best for building credit

Upgrade is a great option if you’re working on building credit — the lender has a low minimum credit score requirement and offers free credit monitoring. 

  • Loan amounts: $1,000 to $50,000
  • Loan terms (years): 2 to 7
  • Minimum credit score: 560
  • Time to fund: Within 1 day
  • Fees: Origination fee of 2.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}; late payment

Upstart: Best for early repayment

Upstart doesn’t charge a prepayment penalty and offers fast funding.

  • Loan amounts: $1,000 to $50,000
  • Loan terms (years): 3 or 5
  • Minimum credit score: 580
  • Time to fund: As soon as the next business day
  • Fees: Origination

Use Credible to compare personal loan rates from multiple lenders.

Other personal loan lenders to consider

The following three lenders are not Credible partners, so you won’t be able to easily compare your rates with them on the Credible platform. But they may also be worth considering if you’re looking for an emergency loan. 

Figure

Figure says you can be approved for one of its loans in minutes. 

  • Loan amounts: $5,000 to $50,000
  • Loan terms (years): 3 or 5
  • Minimum credit score: 680
  • Time to fund: Within 1 to 2 business days
  • Fees: Origination fee of up to 3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Rocket Loans

Rocket Loans says its technology can give you a pre-approval decision in seconds, and you can get your loan funds as soon as the same day you accept the loan.

  • Loan amounts: $2,000 to $45,000
  • Loan terms (years): 3 or 5
  • Minimum credit score: Does not disclose
  • Time to fund: As soon as the same day
  • Fees: Origination fee of 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}; late payment; insufficient funds

Wells Fargo

With Wells Fargo, you may be able to get your loan funds as soon as the same day, and you can get a discount if you have a checking account with the bank and make automatic payments from it.

  • Loan amounts: $3,000 to $100,000
  • Loan terms (years): 1 to 7
  • Minimum credit score: Does not disclose
  • Time to fund: As soon as the same day
  • Fees: Late; insufficient funds

Methodology

Credible evaluated the best emergency loan lenders based on factors such as customer experience, minimum fixed rate, maximum loan amount, funding time, loan terms and fees. Credible’s team of experts gathered information from each lender’s website, customer service department and via email support. Each data point was verified to make sure it was up-to-date.

How fast can I get an emergency loan? 

This varies by lender, but in many cases you can receive your money as soon as the next business day if you qualify for the loan after a credit check. Some personal loan lenders can even fund the loan on the same day. But you’ll need to move quickly to send in all required documentation of your income and assets and sign the paperwork required to accept the loan.

Before applying for a personal loan, you may want to check your credit report and credit score to make sure everything is in order. Errors on your application may affect your loan approval. 

How to get an emergency loan with bad credit

If you have bad credit, it can be more difficult to get an emergency loan. Most personal loan lenders have minimum credit score requirements. But you’re not necessarily out of options if you have bad credit. Here are a few:

Will emergency loans affect my credit score?

You can typically shop for an emergency loan without affecting your credit score. Most lenders will prequalify you for a loan using only a soft pull, which doesn’t harm your credit. Once you fully apply for the loan, your credit score will take a small hit — usually around five points for a short period of time.

Making on-time payments on your loan will boost your score, likely outweighing the temporary negative effect of applying for a loan.

Check out Credible to compare personal loan rates from various lenders in minutes.

How much money should I have in an emergency fund?

An emergency fund is cash that you set aside in a checking or savings account to pay for unexpected expenses. If you can afford to have one, this is a better alternative than taking out an emergency loan. Ideally, your emergency fund should be large enough to cover three to six months’ worth of your household’s typical living expenses. But even having $1,000 on hand could make a big difference.

Having an emergency fund will help you be better prepared when a financial emergency arises. About 60{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of families will face such a situation each year, according to the Federal Emergency Management Agency. Unfortunately, one-third of Americans don’t have money set aside and nearly half would struggle to meet an unexpected $400 expense.

Are there emergency loan alternatives? 

You have options beyond a personal loan to meet a financial emergency. Here are a few alternatives:

93{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of payday loan borrowers regret taking out their loans, survey finds

Payday financial loans can be a debt entice for borrowers who are not able to find the money for to make payments. This is how you can repay your payday mortgage equilibrium prior to it can be sent to credit card debt collectors.  (iStock)

Payday loan providers prey on borrowers with lousy credit who desperately have to have cash, trapping them in a cycle of higher-fascination credit card debt that is challenging to repay. 

The wide the greater part (93{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}) of debtors regret using out their payday financial loan, in accordance to a new survey from DebtHammer. Just 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of respondents explained their monetary situations improved after borrowing a payday bank loan, even though 84{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} claimed they were worse off.

Payday financial loans give individuals an avenue to borrow modest, short-expression dollars financial loans with out a credit score look at. But the common repayment time period is just two months, which potential customers 4 in 5 borrowers to borrow a new payday personal loan to repay their present personal debt, the Shopper Monetary Protection Bureau (CFPB) documented.

It’s attainable to get out of payday bank loan debt without the need of renewing your personal loan and incurring extra expenses. Retain looking at to master how to crack the cycle of payday bank loan borrowing, these types of as consolidating personal debt with a individual loan. You can assess fees on credit card debt consolidation loans for free of charge on Credible with no impacting your credit score score. 

Best Quick-Expression Financial loans: Evaluate YOUR Alternatives

3 ways to get out of a payday loan

The average value of a payday personal loan is equivalent to an once-a-year proportion level (APR) of nearly 400{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} — in other text, borrowers who preserve rolling above their payday loans could pay back 4x the amount of money they originally borrowed around the study course of a calendar year.

Payday creditors may well have you think that rolling above your mortgage is the only way to fork out off your personal debt, but that’s not the scenario. Right here are a few choice methods to crack the payday loan cycle:

  1. Personal debt consolidation financial loans
  2. Prolonged payment programs
  3. Credit counseling

Read about every reimbursement prepare in the sections beneath.

3 Things YOU Should Hardly ever DO WITH YOUR Unexpected emergency FUND

1. Financial debt consolidation loans

Individual financial loans are lump-sum loans that are usually made use of to consolidate additional substantial-fascination financial debt, such as payday financial loan personal debt. They appear with preset interest charges and compensation terms, which suggests that your every month payments will be the exact same while you repay your debt.

These credit card debt consolidation financial loans are commonly unsecured, which indicates that you you should not have to set up an asset as collateral. Because they are unsecured, lenders ascertain your fascination price and eligibility dependent on your credit score score and personal debt-to-profits ratio. 

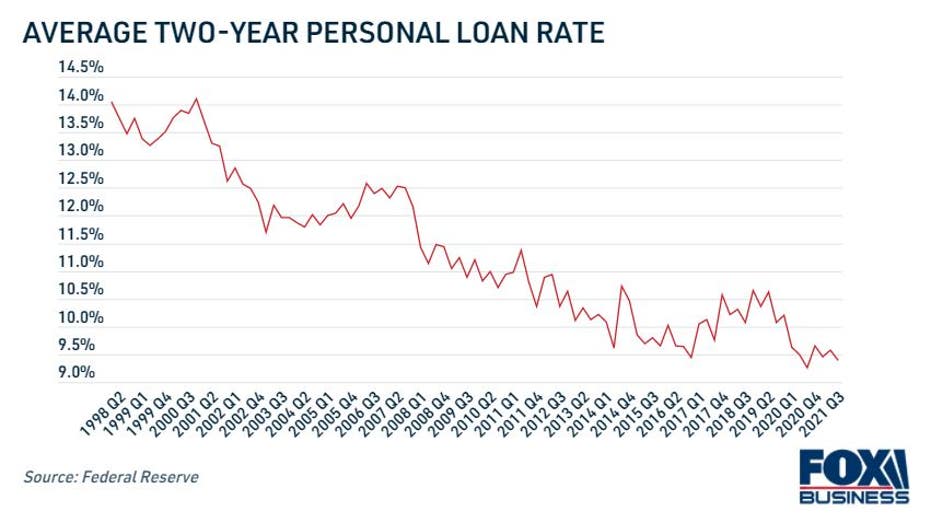
Properly-certified borrowers may well qualify for a minimal rate on a particular personal loan for debt consolidation. Own bank loan premiums are in close proximity to all-time lows, according to the Federal Reserve, averaging 9.39{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in Q3 2021.

Some credit history unions also present smaller payday substitute loans (Buddies), which let users to borrow up to $2,000 with an curiosity fee cap of 28{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. Nonetheless, these loans can be tricky to uncover given that just a tiny part of credit score unions offer you Pals. 

You can see if you qualify for a personal debt consolidation financial loan on Credible with a delicate credit score inquiry, which will not affect your credit score. Use a personalized financial loan calculator to estimate your month to month payments to see if this selection can aid you get out of payday mortgage debt.

Credit score CARD Desire Rates SPIKE TO In the vicinity of ALL-TIME Higher, FED Facts Exhibits

2. Extended payment designs

An prolonged payment system (EPP) lets payday financial loan borrowers repay their credit card debt about a for a longer time time than the usual two-7 days repayment expression. Quite a few states need payday creditors to supply EPPs, so you can have to analysis your state legal guidelines to see if you’re eligible.

Some payday lenders may perhaps offer you EPPs irrespective of regardless of whether they are required to do so by regulation. Creditors belonging to the Neighborhood Monetary Providers Affiliation of The usa (CFSA) are essential to present EPPs to borrowers, but other money establishments may not provide this alternative.

HOW Long DO Negative Merchandise Stay ON YOUR Credit history REPORT?

3. Credit score counseling

Nonprofit credit history counseling agencies give free or low-expense expert services for borrowers who are battling to deal with their financial debt. One particular of these expert services features enrolling payday personal loan borrowers in a credit card debt administration system (DMP).

Below a DMP, a credit score counselor will enable you build a finances and debt compensation program. Credit counselors may perhaps be equipped to assistance you negotiate with payday loan companies to lock in a lower fascination price or lower the bank loan amount.

You can see a whole listing of certified nonprofit credit counselors on the Division of Justice web-site. If you however have questions about payday bank loan debt aid, study far more about financial debt consolidation by getting in touch with a knowledgeable financial loan officer on Credible.

Debtors WHO CONSOLIDATE Credit score CARD Personal debt CAN Conserve $2K+ ON Typical, Information Displays

Have a finance-relevant problem, but you should not know who to check with? E mail The Credible Revenue Specialist at moneyexpert@credible.com and your concern could be answered by Credible in our Money Pro column.

The Last-Ditch Pressure Campaign to Cancel Student Loans

As the White Dwelling sweats in excess of the soaring price of milk, bread and fuel, tens of tens of millions of Us residents are bracing for an even greater strike to their budgets on the horizon: the return of pupil bank loan financial debt.

That is, except the administration moves to terminate individuals money owed first.

Payments on federal college student loans have been paused and interest charges set to percent due to the fact passage of the CARES Act in March 2020. Following repeated extensions, they have been set to resume in September 2021, but a remaining extension permitted the pause to continue by means of January 2022. That’s been a spectacular fiscal reduction for the virtually 45 million individuals with student loans who keep a lot more than $1.7 trillion in fantastic student credit card debt nationwide.

But come February, payments are established to restart. And activists hope there’s enough time remaining to mount a stress campaign on the administration to cancel university student financial debt before payments resume.

Organizers argue that soon after more than a year without the need of payments, folks “have gotten so employed to federal student loans staying paused” and anxiety their bank loan payments will consume away at newly attained rewards like the little one tax credit history, explained Braxton Brewington, push secretary of The Financial debt Collective.

“I just can’t think about what January will glimpse like 30 times out when people today are, like, ‘OK, I’ve gotten 12 emails from the Section of Education… This simply cannot truly be happening,’” he added.

The Scholar Personal debt Crisis Center’s executive director Cody Hounanian informed The Every day Beast that a lack of student mortgage payments has authorized individuals to “fully participate in the financial state, which could not be a lot more important appropriate now as we’re trying to get better the country from the pandemic.”

“We’ve listened to from debtors who, for the 1st time ever, have been able to acquire a home. We’ve listened to from debtors who, for the initially time at any time, could invest in a car or truck to get them to work… It is been a advantage to their family members. It is been a profit to their communities,” Hounanian remarked.

Each groups say they’ve been arranging to attempt and drive lawmakers towards progress on university student debt cancellation just before payments switch again on. Some of Congress’s most outspoken Democrats are by now on board, contacting on Biden to get action by executive electrical power ASAP.

“As we continue recovering from this pandemic, people want enable. Passing the Make Again Greater Act is a significant step but there is even now a lot more to do. It is time to terminate at least $50,000 of student financial debt for every borrower and get folks the relief they will need,” Congressional Progressive Caucus Chair Pramila Jayapal (D-WA) tweeted last 7 days.

And even though the $50,000 aid amount has highly effective backers like Jayapal, Senate Bulk Leader Chuck Schumer (D-NY), and Sen. Elizabeth Warren (D-MA), the White Residence has held firm at the $10,000 for each borrower total Biden promised for the duration of the marketing campaign. Additionally, the administration has managed extending the pause of the debt as a result of govt motion was about as much as his powers on the difficulty could go.

“On day 1, the first working day of his administration, he directed the Department of Education to extend the existing pause on pupil mortgage payments and interest for tens of millions of Us citizens with federal scholar loans,” White Property push secretary Jen Psaki reported in February. “That was a stage he took by way of govt action, but he undoubtedly supports attempts by users in Congress to choose supplemental measures, and he would search ahead to signing it.”

Biden explained before this year that he doesn’t feel he can unilaterally cancel excellent scholar loans and asked for a memo from the Office of Training in spring on what authorized authorities he has on the issue.

That April 5 memo was later acquired by The Credit card debt Collective through a community data request but only the subject of the missive—“The Secretary’s Lawful Authority for Broad-Centered Financial debt Cancellation”—was seen. The relaxation of the memo has been closely redacted, leaving just about no substance visible to the public.

Nevertheless, other customers argue cutbacks to the Establish Again Far better Act serve as justification for pushing the administration to cancel remarkable college student financial loans.

Rep. Alexandria Ocasio-Cortez (D-NY) wrote in an Instagram story on Oct. 28 that provided the paring-again of the Construct Back Far better Act, there is “more option than ever to deliver the warmth on Biden to terminate scholar financial loans.”

“He doesn’t require [Sen. Joe Manchin’s (D-WV)] authorization for that and now that his agenda is thinly sliced he requires to phase up his govt motion sport and exhibit his determination to provide for persons,” she added.

Biden’s social paying out deal, which handed the Property on Nov. 19, unsuccessful to incorporate a system to deal with student loans—and removed a provision to make neighborhood university totally free.

The American Civil Liberty Union informed The Everyday Beast that although the Biden administration “hasn’t finished more than enough to deliver relief to the tens of millions of People who are burdened by the pupil financial debt disaster,” canceling $50,000 could be a indicates to slim the racial wealth gap, with college student financial loans disproportionately impacting Black and Latino communities.

The ACLU is working a petition drive for canceling $50,000 in scholar credit card debt per borrower, which now boasts about 36,000 signatures.

Campaign arms for Schumer, Reps. Ayanna Pressley (D-MA) and Jayapal, in addition to teams like the ACLU, in just the final number of months have launched compensated advert strategies on social media linked to college student financial debt cancelation aimed at growing general public strain for motion on the concern.

“If President Biden and his Administration can pause university student loans, they can cancel them — and there’s hardly ever been a far more crucial time for daring motion,” a November advert from Pressley’s workforce reads.

Dwelling Speaker Nancy Pelosi has also insisted that canceling university student credit card debt would need to have to be carried out through laws, which would likely quantity to gridlock amid Congress’ narrowly divided parties.

“People assume that the President of the United States has the power for financial debt forgiveness. He does not. He can postpone. He can hold off. But he does not have that energy,” Pelosi mentioned in excess of the summer time.

Even now, the administration cites some development on student financial debt this year through the Public Services Financial loan Forgiveness Plan, which was established by Congress in 2007 to entice graduates into community provider roles like instructing or law enforcement in trade for possessing their college debts repaid soon after 10 yrs of get the job done.

But the application had been plagued by unscrupulous procedures and normally substantial rejection rates for candidates. In Oct, the administration introduced a series of patchwork fixes that advocates applauded.

The Biden administration also issued a number of rounds of forgiveness for college students defrauded by for-financial gain educational institutions like ITT Tech and Corinthian Faculties, in addition to announcing that 323,000 folks on file for a disability with the Social Safety Administration will have their university student debt canceled, way too.

American Federation of Instructors president Randi Weingarten advised The Daily Beast that she’s found firsthand how persons respond when their owed student credit card debt drops to zero by means of federal systems.

“The pleasure and the aid is palpable,” she stated.

But Weingarten, an additional advocate for canceling up to $50,000 in scholar personal debt, mentioned that with public provider loan forgiveness, Biden was inheriting a damaged software. Wide university student debt cancellation would be a new method entirely. “As a lot as I consider it really is significant to do, you know, it can be a large coverage final decision,” she explained.

Weingarten prompt that building a program for forgiving all Americans’ university student financial debt would be a well timed undertaking—and would not very likely amount of money to fast gratification for borrowers.

“I feel that there would have to be some expectations set… They’d have to consider some time in generating absolutely sure that this was accomplished the suitable way,” she claimed. Weingarten suspects urgency is only heading to build around the broader situation of student debt as the February cliff nears.

And among the these activists calling for $50,000 in cancellation are nonetheless some contacting for the administration to terminate it all.

Brewington says The Financial debt Collective is between them, telling The Daily Beast, “We will never occur down from significantly less than all of it…. All those numbers are arbitrary and do not seriously signify something.”

Goldman Sachs and other top US banking institutions to consider Bitcoin-backed loans

  • Wall Road banks are on the lookout to seem into using the flagship cryptocurrency as collateral for institutional money financial loans.
  • Attainable groundwork for additional built-in electronic asset primary brokerage services in the upcoming.
  • Top rated-tier financial institutions continue to prefer crypto-relevant goods like futures somewhat than location Bitcoin.

Different top rated-tier banking institutions in the United States are wanting to take Bitcoin as collateral for financial loans. Goldman Sachs and other Wall Road financial institutions may well not dabble in place cryptocurrency marketplaces but could take into account artificial crypto products which includes futures.

Leading banks check out using Bitcoin for loans

Goldman Sachs and other top-tier banking institutions in the US are checking out the plan of taking the world’s greatest cryptocurrency by sector capitalization for loans. According to a new report by CoinDesk, these financial institutions are in search of to do institutional funds financial loans with Bitcoin as collateral.

On the other hand, most banking institutions are not thinking about the custody of spot Bitcoin to make the loans but will consider other crypto-related items such as futures. 

The Wall Avenue banks are searching to emulate a few bash repo-style preparations, which is a way of borrowing resources by promoting securities with an arrangement to repurchase them making use of a third-occasion agent. 

In accordance to numerous resources, it is an opportunity that lays the basis for more built-in electronic asset prime brokerage products and services in the potential. A supply even further said that Goldman Sachs is performing on finding lending from collateral and the tri-social gathering repo approved.

An additional supply mentioned that some financial institutions could use a 3rd social gathering to create the mortgage, and other folks may well opt for to use their own harmony sheet. The source included that fifty percent a dozen of huge banking institutions have been speaking about Bitcoin-backed loans, and some of them are “in the future 3 to six months category”.

Coinbase and Fidelity Digital Property ended up shown as the probable custodians the banking institutions were being in discussions with. The Place of work of the Comptroller of the Forex (OCC) permitted US banking companies and cost savings associations to custody cryptocurrency for their consumers considering that past year. The Federal Deposit Coverage Company (FDIC) chairman even more said that US regulators are on the lookout into means for classic banking companies to keep Bitcoin. 

Bitcoin price aims to reclaim $58,000

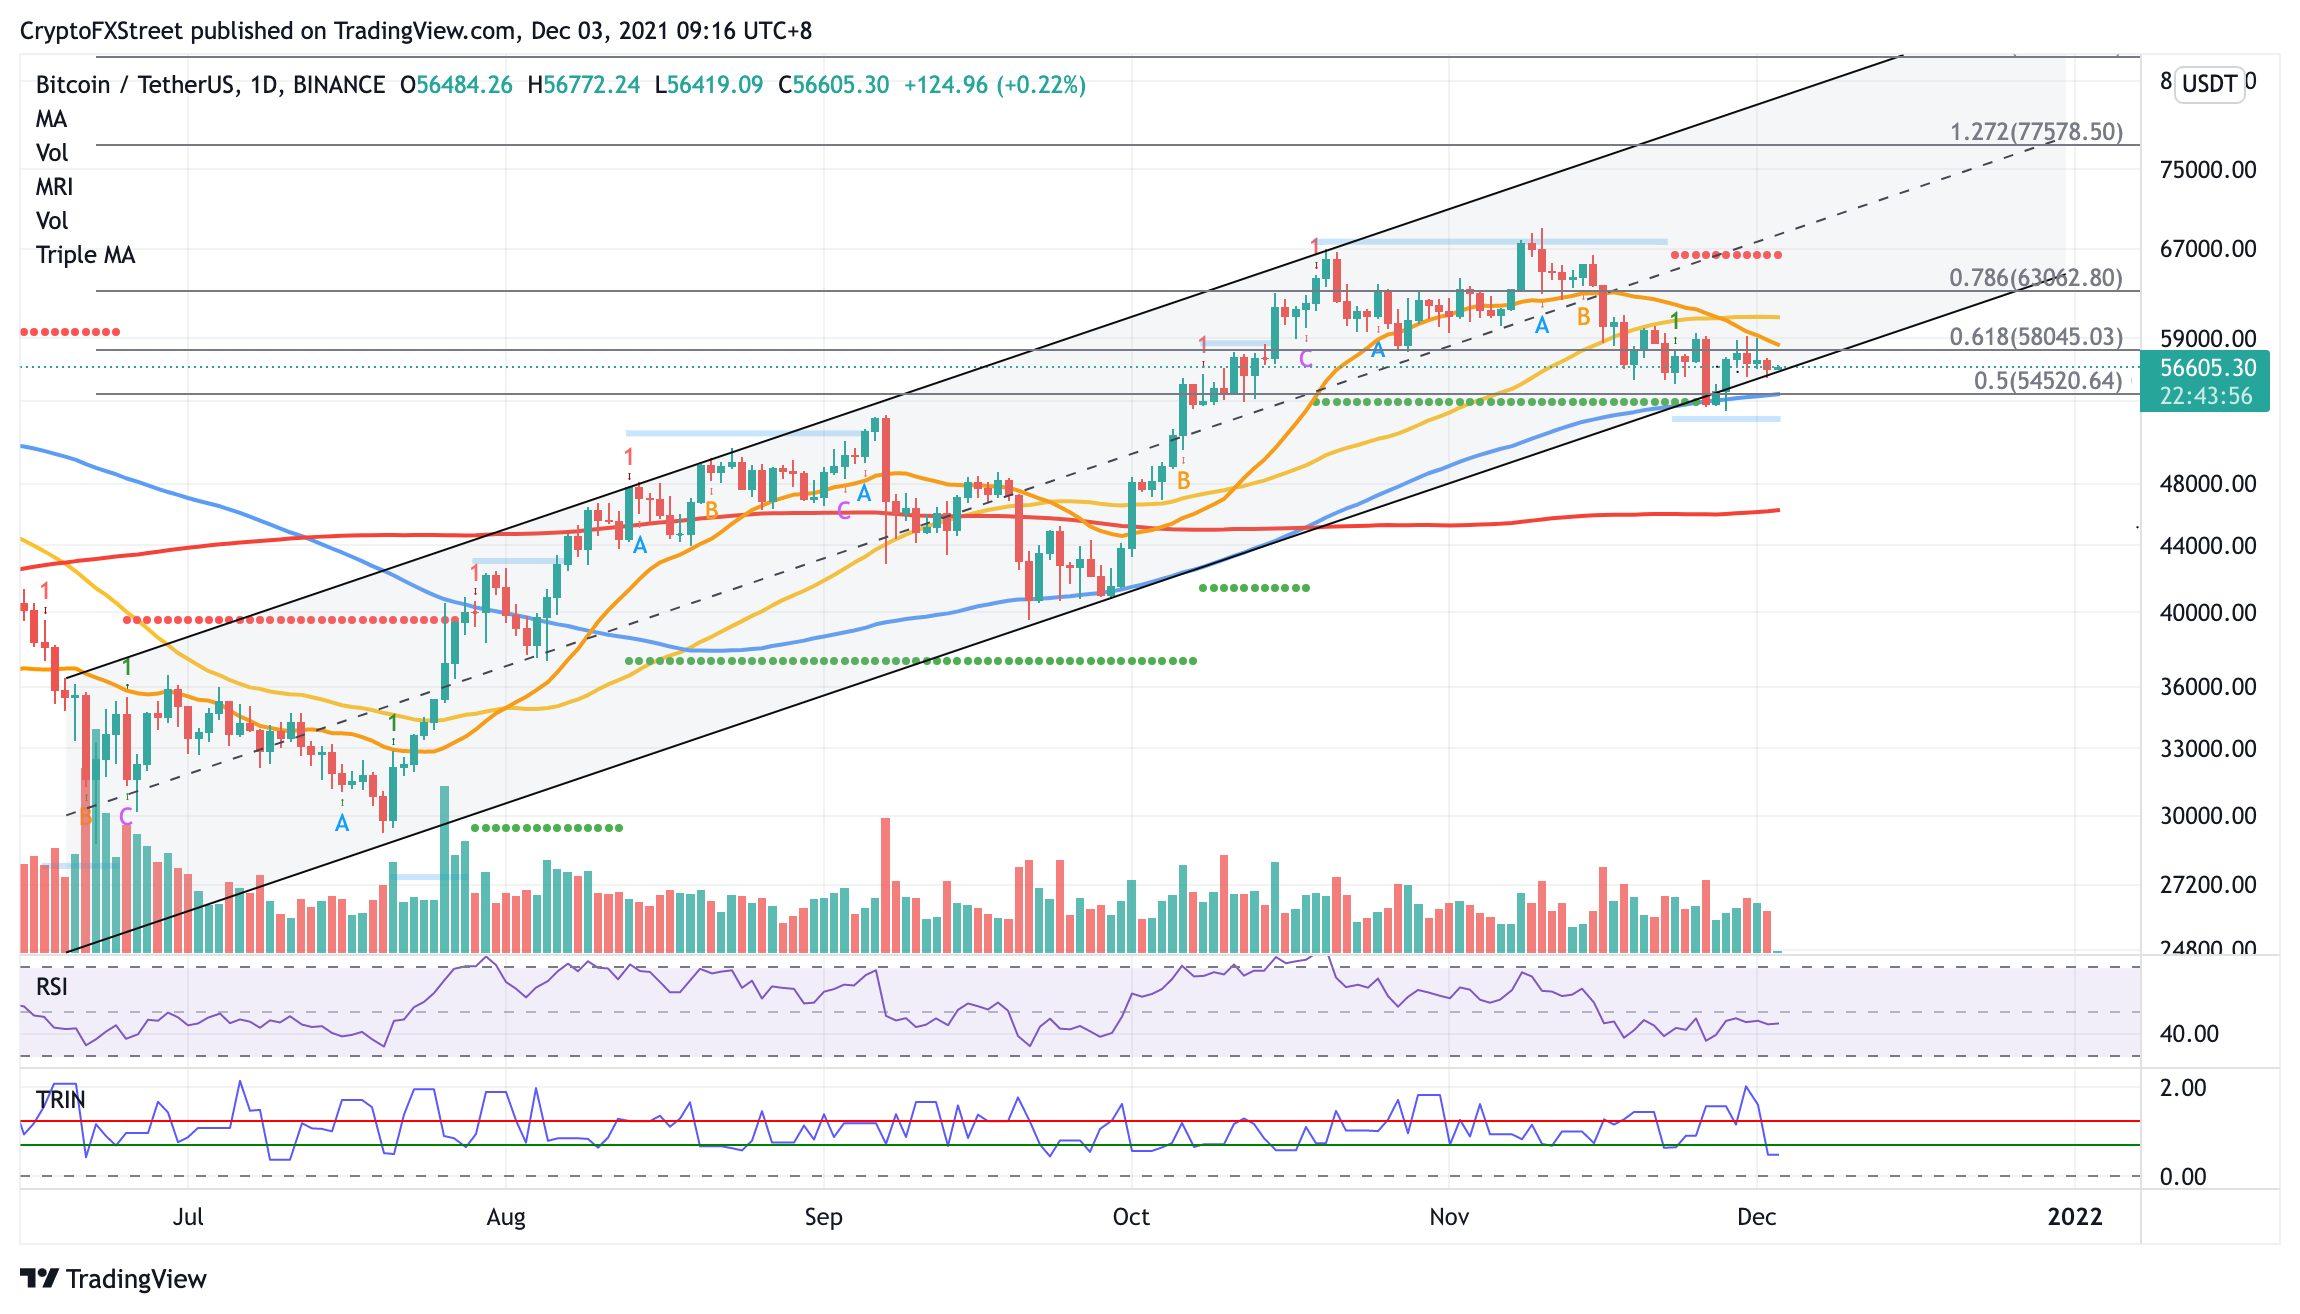
Bitcoin rate has experienced weak point as it resorts to the decreased boundary of the ascending parallel channel close to $56,401. Although this area appears to act as dependable help for BTC, the top cryptocurrency have to reclaim $58,045 to secure an uptrend.

The prevailing chart sample implies a bullish outlook for Bitcoin price, with an optimistic goal at $87,912. Even so, BTC ought to kickstart a recovery as the bears have taken more than momentarily. 

To escape the vulnerability of slipping into a downtrend, the bellwether cryptocurrency ought to purpose to tag the upcoming spot of resistance at the 61.8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} Fibonacci retracement degree at $58,045, coinciding with the 21-day Straightforward Relocating Regular (SMA).

BTCUSDT

BTC/USDT day by day chart

The following hurdle appears at the 50-day SMA at $60,836, then at the 78.6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} Fibonacci retracement amount at $63,062.

The 1st line of protection for Bitcoin selling price is at the reduce boundary of the governing specialized pattern at $56,401. If BTC fails to maintain earlier mentioned this vital place of assistance, it could fall additional to uncover the 50{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} retracement amount at $54,520, corresponding to the 100-working day SMA.

Disclaimer: FXStreet has achieved out to Goldman Sachs to get an official statement about the current developments, but the lender has nevertheless to answer. 


Syracuse unveils new loan program for small city businesses. (Some loans will be forgiven)

Syracuse, N.Y. – Modest business enterprise owners in Syracuse can apply for very low-interest loans starting currently under a $1 million program managed by the metropolis of Syracuse’s economic improvement arm.

The revenue could go rapid. Programs ought to be submitted to the Syracuse Economic Progress Corp. by no later than Dec. 31, Mayor Ben Walsh stated. Walsh is asserting the system at a news conference this early morning.

There are 3 types of financial loans centered on the sizing and form of enterprise. Financial loans for the smallest organizations – ‘’micro-enterprises’’ with 10 or fewer personnel – are forgivable under selected conditions. The loans can be applied for a broad wide variety of uses such as money upgrades, acquire of materials and stock and more.

In this article are 3 basic types:

Micro-company Fund: Financial loans of up to $5,000 are available at an interest charge of 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, repayable in two many years. The financial loans can be forgiven if the company retains its workforce, stays current on home taxes and satisfies other circumstances. To qualify, a company ought to have 10 or less workers.

Modest Organization Aid Fund: These financial loans of up to $25,000 are for enterprises that have 50 or fewer workforce and professional a decrease in sales during 2020 or 2021 or are positioned within just an eligible Census tract (see map). The fascination amount is 1.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, repayable in 5 decades.

Neighborhood Effects Fund: Organizations, nonprofit businesses, or enhancement entities with 50 or fewer staff members can implement for up to $200,000 for creating renovations or other authentic estate improvements inside a skilled Census tract. The interest rate is 2{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for 15 several years.

ARPA tracts

The spots outlined in black are Census tracts eligible for exclusive guidance below the federal American Rescue Strategy Act. Some actual estate advancement jobs in these parts are are suitable for SEDCO financial loans.

The Syracuse Financial Progress Corp., or SEDCO, is a regional enhancement company established by the metropolis. To utilize for a loan, business proprietors should finish a two-phase course of action:

1st, fill out an on the internet questionnaire at the SEDCO site. Then, a metropolis consultant will get hold of the small business to present an application variety for the ideal bank loan fund. Applications and supporting paperwork have to be submitted by noon Dec. 31.

Cash for the loans arrives from the $123 million Syracuse been given this year in federal stimulus money.

Between SEDCO and the Syracuse Industrial Improvement Agency, metropolis officials had previously offered $1.3 million in grants and financial loans to businesses recovering from the Covid-19 pandemic.

LendingClub Auto Refinance Loans Now Cover 94 Percent of U.S. Population

Borrowers Help you save an Typical of $4,000 Around the Existence of the Bank loan

Enterprise Continues to Create Holistic Buyer Working experience Throughout its Client Items to Deliver Added Price for Members

SAN FRANCISCO, Nov. 30, 2021 /PRNewswire/ — LendingClub Corporation (NYSE: LC), the dad or mum organization of LendingClub Bank, America’s foremost electronic market lender, now introduced that its car refinance financial loans are now readily available in 40 states, covering 94 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the U.S. populace, and debtors have saved an average of $4,000 over the everyday living of the personal loan. The product was 1st introduced in California in 2016.

LendingClub Corporation (NYSE: LC) is the parent company of LendingClub Bank, National Association, Member FDIC. LendingClub Bank is the leading digital marketplace bank in the U.S.

LendingClub Company (NYSE: LC) is the guardian company of LendingClub Financial institution, National Affiliation, Member FDIC. LendingClub Financial institution is the major digital market financial institution in the U.S.

Auto loans depict the fourth-maximum share of U.S. residence credit card debt, after mortgage loan credit card debt, residence equity line of credit score, and scholar loan credit card debt, with Us citizens owing far more than $1 trillion on their automobile loans. Almost two-thirds of LendingClub’s members at the moment maintain an car financial loan and it is normally their next maximum regular financial debt outside the house of housing prices. The average APR for borrowers on car refinance loans by way of LendingClub Lender are just about 5 p.c reduced than their past loans. This interprets into an average discounts of much more than $4,000 more than the everyday living of the bank loan.

Right before scaling its automobile refinance offerings, LendingClub targeted its initiatives on generating a very best-in-class customer working experience that has currently set a new bar in the field. The application procedure can now be done in much less than a number of minutes and the time to comprehensive a mortgage has been lowered to a few times in contrast to numerous months for other loan providers.

“We see automobile refinance loans as an great prospect for our 3.8 million associates and for LendingClub. Who would not want to save hundreds for just a couple minutes perform?” explained Todd Denbo, SVP of Auto at LendingClub Financial institution. “Now that we have transformed the approach for refinancing an auto financial loan and can market financial loans through our market as well as maintain financial loans on our equilibrium sheet, we’re scaling the product. Auto is a crucial stage in our vision to generate a holistic shopper working experience that seamlessly integrates saving prospects for our customers throughout our product choices.”

LendingClub put in 15 decades building the nation’s main personal financial loans enterprise – collecting deep knowledge insights, dialing in the purchaser working experience, improving upon credit rating products, building field associations, improving manage and compliance abilities, and additional. As a digital market lender with the capability to each hold loans on its harmony sheet and provide loans on the marketplace, LendingClub Bank can now bring extra of this skills to other economical ache factors that its associates experience, these types of as refinancing vehicle financial loans.

Unlike new entrants, LendingClub’s automobile refinance items are educated by the billions of dollars in personalized financial loans to tens of millions of buyers through a range of credit score situations, enhanced by arduous testing and ensuing in 150+ billion information cells added to its proprietary databases. This prosperous details set has guided LendingClub’s predictive science and credit rating decisioning algorithms to outperform the sector. For case in point, delinquency fees are much more than 35 percent greater than the normal for its private financial loan business.

In addition to the extraordinary chances for customers, LendingClub has also designed a persuasive situation for its marketplace buyers to finance these vehicle refinance financial loans. Vehicle loans ended up the leading accomplishing asset by means of the 2008 recession and their sturdiness was apparent once again in the course of the pandemic. LendingClub has also more than-shipped on credit history general performance for its buyers. The mixture of the resiliency of automobile financial loans through small business cycles and our sturdy mortgage performance has pushed trader desire for our car refinance financial loans.

To make it effortless for debtors to do the job out how much they can save, LendingClub has also produced an vehicle refinance calculator: https://www.lendingclub.com/loans/vehicle-refinancing/refinance-calculator

Much more details about Vehicle Mortgage Refinancing by LendingClub is offered right here.

About LendingClub

LendingClub Company (NYSE: LC) is the father or mother organization of LendingClub Financial institution, Countrywide Association, Member FDIC. LendingClub Bank is the major electronic marketplace financial institution in the U.S., where by members can accessibility a broad assortment of fiscal products and solutions and expert services built to aid them pay out considerably less when borrowing and make far more when conserving. Centered on a lot more than 150 billion cells of details and above $68 billion in loans, our AI-driven credit history decisioning and equipment-mastering styles are utilized across the consumer lifecycle to grow seamless entry to credit for our users, though making persuasive danger-modified returns for our loan investors. Because 2007, additional than 3.8 million associates have joined the Club to aid achieve their financial targets. For a lot more information and facts about LendingClub, stop by https://www.lendingclub.com.

Protected Harbor Assertion

Some of the statements above, which include statements regarding the projected performance, expansion, borrower discounts, resiliency and marketplace investor demand from customers with regard to LendingClub’s vehicle refinance solution, are “forward-seeking statements.” The terms “foresee,” “believe,” “estimate,” “hope,” “intend,” “may well,” “outlook,” “strategy,” “forecast,” “task,” “will,” “would” and similar expressions might determine forward-looking statements, even though not all forward-hunting statements incorporate these identifying words. Elements that could result in genuine results to vary materially from those contemplated by these ahead-seeking statements contain individuals elements established forth in the portion titled “Risk Components” in LendingClub’s most modern Yearly Report on Type 10-K and Quarterly Report on Form 10-Q, every single as submitted with the Securities and Trade Fee, as nicely as in LendingClub’s upcoming filings produced with the Securities and Exchange Commission. LendingClub could not truly achieve the plans, intentions or anticipations disclosed in ahead-looking statements, and you should really not place undue reliance on ahead-looking statements. Real outcomes or functions could vary materially from the programs, intentions and anticipations disclosed in ahead-searching statements. LendingClub does not assume any obligation to update any forward-searching statements, regardless of whether as a result of new information and facts, potential functions or if not, apart from as required by legislation.

Get in touch with:

For Investors: IR@lendingclub.com

Media Speak to: Press@lendingclub.com

Cision

Cision

See original material to obtain multimedia:https://www.prnewswire.com/news-releases/lendingclub-vehicle-refinance-loans-now-cover-94-per cent-of-us-inhabitants-301433800.html

Source LendingClub Company