A B2B marketplace expands for business services

A B2B marketplace expands for business services

The pandemic has solid new company alternatives as well as problems, top to quick progress in new venues for B2B ecommerce.

BrianZielinski-ShapeConnect Head Shot

Brian Zielinski, CEO, ShapeConnect

A single example is ShapeConnect, a Chicago-based on line marketplace for business enterprise companies. Started in November 2019, ShapeConnect’s activity surged the subsequent yr as buyers and sellers of solutions found new price in connecting on-line for products and services ranging from accounting and tax planning to net layout and advertising, CEO and co-founder Brian Zielinski says.

ShapeConnect, which is privately owned and self-funded, grew by more than 800{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in between 2020 and 2021, Zielinski says, as its base of 3,000 small business users improved their on the net getting and offering of providers during the pandemic.

Tom Parker, a partner with Itasca, Illinois-primarily based accounting company Fates, Bodily & Parker, suggests exposure on ShapeConnect served his agency expand amongst 25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and 30{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in 2021 over 2020. “They also linked us with distributors who deal with our social media and site advancement, and assisted us build our CRM and Hubspot referral community,” he states.

Zielisnki jobs the benefit of gross transaction quantity on ShapeConnect is on study course to reach $1 million for every thirty day period inside of two years. ShapeConnect earns its profits by charging sellers a fee of 15{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} or much less centered on transaction volume.

Marketplaces have emerged in recent decades as the quickest-rising B2B ecommerce channel, in accordance to the 2022 B2B Ecommerce Industry Report from Digital Commerce 360.

“Suddenly, marketplaces are in all places in B2B,” says Alex Moazed, CEO of Applico Inc., a electronic business advisory company. “And B2B customers are obvious they want the experience” of broad alternative among suppliers and merchandise.

Signal up for a complimentary membership to Digital Commerce 360 B2B Information, printed 4x/7 days, covering technological know-how and business trends in the expanding B2B ecommerce business. Get in touch with editor Paul Demery at [email protected] and comply with him on Twitter @pdemery.

Favourite

Barrett Business Services, Inc. to Post Q1 2022 Earnings of $1.22 Per Share, Barrington Research Forecasts (NASDAQ:BBSI)

Barrett Business Services, Inc. to Post Q1 2022 Earnings of $1.22 Per Share, Barrington Research Forecasts (NASDAQ:BBSI)

Barrett Company Solutions, Inc. (NASDAQ:BBSI – Get Score) – Equities scientists at Barrington Exploration issued their Q1 2022 earnings per share (EPS) estimates for shares of Barrett Business Companies in a exploration report issued to clients and buyers on Thursday, March 3rd. Barrington Exploration analyst V. Colicchio forecasts that the business companies service provider will write-up earnings of $1.22 per share for the quarter. Barrington Analysis also issued estimates for Barrett Small business Services’ Q2 2022 earnings at $1.16 EPS, Q3 2022 earnings at $1.59 EPS, Q4 2022 earnings at $1.49 EPS, FY2022 earnings at $5.46 EPS and FY2023 earnings at $6.06 EPS. Barrett Business enterprise Services (NASDAQ:BBSI – Get Rating) past issued its quarterly earnings knowledge on Wednesday, March 2nd. The organization expert services provider noted $1.40 earnings for each share (EPS) for the quarter, topping the Zacks’ consensus estimate of $.99 by $.41. Barrett Enterprise Solutions experienced a return on fairness of 17.53{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and a internet margin of 3.72{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. For the duration of the similar quarter in the prior calendar year, the company earned $.93 earnings per share.

BBSI has been the topic of numerous other study experiences. Zacks Financial commitment Research raised Barrett Business Providers from a “sell” ranking to a “maintain” score in a exploration observe on Monday, November 15th. Roth Money elevated their cost aim on Barrett Business Services from $96.00 to $108.00 in a study note on Thursday.

(Advert)

Governments throughout the globe want to go “All Electric” by 2035. You will find 1 rare steel that could cripple these designs. With out it, likely inexperienced is not possible. And that is why there’s a modern day-working day gold-rush for this scarce steel.

NASDAQ BBSI opened at $71.24 on Friday. The business enterprise has a 50 day uncomplicated moving common of $64.48 and a 200 day very simple moving regular of $72.24. Barrett Business enterprise Providers has a 1 year small of $57.76 and a one 12 months large of $86.82. The inventory has a industry capitalization of $534.66 million, a P/E ratio of 15.73, a P/E/G ratio of 1.01 and a beta of 1.48.

In related news, Director Vincent P. Price purchased 1,500 shares of the business’s inventory in a transaction that transpired on Friday, December 17th. The shares have been bought at an typical selling price of $66.25 per share, with a overall benefit of $99,375.00. The transaction was disclosed in a legal submitting with the Securities & Exchange Commission, which can be accessed by means of this hyperlink. 2.40{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the inventory is owned by insiders.

Institutional traders have lately modified their holdings of the stock. Confluence Wealth Services Inc. acquired a new stake in Barrett Business Services for the duration of the fourth quarter well worth $27,000. New York Condition Teachers Retirement Process bought a new stake in Barrett Enterprise Products and services in the course of the 3rd quarter value $46,000. Denali Advisors LLC purchased a new stake in Barrett Business Providers during the fourth quarter well worth $76,000. BNP Paribas Arbitrage SA lifted its holdings in Barrett Organization Solutions by 100.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} all through the third quarter. BNP Paribas Arbitrage SA now owns 2,178 shares of the business services provider’s stock well worth $166,000 just after buying an extra 1,094 shares in the course of the interval. Last but not least, Metropolitan Life Coverage Co NY lifted its holdings in Barrett Business Services by 116,250.{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} during the second quarter. Metropolitan Everyday living Insurance plan Co NY now owns 2,327 shares of the organization services provider’s inventory value $169,000 immediately after obtaining an extra 2,325 shares in the course of the interval. Institutional investors and hedge cash personal 82.40{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the company’s stock.

Barrett Business Solutions Corporation Profile (Get Rating)

Barrett Organization Providers, Inc engages in the provision of organization management answers for little and mid-sized providers. It develops administration system that integrates a know-how-based strategy from the management consulting industry with instruments from the human useful resource outsourcing industry. It focuses on skilled employer, and staffing and recruiting products and services.

See Also

This instant information inform was created by narrative science technological know-how and monetary data from MarketBeat in get to supply audience with the speediest and most exact reporting. This tale was reviewed by MarketBeat’s editorial workforce prior to publication. Be sure to mail any concerns or opinions about this story to [email protected]

Must you commit $1,000 in Barrett Company Products and services appropriate now?

Ahead of you take into account Barrett Organization Products and services, you may want to listen to this.

MarketBeat keeps monitor of Wall Street’s prime-rated and greatest undertaking study analysts and the stocks they endorse to their shoppers on a day by day basis. MarketBeat has determined the five stocks that major analysts are quietly whispering to their clients to obtain now right before the broader industry catches on… and Barrett Small business Solutions was not on the checklist.

Although Barrett Business Expert services at this time has a “Acquire” rating between analysts, best-rated analysts think these five shares are better buys.

Perspective The 5 Stocks Below


Barrett Business Services, Inc. (BBSI) CEO Gary Kramer on Q4 2021 Results – Earnings Call Transcript

Barrett Business Services, Inc. (BBSI) CEO Gary Kramer on Q4 2021 Results – Earnings Call Transcript

Barrett Business Services, Inc. (NASDAQ:BBSI) Q4 2021 Earnings Conference Call March 2, 2022 5:00 PM ET

Company Participants

Gary Kramer – President & Chief Executive Officer

Anthony Harris – Chief Financial Officer

Conference Call Participants

Chris Moore – CJS Securities

Jeff Martin – ROTH Capital Partners

Vincent Colicchio – Barrington Research

Matt Dane – Titan Capital Management

Operator

Good afternoon, everyone, and thank you for participating in today’s conference call to discuss BBSI’s Financial Results for the Fourth Quarter and Full Year Ended December 31, 2021. Joining us today are BBSI’s President and CEO, Mr. Gary Kramer; and the Company’s CFO, Mr. Anthony Harris. Following their remarks, we’ll open the call for your questions.

Before we go further, please take note of the Company’s Safe Harbor Statement within the meaning of the Private Securities Litigation Reform Act of 1995. The statement provides important cautions regarding forward-looking statements. The Company’s remarks during today’s conference call will include forward-looking statements. These statements, along with other information presented that does not reflect historical facts, are subject to a number of risks and uncertainties. Actual results may differ materially from those implied by these forward-looking statements.

Please refer to the Company’s recent earnings release and to the Company’s quarterly and annual reports filed with the Securities and Exchange Commission for more information about the risks and uncertainties that could cause actual results to differ from those expressed or implied by the forward-looking statements.

I would like to remind everyone that this call will be available for replay through April 2, 2022 starting at 8:00 PM Eastern tonight. A webcast replay will also be available via the link provided in today’s press release, as well as available on the Company’s website at www.bbsi.com.

Now, I would like to turn the call over to the President and Chief Executive Officer of BBSI, Mr. Gary Kramer. Sir, please go ahead.

Gary Kramer

Thank you, Paul. Good afternoon, everyone, and thank you for joining the call. Our operational and financial results were exceptional in the fourth quarter and capped off a great year. We consistently exceeded our internal estimates for client retention, net client adds and worksite employee growth, all of which resulted in better than expected financial results.

Before I speak to the financial results, I would like to recap some of the key operational and strategic accomplishments for the year. We successfully completed the conversion of our existing clients over to our new My BBSI platform.

We are pleased with the platform, but more importantly, our clients are appreciative of the investment and the feedback continues to be positive. We are not done with our investment and have an IT roadmap of enhancements, new features, as well as new products.

We packaged our new technology with our nationwide offering and brought on larger clients on average this year than we have in previous years. We built out a corporate sales department and increase the top of the funnel by focusing on lead generation via an omni channel digital campaign, which brought on new clients and new referral partners.

We executed on our employer of choice initiative and invested in our employees with robust enhancements in compensation, benefits, vacation, training and volunteerism. People are our product and we attract, train and ultimately retain the best employees that any PEO has to offer. In November, we were pleased to announce that we were certified as a great place to work for the first time.

We successfully rolled out our asset light markets, which encapsulates everything I just mentioned. Attract and hire great people, train them well, apply the lessons we learned in a COVID environment for how to operate remotely and packaged with our digital initiatives to help grow their market penetration.

We will serve as the clients out of an adjacent branch or a corporate and invest behind them and infrastructure as they build up their client base. We entered into workers compensation insurance transactions, which de-risk our business model and results in better financial predictability.

These transactions are structured in a manner that greatly limit any potential downside of our insurance program. But we can still share in the upside of our disciplined underwriting. I want to again thank everyone in the BBSI family for their exceptional efforts. Plainly stated, I am proud that we foster a culture that embraces innovation and execution.

Moving to our financial results. During the quarter our gross billings increased 13{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} over the prior years quarter and exceeded our expectations. Our average worksite employees were up 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} over the prior year quarter. We have exceeded our pre-pandemic levels and 2021 finished the year with the highest year-end worksite employees in BBSI’s history. This is due to our clients hiring as well as net new business and we continue to be the head of our internal forecast for our worksite employee stack.

Our staffing business increased 14{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} over the prior year quarter. We could have grown more, but continued to have challenges filling orders with the tightness of the labor market. We are seeing more applicants, placing more applicants and companies are increasing wages to attract employees. We are still unable to fill all of our orders but our fill ratio improving.

So to summarize our financial performance for the year, our gross billings increased by 11{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and our earnings per share grew by 14{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, which is in line with our long-term growth plans. We returned $9 million in dividends and bought back shares totaling $17 million, which reduced our shares outstanding by 3.2{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. These are fabulous results and a great return for shareholders.

Moving to the branch operational updates. Our branch footprint decreased by three to 50 total branches. We continue to be mindful of operating efficiencies and consolidated Glendale into Phoenix, Eugene into Willamette Valley and Valencia into Pasadena. These decisions were made with the intention of continuing to grow revenue while servicing our clients, but doing so in a more cost efficient manner.

Our branch stratification is as follows. 23 mature branches with run rates in excess of $100 million, 17 emerging branches running between $30 million and $100 million, 10 branches we consider developing with run rates up to $30 million. Our business units total 98 and incorporates the consolidations previously mentioned. We also continued our migration into revised structure of our 16 member business unit, which allows us to serve as more clients with less management employees and increases our return on management payroll.

To summarize our branch footprint over the past two years. At the end of 2019, we had 64 branches. Over the past two years, we consolidated 19 branches within existing markets and expanded five branches in the new markets, finishing 2021 with 50 branches. By the end of 2022, we forecast that our gross billings will be up by approximately 20{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} over 2019 but our SGMA fuel payroll will only be up by 6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and that includes investing in 14 asset-light markets.

Speaking to the asset-light model, our first-class has graduated and is currently selling in four new markets. We are still in the early innings but through February, we have eight new clients added during contracting. We are seeing positive trends in this model and intend to invest in approximately 10 new markets in 2022 and are actively recruiting in markets we’re not in now.

Moving to our client and WSE stack. Our client retention continues to be stronger than pre-pandemic levels. I like to attribute that to the work we do with our clients and the value our teams bring in this ever changing in complex economic environment.

Regarding our distribution channels, business is almost back to normal. Our leads and prospects in the quarter were greater than the previous quarter and our best quarter post-pandemic. We had a strong fourth quarter and our year-end WSE stack was the highest in our history.

More importantly, we capitalized on the one-one selling season and this January was our best January for net new business in the past five years. Better than pre-pandemic. We continue to invest and refine our longer-term initiatives of increasing the top of the funnel by focusing on lead generation via an omni channel digital campaign, where we target both clients and new referral partners in different markets.

Results thus far are positive. We are signing up new referral partners and new clients that would not have come to us via our traditional channels. We will continue this initiative and make further investments in 2022. These positive trends resulted in the company adding over 1,300 net new worksite employees in the quarter, which was ahead of our forecast and further supports our optimistic outlook for 2022.

As I think to the future, I’ve never been more optimistic about BBSI trajectory. We had great momentum in 2021 and it is carrying into 2022. Our client retention is the best it’s ever been. And we’re seeing in closing on more prospects. Our prospects continue to be larger because of our technology stack, coupled with our nationwide offering. We will continue to invest in technology. And we will continue to invest in growth initiatives.

We have minimized the insurance risk to the company. And the only thing that can hinder our progress now is execution risk. And honestly, our fabulous results speak for themselves.

Now I’m going to turn the call over to Anthony for his prepared remarks.

Anthony Harris

Thanks, Gary. Hello, everyone. I am pleased to report we finished 2021 with strong results and as Gary noted strong momentum. Both the quarter and the year exceeded our expectations. Starting with the full year first, our gross billings increased 11{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to $6.6 billion and diluted EPS increased 14{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to $5 per share compared to $4.39 in the prior year. The increase in earnings leverage was achieved even with the return to more sustainable SG&A levels in 2021 from the uniquely low levels seen in 2020.

Focusing on our Q4 numbers, net income for the quarter was $10.6 million compared to $7.2 million in Q420 20. Q4 PEO gross billings increased 13{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} over the prior year quarter to $1.8 billion. Staffing revenues increased 14{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to $33 million. Our increase in PEO gross billings was driven by stronger than expected growth from net new clients in the quarter, continued strong hiring within our customer base and higher average billing per WSE. Our Q4 average WSEs increased 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} year-over-year, while our average billing for WSE increased 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, driven primarily by higher wages.

PEO gross billings growth by region versus the prior year fourth quarter were as follows. Mountain States grew 38{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, East Coast grew 19{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, the Pacific Northwest grew 15{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, Northern California grew 13{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and Southern California grew 6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

As discussed in prior quarters, the primary driver of the slower growth in Southern California is lower same customer sales growth, as our clients are adding fewer new employees than in other regions. However, we continue to see positive trends in the region, including faster sequential growth in Q4 than in Q3 and we expect this momentum to continue into 2022.

Workers’ compensation expense continue to trend favorably in the quarter and included an actual early determined reduction of prior year estimated liabilities of $1.7 million in the quarter. Our claims performance also remains favorable and our relative frequency rate once again, trended down in the quarter and remains well below historical rates.

As a reminder, we entered into a new fully insured workers compensation program effective July 1 for the majority of our clients. We now describe our workers compensation coverage for clients, as being under either this insured program or our self insured programs.

Approximately 82{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of our workers compensation exposure including, all California clients are covered by our insured program. All claims incurred in these states after July 1, are not covered 100{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} by the insurance market, with zero claims cost retained by BBSI.

The strategy of de risking your operations through this insured program is operating as planned with favorable results. And we expect these favorable results to continue into 2022. Because of the move to our fully insured program, our workers compensation liabilities decreased by approximately $18 million in the fourth quarter, as remaining historical claims continue to be paid.

Looking at margin and pricing, we are seeing billing rates for new at levels consistent with the prior year. Looking at the market more broadly, market pricing for workers compensation coverage has now largely flattened after decreasing for several years.

Rates remain at low-levels, relative to historical rate. But these lower rates have been offset by lower worker’s compensation expense in the year. And our margin rates have remained stable.

We continue to see strong client retention in the fourth quarter and beyond, which demonstrates the value we’re creating for our clients and supports our ability to maintain margins even competitive pricing environments.

Moving to operating expenses, as SG&A for the quarter came in line with expectations, at approximately the same levels of Q4 2020. As discussed in prior quarters, much of 2021 saw faster year-over-year growth in SG&A, due to the abnormal compare in Q2 and Q3 of 2020.

As we look ahead to 2022, we expect to return to more normalized SG&A growth rate, in line with our target of approximately half of our top line billings growth. Our largest increase in SGA will come from employee related expenses in 2022, including higher average wages and increased headcount, primarily to support growth initiatives.

We continue to closely manage our operating expenses and our management employee headcount, in 2021, still ended below that of 2019. Our investment portfolios earn $1.7 million in the fourth quarter, compared to $1.6 million in the prior year quarter. Our investments continue to manage conservatively, have an average duration of 4.1 years average quality of investment at AA, and average book yield of 1.8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Turning to the balance sheet and our capital plan, we had $166 million of unrestricted cash investments at December 31st, compared to $116 million at September 30th. As we continue to evaluate our most efficient capital arrangements, we renegotiated our credit agreement with Wells Fargo to increase our line of credit to $50 million from $33 million previously, and extend the agreement, the maturity of the agreement to June of 2024.

With favorable fee changes, the increased capacity will come with little incremental cost. We also restructured our covenants to provide more flexibility, including in share repurchases. To further optimize our capital commitments, we have purchased certain assets that were formerly leased. This will show us an increase in Q1 CapEx, it will result in lower overall operating expense for the company going forward. And subsequent to year-end, we paid off the remaining balance on our corporate headquarters mortgage, and as a result, we can now say that we are completely debt free.

We continually assess the level of capital needed to maintain effective business operations with appropriate risk mitigation. This minimum level of required capital has decreased as we have de risked our model and now retain less Workers Compensation Claims exposure. We are committed to deploying our excess available cash investments in ways that benefit the long-term health of the company and our shareholders.

I will recap our general philosophy on capital allocation. Our first priority is to invest in the business. Our best path to continued earnings growth is operating leverage through scale, and we continue to seek out new opportunities to invest in order to scale consistently and effectively. This investment typically comes in the form of strategic hiring and focus growth initiatives. And it will also continue to include investment in IT software and infrastructure in the year as we focus on enhancing our product and our client experience.

Second, we have said that we are open to investing in inorganic growth through acquisitions and this remains true, but we are also committed to ensuring that any potential acquisition is right for our company and our shareholders for the long-term.

Third, as BBSI continues to steadily generate positive free cash flow, we remain committed to returning capital to shareholders. In 2021, we returned $26 million to shareholders through a combination of dividends and stock repurchases. This equates to an income payout ratio for the year approximately 70{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

To solidify our commitment to drive shareholder value, our Board of Directors has approved a new $75 million, two-year stock repurchase program, which will replace the 50 million, three-year repurchase program that was previously in effect. In addition, BBSI remains committed to its dividend and the Board also reconfirmed our quarterly dividend of $0.30 per share to be paid April 1st.

Turning now to the outlook for 2022, we expect gross billings to increase between 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and 9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for the year. We expect average WLC to increase between 3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and 4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. We expect gross margin as a percentage of gross billing to be between 3.0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and 3.1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. And we expect our effective annual tax rate to be between 24{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and 25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

I will now turn the call back to Gary for closing remarks.

Gary Kramer

Thanks Anthony. 2021 was a great year and we think 2022 is going to be even better. We continue to always think of the client first and to advocate for the success of the business owner. We’ve been working on the right things and I think we’re in a great position for future growth.

Now I’d like to turn the call over to the operator for questions.

Question-and-Answer Session

Operator

Thank you. We’ll now be conducting a question-and-answer session. [Operator Instructions] Thank you. Our first question comes from Chris Moore with CJS securities. Please proceed with your question.

Chris Moore

Hey, good afternoon guys. Thanks for taking a couple questions. Yes, so given the changes with the Chubb trust and rising rates, when you’re looking at investment income for 2022, how does that compare with 2021?

Anthony Harris

Yes. That’s a great question, Chris. We’ve said previously with our fully insured model, as we have capital requirements going down, we expect our restricted investments to go down, that will be the case. On the other hand, we are seeing rising short-term interest rates in a year. So those are effectively offsetting in our forecast for 2022 in terms of investment income.

Chris Moore

Got it. All right. Maybe can you talk a little bit about the shape of your earnings quarter-to-quarter in fiscal 2022 versus 2021?

Anthony Harris

Yes. Absolutely. So if you look at our income, it is always seasonal, and that’s driven by the timing of when payroll taxes are incurred, and those are front-loaded primarily into Q1. So Q1 will always be our lowest profit quarter. Correspondingly, Q3 is typically our highest profit quarter, and Q2 and Q4 usually similar, but lower profits. And that will be true again this year.

One thing is, if you look at our top line growth in the year, we’re expecting sequential growth in each quarter. But when you look at the compare from 2021, there will be some variance in the quarters. So Q1 will be our strongest top line growth quarter, if you look at the year-over-year compares. And Q4 actually will be lower in part, because 2022 does have one less business day. So that that equates to about a half a percentage point of billings growth that will lose in 2022, because of that one less business day and that occurs in Q4. So on a year-over-year basis, Q1 will be strongest, Q4 will be weakest, Q2 and Q3 will be more consistent on the top line.

Chris Moore

That is extremely helpful. I’ll jump back in line. I appreciate it guys.

Gary Kramer

Thanks, Chris.

Operator

Thank you. Our next question comes from Jeff Martin with ROTH Capital Partners. Please proceed with your question.

Jeff Martin

Thanks. Good afternoon, guys. I was just curious if you could dive into the worksite employee growth a little more during the quarter primary drivers net hiring versus wages, how those two breakout and if there are any — excuse me, any other factors?

Gary Kramer

Yes. I’ll start it off in an Anthony can clean it up. I would say, the one I’m the most proud of in the quarter is clients we added and the worksite employees they had, minus clients that ran off and the worksite employees they had, resulted in us having 1,300 more worksite employees that we added in the quarter, right? And that is our, what we call here, that’s our controllable organic growth, right, which we’re very pleased with. And we’ve had strong track records of that over the last couple quarters and a very strong track record of that going into January as well that I mentioned in my script. So if you take our controllable organic and then you add the same customer sales. What’s the same customer sales, Anthony?

Anthony Harris

8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Gary Kramer

8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Anthony Harris

Well, 6.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} average billing for WSE increase for the year. Is this sort of, I mean, to jump in?

Gary Kramer

Yes. Yes, clean me up.

Anthony Harris

So for the figures, we gave quarterly figures and annual figures, Jeff. But for the annual figures, for average WSE growth, it was 4.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and within that number that’ll include WSEs from client hiring, but also net new client ads. And as Gary said, the portion of net new client ads is the highest it’s been in years on that. So, that’s fantastic news. On the average billing per WCS at 6.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} for the year and we saw that right off the bat early in the year we were seeing high year-over-year billings growth for WSC, and partly that was attributable to employee mix shift towards higher wages.

But especially later in the year that was driven genuinely by wage inflation. So, we’re seeing through wage inflation come through particularly in Q4. And that’s part of the momentum we talked about going into 2022.

Jeff Martin

Yes, yes. Okay. And then the prospects for average size of new clients is interesting. You would think that would become a fairly significant growth tailwind in the not too distant future. I was just curious if you could give us some relative perspective on the size of new clients you’re bringing on now versus maybe in 2018 or 2019?

Gary Kramer

Yes, if you go back to what I meant, if I go back to what I mentioned earlier about the clients we’re adding as far as clients rather than to WCS, they had lot clients that are running off with the WCS, they had that got it to the positive 1,300. And I want to say that our unit counts to put it in perspective, our unit counts are more I’ll say consistent now.

In the past, we were adding smaller clients and running off larger clients, and you had to add two or three to make up for the one you lost. Where we’re getting at now is we’re adding clients that are larger than what we’re running off.

So, our — if you say our average worksite employee per client is about 26, we’re adding north of 26 of WSCs on average now. We have some still smaller than that, but the majority seem to be larger than that. And one of the things we’ve done too is we have been — we love small clients that become big clients and we love small clients that we can make adequate marginal.

But if we’re not making the adequate margin on the smaller clients or they don’t have plans to grow, then we try to make the business decision to focus on the larger business now.

Jeff Martin

Yes, yes. Okay. And you’ve been in the CEO role for almost two years now or maybe it’s been two years. I was just curious from your perspective, how you see a typical market cycle affecting the business and what are some of the things you do strategically and/or operationally as part of the different phases of the cycle?

Gary Kramer

Good question. And it has been a long two years and it’s hard to visualize what normal is with no pandemic or hyperinflation or conflict over in Europe. But just in general, the way the way that we think of the businesses — and I’ll talk, approximate, right, because I’ll do round numbers and try to keep it simple.

Kind of last year results is what we think we’re capable to put up annually, right where we can grow the topline 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. Grow the SG&A in a normal market at about half of what our topline is. And then what that equates to the bottom-line is about a 15{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} increase in net income and we feel like we’ve got the machine in place to consistently over cycle get, 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} on the top and 15{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} on the bottom.

Jeff Martin

That’s nice. That it should be great to see that happen. I know a lot of this have been rooting for the SG&A leverage over the years and it sounds like you’re at that point. Now you did make a comment that in — in a normal environment. Do you expect that you’ll be able to experience that leverage this year or does wage inflation and employee retention become a factor where that may not be the case, just yet this year or parts of this year?

Gary Kramer

We’ve modeled in that. And we’ve also modeled in investments in other company, investments in adding new headcount, investments and I mentioned adding the 10 new markets and even layering all of that in, we feel pretty confident that we’ll be able to do it. I mean, if you just keep it simple, if you put up 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} growth at a 3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} margin that’s about $20 million of gross margin and we’re mindful of how we — how we invest in the SG&A so that we show leverage down the bottom for the net income growth.

Jeff Martin

Okay, great. Thanks for taking my questions.

Operator

[Operator Instructions] Thank you. Our next question comes from Vincent Colicchio with Barrington Research. Please proceed with your question.

Vincent Colicchio

Yes, Gary. Nice quarter. I think I heard you say that you’re investing in 10 new markets in 2022. That sounds pretty aggressive versus the past. Can you maybe take us through your thinking on that is it just more optimism — any thoughts would be helpful.

Gary Kramer

Yeah. So this kind of ties into my prepared remarks where I talked about our asset light model, right. So we were able to attract good talent. We’ve invested in training good talent, we have emerging training with them as well. We get them up to speed where they can go sell in their market, when they sell in their market we assist them with our digital campaigns. And really, that’s one salesperson in one market. And then what we do is support that business either out of corporate or an adjacent market. So we call that the asset light because what we’re really doing is hiring 10 folks and putting them in 10 markets. And what we’re seeing so far after experimenting with this in 2021 is saying, all right, we feel comfortable with — what the results we got and where we are for 2021. We’re going to double down in 2022 on this program. And the idea is, once they are successful and they begin to get critical mass then we will invest in infrastructure behind them in that market as far as people to help service the business locally.

Vincent Colicchio

And can you talk a little bit about acquisitions has you’re focused changed at all or you still get the same markets and how does pricing look?

Gary Kramer

Not much of an update there. You know we look at everything that comes across, we’re active. But we are thoughtful, right? We are thoughtful of shareholder, equity and we need to make sure that we put on the right acquisition, not just any acquisition and that just comes down to how we look at our capital and the risk that we have to take with capital. So we are active. We will continue to be active, but we will be mindful. I said in prior quarters that you got to kiss a lot of frogs. We’re still kissing frogs.

Vincent Colicchio

And what did the mix look like in the quarter in terms of WSE additions from referrals and your new model?

Gary Kramer

Versus direct? So the direct versus the referral channels, we are a heavy referral channel business and that’s where the majority of our business comes from and will continue to come from. And we love our referral channels. I mean, part of our digital campaign is to try to attract new referral partners. And if I look at Q4 for referral partners, that brought us leads or prospects for Q4 ’21 versus Q4 ’20. Now these are new referral partners, new to BBSI. We had three times the velocity of new referral partners that were feeding us business in ’21 versus ’20. Part of that is a function of ’20 was still coming out of pandemic, number one. But number two is, we have the discipline to seek out referral partners and we’re using technology to assist us with that.

Vincent Colicchio

And how does the pipeline of leads and prospects look now versus last quarter?

Gary Kramer

If I just look at our prospects that we had going into Q4, we were about 50{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} higher than we were in the prior year, which results in it’s kind of math if you keep your close ratio the same. We had more closes in Q4, which added to our strong WSE growth in Q4. But that momentum carried into January and January was our strongest January as far as net client adds over the past five years. So positive things Q3 and the Q4 that continued into Q1, which gives us – those clients, we add in Q4 and early January give us a real good tailwind for revenue growth for ’22.

Vincent Colicchio

Sounds good. Nice job. Thanks.

Operator

Thank you. Our next question comes from Kevin Mackey [ph], Independent Analyst. Please proceed to your question.

Q – Unidentified Analyst

Yeah. So I believe it was last conference call that you mentioned your new technology…

Gary Kramer

Hello?

Operator

This is the end of our question-and-answer session. I’m sorry. One moment. Our next question comes from Matt Dane with Titan Capital Management. Please proceed with your question.

Matt Dane

Great. Thank you. I wanted to delve a little bit more into your initiative to attract larger clients. What additional color can you share around that? What specifically are you doing to help drive those larger clients and attract them to work with CBSI?

Gary Kramer

Yeah, sure. The technology that we have is able to bring on larger clients. Now, the clients appreciate our technology much more than what we had in the past. That’s first and foremost. The second is, larger clients have exposure in various States. Before, we weren’t able to do — we weren’t licensed in every state [indiscernible], so now we have the technology. And we can go anywhere they go as far as on the state mix. And, you know, we mentioned that we are investing in technology and we’ll continue to invest in technology and part of these investments we will be making in 2022 is to better support larger clients. Because larger clients have a — I’ll say a different need or sophistication than a smaller client and we’re going to utilize and invest in technology to make that business, I’ll say, easier to flow data with our larger clients.

Matt Dane

Okay. That’s helpful. And then on the actual sales and marketing side. I understand that the technology is really facilitated today compared to the past. But in regards to targeting them specifically, is it more of just interactions with your referral sources and asking them telling them – telling them, hey, these are the ideal type of clients and — or is there other sales and marketing approaches that really allow you to target those – this type of clients that you’d like better?

Gary Kramer

There is two-fold here, right. One is we’re using technology on the sales and marketing side. And I don’t want to get into too much of the plumbing because we have about 500 competitors that listen to this call. So we utilize technology to get to clients that we that — that wouldn’t have typically come to us before, especially in new markets where we’re building out and we’ve learned a lot in 2021. We have been refining as we go and we think we, you know, we think we have a better mousetrap for 2022 than we did for 2021. Is it perfect? No. Is it better than it was? Yes. Will we continue to evolve it? Absolutely.

And then on the referral partner side, it’s, you know, it’s really being comfortable with your expertise and knowing who you are, right? You know, we can go in with a referral partner and understand what their specialty is right. So if their specialty is transportation, that’s like great. We have a huge portfolio of transportation.

Let me help you and do some co-branding and co-marketing on the transportation. Is it you know, pick an industry right and we can work with them that way because it depends on how the distribution channel comes to you and what their specialty is and that’s how we try to align with them.

Matt Dane

Great. That’s helpful. Thank you, guys

Operator

Thank you. There are no further questions at this time. I would like to turn the floor back over to Gary Kramer for any closing comments.

Gary Kramer

I just want to wrap-up and thank everybody at BBSI for their hard work. And I just want to say that 2021 was a great year and we feel good momentum and good trajectory and are optimistic about where 2022 is going to go. So thank you, everybody.

Operator

This concludes today’s conference. You may disconnect your lines at this time. Thank you for your participation.


Barrett Business Services: Buy BBSI Stock Before Earnings Today

Barrett Business Services: Buy BBSI Stock Before Earnings Today

Businessman touching to virtual screen with infographic and HR wording , Human development and recruitment concept.

Dilok Klaisataporn/iStock by using Getty Visuals

You will have to forgive me for abandoning my usual format, as modern post will be brief and sweet. Bottom line up entrance: acquire Barrett Enterprise Solutions ahead of earnings are introduced right after the marketplace closes these days. They are 13{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} undervalued even under pessimistic assumptions, and 32{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} off their all-time highs, for no great motive.

BBSI Stock Valuation

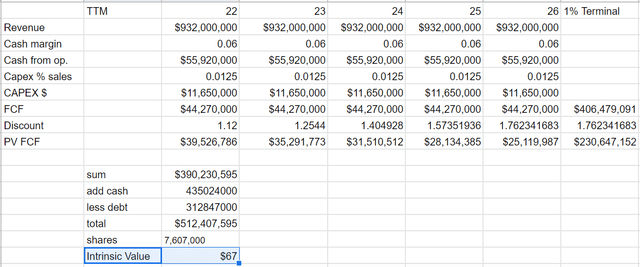
I will start where I ordinarily conclude, and that is with a DCF assessment. Listed here is the spreadsheet, with a discussion following:

Spreadsheet

Spreadsheet (Compiled by author)

Discover the flat revenue for the following 5 many years, a cash from functions margin of 6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} that is way below their extended-phrase common (pandemic decades with negative values inclusive) of 8.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, CAPEX fees that amount of money to 1.25{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of income in spite of CAPEX historically currently being only .72{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of revenue, a terminal price of only 1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, and the significant discounted price of 12{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} (my essential charge of return). Even under this gloomy condition, BBSI is nonetheless value $67, nicely over the place they are now investing.

Barrett Organization Services – Quarterly Expectations

Administration sounded extremely optimistic about how they have been established up to finish the year. Q3 revenues have been up 8.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} more than the prior year’s similar quarter, and if the exact same repeats in Q4 they will put up an all-time substantial quarterly profits of $253 million. This would carry their once-a-year earnings to $951 million, also a report.

Specified that their revenue is calculated as a p.c of the wages of the employees of the clientele they aid, and considering that wages and work have the two been sturdy these days, the chance of them accomplishing these history quantities is incredibly superior.

In spite of these strong figures the stock trades at a P/E ratio of just a lot less than 13. I anticipate sizeable various expansion on the again of sturdy outcomes and healthy forecasts.

Also encouraging is the actuality that as of the conclude of Q3 they still experienced $31 million remaining on a share repurchase plan. With the stock acquiring faced these kinds of a extreme descent, hopefully they had been opportunistic about splurging when the price ranges have been small.

Other pertinent developments

BBSI has penned new coverage preparations with Chubb wherever-in they are no extended assuming the possibility of paying promises for masking their clients’ workers payment demands. That chance has been transferred, and all related liabilities from prior many years underwriting will gradually run-off the equilibrium sheet. This significantly de-dangers the organization product.

They have moreover consolidated their department footprint and moved to a much more personnel light company design. This must see price tag savings accrue about time.

Also, BBSI has implemented a new referral program wherever-in they can funnel much more options. From the conference contact:

Very last quarter we reviewed our for a longer time-time period initiatives in which we intend to maximize the best of the funnel by concentrating on guide era by using an omni-channel digital campaign wherever we focus on both consumers and new referral associates in distinct markets. We are only 4 to five months into the various trials, but I am energized about what we are looking at and I would like to offer some studies since the previous earnings connect with.

We have signed up 82 new referral companions and we set up 74 new conferences with interested likely shoppers. We are testing and refining our a variety of profits initiatives by sector, measuring the return on investment and will transport the most effective method to our other markets. We continue to package our new engineering with our nationwide giving, and we proceed to see much larger prospects.

Last but not least, BBSI recently rolled out a new engineering system. It is by way of this automobile that they will be in a position to enhance their benefit proposition by supplying new products and services, and subsequently justify charging a lot more for what they do. From the CEO:

We crafted our portal out with the plan that we personal our technology destiny. So, we have the means to plug in more goods and solutions. Whether or not we make enhancements or boost productiveness in there or we white label things and plug it in. There is a limitless likely for goods and products and services that we can convey in. And we’ve got folks performing on executing to that solution highway map so that we can in the long run have a lot more matters that we can provide to make us both extra beautiful or the business enterprise stickier. But we are not heading to spill the popcorn right up until we do the launch on all those.

Summary

Forgive me for not becoming as thorough and in-depth as typical. But provided that this update is time delicate, I favored concision. Eventually, BBSI is executing at a degree considerably increased than their P/E would point out. If success occur in as healthy as I am anticipating, numerous expansion is likely. Coupled with probably earnings development from larger income and lower expenses, buyers will take pleasure in tremendous value appreciation.

3 Business Services Stocks With Impressive Dividend Yield

3 Business Services Stocks With Impressive Dividend Yield

This story at first appeared on Zacks

The Organization Expert services sector has been steadily collecting steam on the again of gradual resumption of company functions, improved adoption and accomplishment of the work-from-household design, rise in desire for hazard mitigation and consulting expert services, and abilities in improving upon operational performance and minimizing charges. Providers of vital and non-deferrable solutions, such as waste removing and building upkeep, remained resilient to the pandemic-induced disruptions.

– Zacks

Since of its commonly-diversified nature, the sector was broadly aided by the recovering overall economy, manufacturing and non-manufacturing power, and greater vaccination drives. When Omicron and Delta variant cases have raised considerations these days, production and company power acted as a tailwind for the sector, which is a important beneficiary of the broader economy. Notably, the Institute for Supply Administration measured that the two Producing PMI and Companies PMI clocked the 20th consecutive thirty day period of growth in January.

Meanwhile, a continual restoration is obvious from the most up-to-date fourth-quarter 2021 GDP quantity, which in accordance to the “second” estimate released by the Bureau of Financial Assessment, amplified at an yearly charge of 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, better than 2.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} advancement witnessed in third-quarter 2021.

In look at of the aforementioned favorable developments, a couple small business companies companies these as Trane Systems plc TT, Verisk Analytics, Inc.VRSK andThe Interpublic Group of Firms, Inc. IPG have picked to reward their shareholders with dividend hikes. We imagine regularity in worthwhile shareholders by dividend payments or share repurchases not only boost trader self-assurance but also positively affect a company’s earnings for each share.

All the 3 stocks at the moment have a Zacks Rank #3 (Hold). You can see the full record of today’s Zacks #1 Rank (Strong Acquire) shares right here.

3 Companies That Rewarded Shareholders

Trane Systems: This Eire-primarily based corporation has amplified its quarterly dividend rate by 14{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} from 59 cents per share to 67 cents for each share. The improved dividend will be paid out on Mar 31, 2022 to shareholders of report at the shut of company on Mar 4.

Trane Technologies continues to be focused on improving the high quality of its merchandise and products and services and running efficiencies to accomplish sustained improvement in earnings and cash circulation. It prioritizes improving upon its enterprise running procedure and innovation by means of organization transformation initiatives and prudent investments. Trane has a keep track of document of repurchasing shares and paying dividends continuously.

The Zacks Consensus Estimate for Trane Technologies’ 2022 EPS has moved up .4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in the past 90 days. The company’s expected earnings expansion amount for the year is 15.6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. Additionally, it has a long-term (three to 5 a long time) predicted earnings growth charge of 18.6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. The firm has a trailing 4-quarter earnings surprise of 16.1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, on average.

Verisk: This New Jersey-based facts analytics solutions’ provider corporation has hiked its quarterly dividend by 6.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} from 29 cents for each share to 31 cents per share. The elevated dividend will be paid out on Mar 31, 2022, to shareholders of file as of Mar 15, 2022.

Toughness throughout all the segments has been aiding Verisk’s major line. The firm has a robust expansion tactic that focuses on natural and organic advancement, product growth and acquisitions. Verisk’s know-how in giving predictive data analytics and decision guidance options offers it an edge above its competitors. The company has been obtaining and investing in providers globally in order to broaden its knowledge and analytics abilities. Organic and natural growth in just the organization, decreased curiosity costs, effective tax fee and average share count have been aiding Verisk’s bottom line. 

The Zacks Consensus Estimate for Verisk’s 2022 EPS has moved up .8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in the past 90 times. The company’s expected earnings growth rate for the yr is 11.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. In addition, it has a extensive-expression (3 to 5 several years) anticipated earnings growth price of 12{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. Verisk’s shares have rallied 7.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} more than the previous calendar year.

Interpublic: This New York-based mostly provider of promoting and internet marketing solutions introduced a dividend hike of 7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, thereby elevating its quarterly income dividend from 27 cents for each share to 29 cents.

Interpublic’s electronic capabilities, numerous workforce and geographic get to offer you a exclusive competitive advantage. It has been attaining and investing in providers globally, in order to extend its product or service portfolio and regulate by itself with the promptly shifting advertising providers and media prospective clients. The favorable influence of organic internet revenues and international forex movements have been aiding Interpublic’s top line.

The Zacks Consensus Estimate for Interpublic’s 2022 EPS has moved up 1.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} in the past 90 times. The company’s expected earnings growth price for the yr is 3.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. On top of that, it has a long-time period (three to 5 a long time) envisioned earnings progress rate of 11.8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. The organization has a trailing 4-quarter earnings surprise of 66.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, on average. Interpublic’s shares have rallied 39.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} over the previous year.

Just Introduced: Zacks Top rated 10 Stocks for 2022

In addition to the expense ideas reviewed over, would you like to know about our 10 best get-and-hold tickers for the entirety of 2022?

Past year’s 2021 Zacks Major 10 Shares portfolio returned gains as superior as +147.7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}. Now a brand name-new portfolio has been handpicked from in excess of 4,000 firms lined by the Zacks Rank. Never skip your chance to get in on these very long-time period buys

Obtain Zacks Prime 10 Stocks for 2022 nowadays >>

Want the newest suggestions from Zacks Expense Investigation? These days, you can download 7 Very best Shares for the Following 30 Times. Simply click to get this cost-free report
 
Interpublic Group of Organizations, Inc. The (IPG): Cost-free Inventory Investigation Report
 
Verisk Analytics, Inc. (VRSK): Free of charge Stock Investigation Report
 
Trane Systems plc (TT): No cost Inventory Evaluation Report
 
To study this write-up on Zacks.com click on right here.
 
Zacks Investment decision Study

Lincoln Educational Services Reports Continued Growth for Fourth Quarter and Full Year 2021

Lincoln Educational Services Reports Continued Growth for Fourth Quarter and Full Year 2021

2021 Operating and Financial Results Met or Exceeded Guidance

Conference Call Today at 10 a.m. ET

PARSIPPANY, N.J., Feb. 28, 2022 (GLOBE NEWSWIRE) — Lincoln Educational Services Corporation (Nasdaq: LINC) today, reported operating and financial results for the fourth quarter and full year ended December 31, 2021 as well as recent business developments.

Fourth Quarter 2021 Financial Highlights and Recent Operating Developments

  • Revenue of $87.8 million, up 7.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} compared to prior year

  • Adjusted EBITDA* of $15.1 million, up 13.1{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} over prior year

  • Average student population up 6.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}; ending population up 6.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} or 850 students

  • Consummated sale-leaseback transactions generate gain on sale of $22.5 million and net proceeds of $45.4 million, with approximately $17 million used to retire all outstanding debt

  • Net cash position of $83.3 million, up $62.5 million over prior year

  • Net income of $24.0 million

Full Year 2021 Results – Achieved or Exceeded Guidance

  • Revenue grew 14.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

  • Student start growth of 7.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

  • Adjusted EBITDA* of $38.1 million

  • Adjusted pre-tax net income* of $27.1 million

*See Use of “Non-GAAP Financial Information” below.

“Strong execution, both during the fourth quarter and for the full year, allows Lincoln to enter 2022 in an extremely strong operating position with approximately 850 more students compared to the year-ago period. Additionally, the proceeds from the sale-leaseback transactions significantly improved our liquidity, giving us one of the strongest balance sheets in Lincoln’s 75-year history,” said Scott Shaw, President & CEO. “Our continued success, high graduate placement rates and a more favorable outlook for high school student starts compared to a year ago, gives us a high degree of confidence that we can achieve even greater results for years to come.

The expected proceeds of approximately $34.0 million from the contemplated sale of our Nashville, Tennessee property, assuming consummation, combined with our continuing strong cash flow provides the Company with even more financial resources to execute our near and long-term growth strategies. During 2022, we plan to begin the relocation of our Nashville campus to a new and more efficient facility in the Nashville area. Furthermore, we plan to expand our footprint through a new campus while continuing to invest in new programs. We are poised to execute these strategies to generate consistent, long-term growth while enhancing our ability to serve our growing student population as well as our corporate partners.”

2021 FOURTH QUARTER FINANCIAL RESULTS

(Quarter ended December 31, 2021 compared to quarter ended December 31, 2020)

  • Revenue increased $6.0 million, or 7.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, to $87.8 million from $81.8 million. The increase in revenue resulted from a 6.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} increase in average population, driven by a 7.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} increase in starts for the year.

  • Educational services and facilities expense increased $3.3 million, or 10.6{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, to $34.8 million from $31.5 million in the prior year comparable period. Increased costs were primarily concentrated in instructional expense, books and tools expense and facilities expense. In addition to increases resulting from higher student populations, instruction expense rose due to higher salaries as a consequence of inflationary pressures and instructor shortages, particularly in nursing programs. Facility expenses increased $0.6 million due to additional rent expense in the current quarter as a result of the sale-leaseback transactions.

  • Selling, general and administrative expense increased $1.6 million, or 4.0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to $40.8 million primarily due to an increase in benefits expense driven by an uptick in medical claims in the current year in combination with a slight increase in salaries.

  • Gain on sale of assets was $22.5 million recorded upon the consummation of the sale-leaseback transactions involving the Denver, Colorado and Grand Prairie, Texas campuses.

  • Operating income increased to $34.0 million in 2021, from $11.1 million in the prior year period. The increase was mainly driven by a $22.5 million gain resulting from the sale-leaseback transactions, partially offset by $0.6 million of additional rent expense related to the two campuses that were subject of the sale-leaseback transactions and a $0.7 million non-cash impairment charge to adjust the book value of a former campus facility, which closed about 10 years ago. Excluding the impact of the sale-leaseback transactions and the impairment charge as a one-time event, operating income would have increased $1.7 million, or 15.2{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

  • Net interest expense increased $0.8 million, to $1.1 million from $0.3 million in the prior year comparable period. The additional expense was driven by the sale-leaseback transactions which included $0.5 million related to terminating the interest rate hedge early and $0.5 million non-cash write-off of deferred finance fees.

  • Net income of $24.0 million, or $0.73 per diluted share, compared to $46.0 million, or $1.44 per diluted share. In 2021, income tax provision was $12.5 million compared to $35.1 million tax benefit related to a full valuation allowance reversal in 2020.

  • Debt-free balance sheet as of December 31, 2021 after payoff of all outstanding debt in the fourth quarter compared to $17.8 million of borrowings in the prior year.

FOURTH QUARTER SEGMENT RESULTS
Transportation and Skilled Trades Segment
Revenue increased $4.3 million, or 7.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to $62.9 million from $58.6 million in the prior year comparable period. The increase in revenue results from a 7.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} higher average student population, driven by the 9.0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} increase in student starts for the year.

Operating income improved to $16.6 million from $15.6 million in the prior year comparable quarter, driven mainly by revenue growth.

Healthcare and Other Professions Segment
Revenue increased $1.7 million, or 7.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to $24.9 million from $23.2 million in the prior year comparable quarter. The increase in revenue results from a 3.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} higher average student population, driven by the 4.8{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} increase in student starts for the year, and a 3.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} increase in average revenue per student in the current quarter.

Operating income was $4.1 million down slightly from $4.7 million in the prior year comparable quarter due primarily to higher instructional salaries.

Corporate and Other
This category includes unallocated expenses incurred on behalf of the entire Company. Corporate and other expenses were $8.5 million compared to $9.2 million after excluding the $22.5 million gain from sale-leaseback transactions, partially offset by a one-time non-cash impairment charge of $0.7 million in the current year.

YEAR-END FINANCIAL RESULTS
(Period ended December 31, 2021 compared to December 31, 2020)

  • Total revenue increased by $42.2 million, or 14.4{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, to $335.3 million, compared to $293.1 million

  • Student starts grew by 1,081 or 7.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, to 15,402 compared to 14,321

  • Transportation and Skilled Trades segment revenue increased by $33.1 million, or 16.0{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, to $240.5 million, compared to $207.4 million

  • The Healthcare and Other Professions segment revenue increased by $9.1 million, or 10.7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, to $94.8 million, compared to $85.7 million

  • Adjusted EBITDA increased $14.2 million or 59{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to $38.1 million, compared to $23.9 million

  • Operating income increased to $49.3 million as compared to $14.8 million

FULL YEAR 2022 OUTLOOK

Through the combination of cash generated from Lincoln’s strong operating performance and additional liquidity provided by the sale-leaseback transactions, Lincoln entered 2022 with over $80 million of net cash. In addition, the Company has availability under its credit agreement and anticipates increasing its cash position from the contemplated consummation of the sale of its Nashville, Tennessee campus. Lincoln will utilize this strong balance sheet to increase its level of investment in growth strategies and operating efficiencies.

Specific operating and financial guidance for the coming year is as follows:

  • Revenue in the range of $350 million to $365 million

  • Student start growth in the range of 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

  • Adjusted EBITDA* in the range of $35.0 million to $40.0 million

  • Net Income in the range of $17.0 million to $22.0 million

  • Capital expenditures in the range of $7.0 million to $9.0 million

*See Use of “Non-GAAP Financial Information” below

The 2022 guidance excludes the impact of the contemplated consummation of the sale and relocation of the Nashville, Tennessee campus, which is under contract, as well as additional costs associated with a new potential campus. The outlook is based on, among other things, current enrollment trends and does not account for the impact from continuing COVID-19 issues or any new COVID-19 variants. Accordingly, as is always the case, the guidance may be revised as the year unfolds due to changes in student demand and other factors.

The Company is also providing additional information as to the progress of operations through 2022. This information represents management’s current expectations for the upcoming year and may be revised in-line with the developing business environment.

Revenue
Pursuant to the Company’s seasonality patterns, it is anticipated that approximately 45{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of revenue will occur in the first half of the year. Student starts are expected to increase in the low single digits during the first quarter, with higher start growth in the remainder of the year.

Operating Expenses
Operating expenses are expected to range in the low to mid $80 million level each quarter, with the third quarter’s expenses expected to reflect the high point of the year, consistent with the seasonality of the Company’s business. This higher level of operating expenses for the full year includes the addition of $3.2 million of rent expense resulting from the sale-leaseback transactions as well as $2.0 million of additional spending related to growth initiatives, efforts to streamline operations and development and implementation of improvements to Lincoln’s hybrid teaching model. First quarter operating expenses will show the largest increase year over year, as the first quarter of 2021 included a one-time $3.0 million benefit due to Care Act funds credited to student’s accounts.

Other
Interest expense, depreciation and amortization and stock-based compensation expense are expected to be approximately $0.4 million, $6.6 million, and $4.5 million respectively, recognized evenly throughout the year. The effective tax rate for the year is projected to be 28.5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

CONFERENCE CALL INFO
Lincoln will host a conference call today at 10:00 a.m. Eastern Daylight Time to discuss results. To access the live webcast of the conference call, please go to the Investor Relations section of Lincoln’s website at http://www.lincolntech.edu.
Participants can also listen to the conference call by dialing 844-413-0946 (domestic) or 216-562-0456 (international) and providing access code 2498132.
Please log in or dial into the call at least 10 minutes prior to the start time.

  • An archived version of the webcast will be accessible for 90 days at http://www.lincolntech.edu.

  • A replay of the call will also be available for seven days by calling 855-859-2056 (domestic) or 404-537-3406 (international) and providing access code 2498132.

ABOUT LINCOLN EDUCATIONAL SERVICES CORPORATION
Lincoln Educational Services Corporation is a provider of diversified career-oriented post-secondary education helping to provide solutions to America’s skills gap. For 75 years, Lincoln has offered and continues to offer recent high school graduates and working adults degree and diploma programs. The Company operates under two reportable segments: Transportation and Skilled Trades and Healthcare and Other Professions. Lincoln has provided the nation’s workforce with skilled technicians since its inception in 1946. For more information, go to www.lincolntech.edu.

SAFE HARBOR
Statements in this press release and in oral statements made from time to time by representatives of Lincoln Educational Services Corporation regarding Lincoln’s business that are not historical facts, including those made in a conference call, may be “forward-looking statements” as that term is defined in the federal securities law. The words “may,” “will,” “expect,” “believe,” “anticipate,” “project,” “plan,” “intend,” “estimate,” and “continue,” and their opposites and similar expressions are intended to identify forward-looking statements. Forward-looking statements are based on information available at the time those statements are made and/or management’s good faith belief as of that time with respect to future events, and are subject to risks and uncertainties that could cause actual performance or results to differ materially from those expressed in or suggested by the forward-looking statements. Forward-looking statements should not be read as a guarantee of future performance or results and will not necessarily be accurate indications of the times at, or by, which such performance or results will be achieved, if at all. Generally, these statements relate to business plans or strategies and projections involving anticipated revenues, earnings or other aspects of the Company’s operating results. Such forward-looking statements include the Company’s current belief that it is taking appropriate steps regarding the pandemic and that student growth will continue. The Company cautions you that these statements concern current expectations about the Company’s future performance or events and are subject to a number of uncertainties, risks and other influences many of which are beyond the Company’s control, that may influence the accuracy of the statements and the projects upon which the statements are based including, without limitation, impacts related to the COVID-19 pandemic, our inability to close on the sale of our Nashville campus; our failure to comply with the extensive regulatory framework applicable to our industry or our failure to obtain timely regulatory approvals in connection with acquisitions or a change of control of our Company; our success in updating and expanding the content of existing programs and developing new programs for our students in a cost-effective manner or on a timely basis; risks associated with changes in applicable federal laws and regulations; uncertainties regarding our ability to comply with federal laws and regulations, such as the 90/10 rule and prescribed cohort default rates; risks associated with the opening of new campuses; risks associated with integration of acquired schools; industry competition; our ability to execute our growth strategies; conditions and trends in our industry; the COVID-19 pandemic and its impact on our business and the U.S. and global economics; general economic conditions; and other factors discussed in the “Risk Factors” section of our Annual Reports and Quarterly Reports filed with the Securities and Exchange Commission. All forward-looking statements are qualified in their entirety by this cautionary statement, and Lincoln undertakes no obligation to publicly revise or update any forward-looking statements, whether as a result of new information, future events or otherwise after the date hereof.

(Tables to Follow)
(In Thousands)

Three Months Ended

Year-Ended

December 31,

December 31,

(Unaudited)

(Unaudited)

2021

2020

2021

2020

REVENUE

$

87,816

$

81,792

$

335,336

$

293,095

COSTS AND EXPENSES:

Educational services and facilities

34,788

31,463

138,931

122,196

Selling, general and administrative

40,762

39,188

168,923

156,199

(Gain) loss on disposition of assets

(22,479

)

15

(22,479

)

(81

)

Impairment of long-lived assets

700

700

Total costs & expenses

53,771

70,666

286,075

278,314

OPERATING INCOME

34,045

11,126

49,261

14,781

OTHER:

Interest expense

(1,142

)

(315

)

(2,015

)

(1,275

)

INCOME BEFORE INCOME TAXES

32,903

10,811

47,246

13,506

PROVISION (BENEFIT) FOR INCOME TAXES

8,939

(35,209

)

12,528

(35,059

)

NET INCOME

$

23,964

$

46,020

$

34,718

$

48,565

PREFERRED STOCK DIVIDENDS

304

304

1,219

1,378

INCOME AVAILABLE TO COMMON STOCKHOLDERS

$

23,660

$

45,716

$

33,499

$

47,187

Basic and Diluted

Net income per share

$

0.73

$

1.44

$

1.04

$

1.49

Weighted average number of common shares outstanding:

Basic and Diluted

25,180

24,831

25,081

24,748

Other data:

Adjusted EBITDA (1)

$

15,136

$

13,380

$

38,065

$

23,867

Depreciation and amortization

$

1,520

$

1,854

$

7,140

$

7,400

Number of campuses

22

22

22

22

Average enrollment

13,599

12,796

12,899

11,729

Stock-based compensation

$

796

$

400

$

2,889

$

1,686

Net cash provided by operating activities

$

9,697

$

13,263

$

27,447

$

23,485

Net cash provided by (used in) investing activities

$

43,100

$

(2,026

)

$

37,848

$

(5,483

)

Net cash used in financing activities

$

(16,640

)

$

(804

)

$

(20,014

)

$

(18,620

)

Selected Consolidated Balance Sheet Data:

December 31, 2021

(Unaudited)

Cash and cash equivalents

$

83,307

Current assets

121,627

Working capital

55,745

Total assets

295,299

Current liabilities

65,882

Long-term debt obligations, including current portion, net of deferred financing fees

Series A convertible preferred stock

11,982

Total stockholders’ equity

129,418

RECONCILIATION OF NON-GAAP FINANCIAL MEASURES

In addition to disclosing financial results that are determined in accordance with U.S. generally accepted accounting principles (“GAAP”), the Company believes it is useful to present non-GAAP financial measures that exclude certain significant items as a means to understand the performance of its business. EBITDA, Adjusted EBITDA, reconciled net cash and Adjusted Pre-tax income are measures not recognized in financial statements presented in accordance with GAAP.

  • We define EBITDA as income (loss) before interest expense (net of interest income), provision (benefit) for income taxes, depreciation and amortization.

  • We define Adjusted EBITDA as EBITDA plus stock compensation expense and adjustments for items not considered part of the Company’s normal recurring operations.

  • We define reconciled net cash as our cash and cash equivalents and restricted cash less both the short and long-term portion under the Company’s credit agreement, and deferred financing fees.

  • We define Adjusted pre-tax income as pre-tax net income before gain on sale of assets, non-cash impairment charges and expenses incurred resulting from the consummation of the sale-leaseback transactions.

EBITDA, Adjusted EBITDA, reconciled net cash and Adjusted Pre-tax income are presented because we believe they are useful indicators of our performance and our ability to make strategic acquisitions and meet capital expenditures and debt service requirements. However, they are not intended to represent cash flows from operations as defined by GAAP and should not be used as an alternative to net income (loss) as indicators of operating performance or cash flow as a measure of liquidity. EBITDA, Adjusted EBITDA, reconciled net cash and Adjusted Pre-tax income are not necessarily comparable to similarly titled measures used by other companies.

Following is a reconciliation of net income (loss) to EBITDA, Adjusted EBITDA, reconciled net cash and Adjusted Pre-tax income:

Three Months Ended December 31,

Year-Ended December 31,

(Unaudited)

(Unaudited)

2021

2020

2021

2020

Net income

$

23,964

$

46,020

$

34,718

$

48,565

Interest expense, net

1,142

315

2,015

1,275

Provision (benefit) for income taxes

8,939

(35,209

)

12,528

(35,059

)

Depreciation and amortization

1,520

1,854

7,140

7,400

EBITDA

35,565

12,980

56,401

22,181

Stock compensation expense

796

400

2,889

1,686

Gain on sale of asset

(22,479

)

(22,479

)

Impairment

700

700

Sale leaseback rent expense

554

554

Adjusted EBITDA

$

15,136

$

13,380

$

38,065

$

23,867

December 31,

(Unaudited)

2021

2020

Current portion of credit agreement and term loan

$

$

(2,000

)

Long-term credit agreement and term loan

(15,212

)

Cash and cash equivalents

83,307

38,026

Reconcilled net cash

$

83,307

$

20,814

December 31, 2021

(Unaudited)

Pre-tax net income

$

47,246

Gain on disposition of asset

(22,479

)

Non-cash impairment0

700

Sale leaseback expenses

1,684

Adjusted pre-tax income

$

27,151

Three Months Ended December 31,

2021

2020

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} Change

Revenue:

Transportation and Skilled Trades

$

62,945

$

58,636

7.3

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

HOPS

24,871

23,156

7.4

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total

$

87,816

$

81,792

7.4

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Operating Income (Loss):

Transportation and Skilled Trades

$

16,632

$

15,611

6.5

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions

4,101

4,681

-12.4

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Corporate

13,312

(9,166

)

245.2

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total

$

34,045

$

11,126

206.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Starts:

Transportation and Skilled Trades

1,467

1,438

2.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions

1,254

1,228

2.1

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total

2,721

2,666

2.1

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Average Population:

Transportation and Skilled Trades

9,087

8,536

6.5

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Leave of Absence – COVID-19

(82

)

100.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Transportation and Skilled Trades 1

9,087

8,454

7.5

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions

4,512

4,400

2.5

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Leave of Absence – COVID-19

(58

)

100.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions 1

4,512

4,342

3.9

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total

13,599

12,936

5.1

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total 1

13,599

12,796

6.3

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

End of Period Population:

Transportation and Skilled Trades

8,648

7,917

9.2

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Leave of Absence – COVID-19

(22

)

100.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Transportation and Skilled Trades 1

8,648

7,895

9.5

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions

4,411

4,402

0.2

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Leave of Absence – COVID-19

(80

)

100.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions 1

4,411

4,322

2.1

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total

13,059

12,319

6.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total 1

13,059

12,217

6.9

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

1 Excluding Leave of Absence – COVID-19

Year-Ended December 31,

2021

2020

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} Change

Revenue:

Transportation and Skilled Trades

$

240,531

$

207,434

16.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

HOPS

94,805

85,661

10.7

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total

$

335,336

$

293,095

14.4

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Operating Income (Loss):

Transportation and Skilled Trades

$

52,055

$

34,458

51.1

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions

11,845

11,068

7.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Corporate

(14,639

)

(30,745

)

52.4

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total

$

49,261

$

14,781

233.3

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Starts:

Transportation and Skilled Trades

10,291

9,442

9.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions

5,111

4,879

4.8

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total

15,402

14,321

7.5

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Average Population:

Transportation and Skilled Trades

8,505

7,872

8.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Leave of Absence – COVID-19

(12

)

(219

)

94.5

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Transportation and Skilled Trades 1

8,493

7,653

11.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions

4,439

4,232

4.9

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Leave of Absence – COVID-19

(33

)

(156

)

78.8

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions 1

4,406

4,076

8.1

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total

12,944

12,104

6.9

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total 1

12,899

11,729

10.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

End of Period Population:

Transportation and Skilled Trades

8,648

7,917

9.2

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Leave of Absence – COVID-19

(22

)

100.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Transportation and Skilled Trades 1

8,648

7,895

9.5

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions

4,411

4,402

0.2

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Leave of Absence – COVID-19

(80

)

100.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Healthcare and Other Professions 1

4,411

4,322

2.1

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total

13,059

12,319

6.0

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

Total 1

13,059

12,217

6.9

{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}

1 Excluding Leave of Absence – COVID-19

LINCOLN EDUCATIONAL SERVICES CORPORATION
Brian Meyers, CFO
973-736-9340

EVC GROUP LLC
Investor Relations: Michael Polyviou, mpolyviou@evcgroup.com, 732-933-2755
Media Relations: Tom Gibson, 201-476-0322