Why It Should Be on Your Radar

Why It Should Be on Your Radar

This story initially appeared on Zacks

Two components generally figure out stock selling prices in the prolonged run: earnings and interest charges. Traders won’t be able to command the latter, but they can aim on a firm’s earnings benefits each quarter.

– Zacks

We know earnings results are essential, but how a firm performs compared to bottom line expectations can be even additional critical when it comes to inventory prices, particularly in the near-time period. This implies that traders may well want to just take advantage of these earnings surprises.

Searching for ‘earnings whispers’ or firms poised to defeat their quarterly earnings estimates is a somewhat popular practice. But that isn’t going to make it easy. Just one way that has been tested to function is by using the Zacks Earnings ESP resource.

The Zacks Earnings ESP, Explained

The Zacks Earnings ESP, or Anticipated Shock Prediction, aims to come across earnings surprises by focusing on the most new analyst revisions. The primary premise is that if an analyst reevaluates their earnings estimate in advance of an earnings launch, it means they possible have new information and facts that could quite possibly be much more correct.

With this in brain, the Envisioned Shock Prediction compares the Most Correct Estimate (currently being the most current) against the over-all Zacks Consensus Estimate. The percentage difference supplies the ESP figure. The program also makes use of our core Zacks Rank to deliver a much better system for pinpointing shares that could conquer their up coming quarterly earnings estimate and maybe see the inventory rate climb.

When we join a optimistic earnings ESP with a Zacks Rank #3 (Maintain) or much better, stocks posted a beneficial bottom-line shock 70{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of the time. In addition, this program saw investors deliver about 28{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} once-a-year returns on typical, in accordance to our 10 yr backtest.

Most shares, about 60{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, fall into the #3 (Hold) classification, and they are anticipated to complete in-line with the broader marketplace. Shares with a #2 (Buy) and #1 (Powerful Purchase) score, or the prime 15{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and prime 5{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of shares, respectively, really should outperform the market place, with Strong Purchase stocks outperforming far more than any other rank.

Need to You Think about Cross Country Healthcare?

The final move today is to look at a inventory that satisfies our ESP skills. Cross Region Health care (CCRN) earns a #2 (Invest in) 30 times from its following quarterly earnings release on November 3, 2021, and its Most Accurate Estimate arrives in at $.39 a share.

CCRN has an Earnings ESP figure of 12.72{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, which, as spelled out higher than, is calculated by using the share big difference concerning the $.39 Most Precise Estimate and the Zacks Consensus Estimate of $.35. Cross Region Healthcare is one of just a massive database of stocks with positive ESPs. These stocks can be filtered by ESP, Zacks Rank, {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} Shock (Very last Qtr.), and Reporting day.

Now that you know how to use the Zacks Earnings ESP to your advantage, make positive to check out out the Earnings ESP Residence Website page for even a lot more earnings similar procedures to develop a successful portfolio.

Discover Stocks to Get or Promote Right before They’re Documented

Use the Zacks Earnings ESP Filter to transform up shares with the best likelihood of positively, or negatively, stunning to acquire or promote prior to they are described for worthwhile earnings year trading. Check out it out below >>

5 Shares Set to Double

Every single was handpicked by a Zacks pro as the #1 favourite stock to achieve +100{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} or a lot more in 2021. Earlier suggestions have soared +143.{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, +175.9{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}, +498.3{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} and +673.{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}.

Most of the shares in this report are traveling beneath Wall Street radar, which delivers a great opportunity to get in on the floor ground.

These days, See These 5 Possible Household Operates >>

Want the newest suggestions from Zacks Financial commitment Investigate? Right now, you can download 7 Most effective Stocks for the Following 30 Times. Click to get this no cost report
 
Cross Nation Health care, Inc. (CCRN): Free Inventory Evaluation Report
 
To examine this posting on Zacks.com click on right here.

Unlocking the potential of SMBs with Tata Tele Business Services

Unlocking the potential of SMBs with Tata Tele Business Services

India currently is powered by 6.5 crores micro, Smaller and Medium Enterprises (SMBs) that contribute 30 p.c to the country’s GDP. As the critical driver driving the financial growth of the nation, SMBs maximize employment possibilities, boost the producing sector and boost export competitiveness. While these businesses definitely experienced a blow in the wake of the pandemic, they are bouncing back again quick. As for each a current survey by The Financial Instances, 43 p.c of all MSMEs in India are selling their solutions as a result of on line retail retailers.

But the highway to achievements has never ever been a bed of roses for these business people. From weak protection infrastructure, increased globalisation to many seller factors, to absence of income flow, many issues plague their functions. And, deluged by a international overall health crisis, it has develop into progressively complicated to stay afloat. So how can SMBs rise to obstacle, turn out to be long run-completely ready and compete in the entire world arena?

A platform to quickly navigate ‘digital’

A analyze by Google-KPMG confirmed that digitally-empowered SMBs have about twice the profits expansion projections in comparison to digitally-laggard SMBs. A further review by SMB Team cited that on-line cloud-based mostly company purposes, web/online video conferencing methods, remote IT and access alternatives, and actual-time collaboration were most successful in assisting SMBs grow to be digitally agile to climate the COVID-19 storm and manage their business continuity and growth.

Foremost digital methods vendors like Tata Tele Enterprise Solutions (TTBS) have leveraged their deep consumer knowledge to empower tiny and medium companies with bespoke tech alternatives. With a higher-capability fibre optic network operating throughout 132,000 km, operations in above 60 towns, 1800+ partners and the greatest crew with 1600+ industry experts, TTBS is very well geared to cater to the compact and medium business neighborhood in India.

TTBS is a one-prevent system that presents the most extensive portfolio of electronic transformation alternatives. This includes Cloud & SaaS, facts, collaboration, voice, IoT solutions, advertising, cybersecurity and so on. It also lately launched SD-WAN iFLX, an clever and adaptable networking answer that enables SMBs to transform and make their community extra resilient to tackle intricate electronic and cloud applications. TTBS has also partnered with Zoom Movie Communications Inc, to give an intuitive, scalable, and safe communications resolution for modest and medium companies.

Harjit Singh, CEO, Tata Tele Small business Products and services claims, “The pandemic has accelerated digital adoption across sector sectors. While firms with a nicely-recognized electronic ecosystem have managed to tide more than the crisis smoothly, the vast majority have been jolted out of their consolation zones and have realised the importance of digital alternatives for survival and progress the tough way. The onus lies with tech businesses to develop related options to assistance SMBs in their transformation journey.”

He provides, “At TTBS, we have a progressive method of partnering with SMBs as a technology enabler/subject matter subject skilled. As a result of our extensive portfolio of ICT solutions, we find to simplify the electronic evolution of SMBs consequently enabling them to unleash their total potential and DO Big.”

Tapping into opportunities to scale

Whilst the ambiance is demanding, it is really also ripe with options. Governments, buyers, establishments and incubators are setting up a support technique to assistance SMBs attain their complete prospective. These days, smaller enterprise business owners can avail government techniques, investigate new marketplaces, empower tradition changes, and so on, to scale in the submit-COVID-19 era.

But the most essential stage is to change their organizations as a result of digitalisation. Going electronic will enable them to entry wider marketplaces, promptly join with shoppers, create flexible function environments, make far more income and enhance operational efficiencies.

Until just lately, SMBs experienced to commit a considerable total for engineering adoptions, but with the advent of cloud computing and the SaaS ecosystem, it has become economical and quick to make the shift.

What the long run retains for SMBs?

As we embrace the new usual, SMBs will have to be cognizant of the difficulties, uncertainties, and customer designs that lie ahead. The Indian govt aims to increase the MSME sector’s share in the GDP to 40 p.c to advantage the rural inadequate, Many thanks to the pandemic, technological innovation is no more an price for SMBs, but an investment and that usually means, we are just one step closer to fulfilling the goal of India’s $5 trillion economy.

Ashwini Fulzele, National Product sales Coordinator, Pinnacle Teleservices Pvt Ltd, shares how organizations are considering about progress and how an organisation like TTBS has served them navigate the pandemic disruption correctly. She states, “Tata Tele Enterprise Expert services assisted us speed up our electronic transformation by bettering procedures and consequently achieving clients much more correctly. As we stored rising and incorporating quantities, we needed to be foreseeable future-all set. The splendor of TTBS is that their advertising methods can be used in any natural environment where by expansion is the prime precedence.”

It can be a no-brainer that the companies very best suited to expand in the foreseeable future are by now investing in the newest know-how. Know additional about how TTBS answers can help SMBs avail an uncomplicated ticket to a digital long run.


Public Service Loan Forgiveness to get Education Department overhaul : NPR

Public Service Loan Forgiveness to get Education Department overhaul : NPR
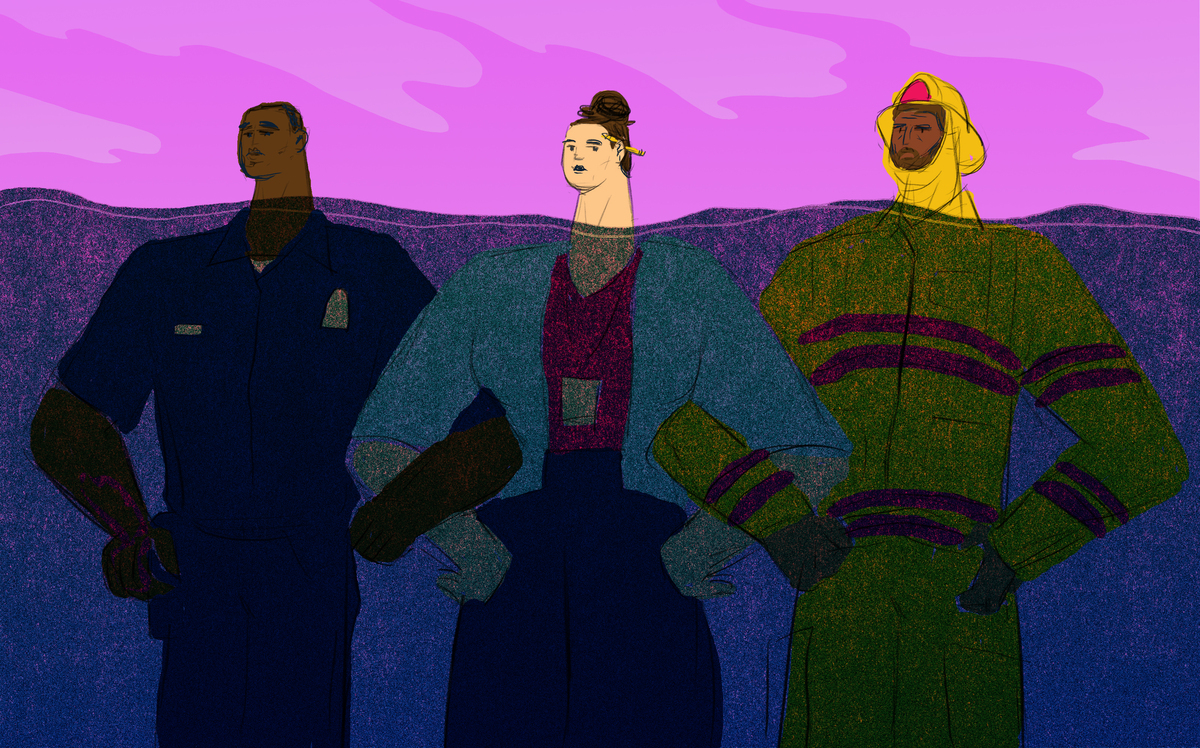
Police officer, teacher, and firefighter with their heads above water.

A troubled college student credit card debt relief application for instructors, law enforcement officers and other community assistance employees will soon get the makeover that borrowers have been demanding.

Upcoming 7 days, according to a source common with the options but who is not authorized to explore them publicly, the U.S. Division of Schooling will unveil a important overhaul of the General public Services Bank loan Forgiveness (PSLF) system, which has been a magnet of confusion, blunders and mismanagement due to the fact its inception in 2007.

The alterations will occur in two phases — a extended-phrase renovation to make the software much easier to navigate, obtained through the federal process acknowledged as rule-producing, and a short term move employing the department’s government authority to retroactively chill out the program’s policies to instantly assist countless numbers of affected borrowers.

Puzzling needs led to borrowers getting denied

Debtors must meet up with a handful of frequently-puzzling necessities to qualify for PSLF:

  • The borrower should perform in a general public sector work. 
  • The borrower must make 120 on-time college student mortgage payments. 
  • The borrower must take part in a competent reimbursement strategy. 
  • The borrower’s financial loans will have to be a particular sort, acknowledged as federal Direct Loans. 

For borrowers hoping for an quick route to mortgage forgiveness, these specifications have acted like the creaking wooden planks of a rope bridge, and, as NPR has reported, each and every plank has sent a group of frustrated community servants plunging.

For instance, what is community assistance? In accordance to the program’s Training Department site, public services involves any one operating for “a U.S. federal, point out, regional, or tribal government or not-for-financial gain business.”

But in a 2018 critique, the U.S. Federal government Accountability Business office found that when borrowers known as the organization managing PSLF to make guaranteed their positions experienced, they occasionally didn’t get an remedy — because the Instruction Department hadn’t supplied the corporation a checklist of suitable employers.

Additional not long ago, the College student Borrower Protection Middle, a nonprofit that has vocally pushed for PSLF reform, uncovered evidence that hundreds of borrowers who do do the job in capable general public service positions were being blocked from pursuing loan forgiveness.

The compensation program presents an additional obstacle, with several borrowers earning on-time payments, believing (and often being advised by their mortgage servicer) they were being on the path to forgiveness, only to know later that those payments hadn’t counted towards PSLF, simply because they experienced been made beneath the completely wrong compensation plan. In 2018, Congress developed an emergency enlargement of PSLF to attempt to deal with this.

And then there are the loans on their own. When PSLF was made, the lion’s share of federal student financial loans ended up identified as Federal Relatives Education and learning Loans (FFEL) — financial loans typically issued by banking companies but backed by the U.S. authorities. In 2010, FFEL was shuttered, and all new financial loans were being created less than the preexisting federal Direct Personal loan software. Although Direct Financial loans qualify for the personal loan forgiveness plan — FFEL loans do not.

Quite a few borrowers with FFEL loans put in years in public company, only to realize later that their payments did not count towards PSLF. Their only route to qualify was to consolidate their money owed into Direct Loans. But that consolidation arrives at a cost. Visualize a nurse operates for 3 yrs — and will make 36 mortgage payments — ahead of she realizes her FFEL loans never qualify. When she consolidates, her route to 120 payments will not start off at 37. It begins at zero.

In a June submitting, the Training Department’s Federal Student Assist business conceded that “over the several years, PSLF has spawned a great deal confusion and aggravation. Tens of millions of men and women are used in public service, including lecturers, firefighters, law enforcement, and some nonprofit workers, but only about 5,500 borrowers have been given PSLF discharges hence much, totaling $453 million.”

Now, the office ideas to use its government authority to assistance thousands of certified community servants get back again on the path to loan forgiveness.

The rapid fixes for current borrowers

In accordance to the resource common with the Education and learning Department’s options, the company will present a non permanent opportunity for any individual working in community company to get prior loan payments counted towards PSLF — even if people payments had been going towards disqualified FFEL financial loans.

And the department is not just increasing the principles close to loan type. Debtors will also acquire credit history for payments designed in the incorrect repayment prepare, irrespective of irrespective of whether the payment was produced on time.

To qualify for this do-in excess of, debtors will want to utilize for PSLF in advance of Oct. 31, 2022.

What is extra, for borrowers who were being informed to consolidate older loans into Direct Loans but had formerly licensed their several years of general public service, the division programs to automatically alter their payment counts, supplying them credit score for payments made just before consolidation. In the circumstance of that hypothetical nurse, this usually means her payment rely would not reset at zero it would now contain people 36 earlier payments.

According to a source familiar with the information, 60{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of borrowers who are not nonetheless suitable for PSLF for the reason that they haven’t created more than enough qualified payments also have — or at one position had — ineligible loans. This transfer to give them credit for payments on individuals formerly ineligible financial loans could quickly-track some debtors who had all but given up on financial loan forgiveness.

Even debtors who did not certify all those early years of community services will be capable to do so retroactively and get credit rating for individuals early FFEL payments.

For armed service service users, the office will also enable all months put in on energetic duty to rely towards PSLF, even if their bank loan payments were paused.

Particulars of the department’s plans, acquired by NPR, propose that tens of countless numbers of borrowers could most likely see their loans canceled, though hundreds of thousands could at minimum see a drop in the number of payments they are needed to make.

The section is anticipated provide far more information next week to enable debtors navigate these modifications.

Extended-term fixes are also on the way

In addition to working with its government authority to assistance borrowers get credit rating for disqualified payments, the office also options to use the rule-building system to overhaul PSLF for the very long-expression.

Probable modifications involve simplifying guidelines all-around qualifying payments and providing debtors credit score even if payments are late or created in installments.

The section also wants to give borrowers credit for PSLF even if, less than selected situation, their payments have been paused, these as for energetic-responsibility company members and borrowers facing financial hardships.

Even the definition of community support is up for assessment. Underneath the current procedures, a lot of nurses and health care personnel you should not qualify for the system for the reason that they perform in for-income hospitals, for case in point.

In an acknowledgement that borrowers’ denials under the PSLF software can be frustratingly opaque, the section also would like to make a official reconsideration process so debtors can clearly clarify them selves and suitable mistakes when important.

Borrowers have voiced their stress with PSLF

The expected alterations to PSLF come soon after a sustained, decades-long drive by borrower advocates. In September, far more than 200 corporations — symbolizing learners, instructors, public wellbeing employees and army service users — despatched a letter to U.S. Secretary of Education and learning Miguel Cardona, urging him “to just take administrative motion to assure that all general public provider employees who have completed a ten years of services receive the personal debt reduction they were being promised … This action need to be immediate and will need not wait for the Office of Training to write new rules.”

The letter was led by the University student Borrower Security Centre and co-signed by the nation’s two largest academics unions.

The Biden administration had already built very clear its want to overhaul PSLF, which was intended, in spirit, to really encourage borrowers to perform in community support.

“We’re heading to resolve General public Support Bank loan Forgiveness,” Cardona told NPR two days right before he obtained that aforementioned letter. “That method is broken. We’re heading to overhaul it and take care of it and make it get the job done for college students.”

In July, the department posted a general public ask for for information and facts about the program. In about two months, the ask for has generated a lot more than 48,000 responses.

“I put in yrs in the improper payment plan for very little,” wrote Scott Friedman of Los Angeles. “The entire matter is broken.”

Friedman echoes a lot of of the opinions when he writes, “It must be basic — if you can exhibit you worked in the community sector for 10 years that really should be adequate.”

“This method has been plagued with deceptive, untrue information and facts from the begin,” reads a comment from Arizona firefighter Russell Smith. “Not one particular of us in General public Support ‘expects’ this, but it was made available as a government system and our government should do every little thing in their electrical power to make it ideal.”

It now appears which is what the U.S. Division of Instruction intends to do.
31.7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Nigerian youths lack access to bank loans for businesses

31.7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of Nigerian youths lack access to bank loans for businesses

The bureau said this in its National Youth Survey for 2020, obtained from its website in Abuja on Monday, Travel & Tips.

According to it, the report is a collaborative effort between the Federal Ministry of Youth and Sports Development and the NBS.

It also said that stringent bank polices, government policies and other measures adopted by banking institutions make it difficult for youths to finance their businesses through bank loans.

Giving a breakdown of the result from the survey, the NBS said that stringent bank policies accounted for 24.8 per cent youths not having access to bank loans, 7.3 per cent attributed their challenges to government policies while 13.2 per cent of the youths gave other reasons.

“At zonal level, youths from South-South 45.7 per cent and South West 35.5 per cent could not access bank loan due to high rate of interest while youths from North-West 54.5 per cent and North-Central 33.8 per cent could not access bank loans due to stringent policies.

“Youths from South-South 15.7 per cent and North-East 13.3 per cent could not access bank loans due to government policies.”

It however said that for those that had access to bank loans, nationally, 55.1 per cent female youths had access than their male counterparts put at 44.9 per cent.

Analysing major challenges facing youths in businesses, the report said that the survey indicated different types of challenges faced by youths in their business enterprises.

According to it, nationally, 86.1 per cent of youths faced the challenge of access to fund to finance their businesses, while 4.9 per cent faced the challenge of inconsistency in government policies.

It said that another 4.6 per cent faced the challenges of obsolete equipment while three per cent faced the challenges of lack of proper training in relation to their businesses.

“At zonal level, most youths from all the zones reported the challenge of financing their businesses; youths from South-West (100 per cent) top the list followed by North-East at 93.6 per cent while youths from South-East (78.1 per cent) were least.

“However, youths from North-Central (9.2 per cent) faced the challenge of obsolete equipment for their businesses followed by youth from South-East (3.5 per cent).

“Meanwhile, youths from South- East (10 per cent) reported inconsistencies in government policies as a major challenge affecting their businesses.”

For sources of business funding, the survey reported that youths across the six geo-political zones source for funds to set up their businesses enterprises through personal savings, loans, family sources, cooperative/Esusu, grants and other sources.

It said that nationally, 34.5 per cent of youths sourced fund through government grants to set up their business enterprises, while 29.7 per cent of youths used their personal savings.

The report added that 15.1 per cent sourced funds through cooperative thrift and 2.4 per cent of the youth obtained loan to start up their business enterprises.

“The results on zonal level shows that 96.6 per cent of youths from South-South obtained grants to start-up businesses and 49.2 percent of youths from North-Central also obtained grants to start-up their businesses.

“Meanwhile, in the South-West, 26.2 per cent of youths acquired fund through cooperative thrift to start-up their businesses, while in the North-West 44.4 per cent and South-West 24.8 per cent of youths obtained funds through other sources.”

It added that across the six geo-political zones, more female youths (65.4 per cent) operated business enterprises than their male counterpart.

It said that the North-West with 82.9 per cent had the highest number of female youths who operated business enterprises followed by South-South (73.5 per cent), North Central (70.7 per cent), while the North-East had 36 per cent.

On the other hand, 64 per cent male youths in North East engaged in business, more than females followed by South-East (57.7 per cent) while the North West had just 17.1 per cent male youths in business enterprises.

For business registration, the result indicated that only 8.9 per cent of youths registered business enterprises across the six geo-political zones.

The News Agency of Nigeria (NAN) reports that the survey is a follow up on the National Baseline Youth Survey 2012 version, as the NBS attempts to fulfill its mandate of providing credible and comprehensive statistics on all levels of the country.

Furthermore, the report enhances the ability of policy makers and other stakeholders to improve the efficacy of policies they put forward through the use of evidence based data.

Home Decorating
Travel Tips
Classic Car

31.7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} youths lack access to bank loans for business -NBS

31.7{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} youths lack access to bank loans for business -NBS

The National Bureau of Studies claims that 31.7 percent of youths in Nigeria absence obtain to financial institution financial loans to finance their firms owing to significant interest charges.

The bureau stated this in its Countrywide Youth Study for 2020, received from its web-site in Abuja on Monday.

In accordance to it, the report is a collaborative work in between the Federal Ministry of Youth and Sporting activities Improvement and the NBS.

It also stated that stringent bank guidelines, governing administration guidelines and other actions adopted by banking institutions make it difficult for youths to finance their enterprises by bank loans.

Giving a breakdown of the final result from the survey, the NBS claimed that stringent financial institution guidelines accounted for 24.8 for every cent youths not getting access to financial institution financial loans, 7.3 per cent attributed their problems to governing administration policies when 13.2 for every cent of the youths gave other explanations.

“At zonal stage, youths from South-South 45.7 per cent and South West 35.5 percent could not obtain financial institution financial loan because of to large price of fascination price though youths from North-West 54.5 p.c and North-Central 33.8 per cent could not access bank financial loans thanks to stringent policies.

“Youths from South-South 15.7 for every cent and North-East 13.3 for every cent could not entry financial institution financial loans thanks to federal government procedures.”

It, however, claimed that for all those that experienced accessibility to bank financial loans, nationally, 55.1 percent female youths had access than their male counterparts, put at 44.9 p.c.

Analysing key challenges going through youths in companies, the report explained that the study indicated diverse varieties of worries faced by youths in their company enterprises.

In accordance to it, nationally, 86.1 percent of youths confronted the obstacle of accessibility to fund to finance their organizations, even though 4.9 for each cent faced the challenge of inconsistency in government insurance policies.

It stated that another 4.6 for every cent faced the problems of obsolete gear when three for each cent confronted the challenges of absence

of proper training in relation to their firms.
“At zonal level, most youths from all the zones reported the problem of funding their companies youths from South-West (100 per cent) major the record followed by North-East at 93.6 per cent, when youths from South-East (78.1 for each cent) have been least.

“However, youths from North-Central (9.2 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}) faced the problem of out of date devices for their organizations followed by youth from South-East (3.5 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}).

“Meanwhile, youths from South- East (10 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}) described inconsistencies in authorities insurance policies as a major challenge impacting their companies.”

For resources of organization funding, the survey documented that youths across the 6 geo-political zones supply for money to established up their corporations enterprises as a result of personalized discounts, loans, spouse and children sources, cooperative/Esusu, grants and other resources.
It reported that nationally, 34.5 p.c of youths sourced fund by means of govt grants to set up their business enterprises, though 29.7 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of youths utilised their own financial savings.

The report added that 15.1 percent sourced cash via cooperative thrift and 2.4 for every cent of the youth received financial loan to get started up their business enterprises.

“The outcomes on zonal degree displays that 96.6 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of youths from South-South acquired grants to start out-up enterprises and 49.2 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} of youths from North-Central also obtained grants to start off-up their organizations.

“Meanwhile, in the South-West, 26.2 p.c of youths obtained fund by way of cooperative thrift to start out-up their organizations, though in the North-West 44.4 p.c and South-West 24.8 p.c of youths obtained cash by other resources.”

It additional that throughout the 6 geo-political zones, far more woman youths (65.4 per cent) operated enterprise enterprises than their male counterpart.

It stated that the North-West with 82.9 percent had the highest amount of female youths who operated business enterprises followed by South-South (73.5 p.c), North Central (70.7 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550}), though the North-East experienced 36 p.c.

On the other hand, 64 percent male youths in North East engaged in business enterprise, far more than women followed by South-East (57.7 per cent) whilst the North West experienced just 17.1 {ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} male youths in enterprise enterprises.

For small business registration, the consequence indicated that only 8.9 percent of youths registered company enterprises across the 6 geo-political zones.

The Information Agency of Nigeria reports that the survey is a stick to up on the Countrywide Baseline Youth Survey 2012 model, as the NBS makes an attempt to satisfy its mandate of offering credible and extensive figures on all amounts of the country.

Additionally, the report enhances the ability of coverage makers and other stakeholders to enhance the efficacy of policies they place forward through the use of proof based info.

(NAN)

Higher loan limit now available for USDA guaranteed farm loans

Higher loan limit now available for USDA guaranteed farm loans

WASHINGTON — The U.S. Section of Agriculture is announcing a larger bank loan limit will be offered for debtors in search of a confirmed farm financial loan commencing Oct. 1, 2021, from $1.776 million to $1.825 million.

“Farm financial loans are critical for our customers’ once-a-year running and spouse and children dwelling expenses, unexpected emergency desires, and hard cash circulation,” FSA Administrator Zach Ducheneaux explained. “Raising the confirmed personal loan restrict will allow FSA to greater fulfill the economic demands of producers as organic disasters and the pandemic carry on to impact their operations.”

FSA farm financial loans give entry to funding for a broad variety of producer requires, from securing land to funding the obtain of devices. Guaranteed financial loans are financed and serviced by commercial loan companies. FSA supplies up to a 95{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} warranty against possible economical loss of principal and fascination. Guaranteed loans can be utilised for both farm ownership and running uses.


In fiscal calendar year 2021, FSA saw ongoing sturdy desire for assured loans. FSA obligated much more than $3.4 billion in assured farm possession and functioning loans. This contains almost $1.2 billion for beginning farmers. The number of certain debtors has grown by 10{ac23b82de22bd478cde2a3afa9e55fd5f696f5668b46466ac4c8be2ee1b69550} to additional than 38,750 farmers and ranchers about the past ten years. FSA expects the escalating demand from customers for farm financial loans to proceed into fiscal yr 2022.

Catastrophe Set-Apart


USDA has more guidance out there to producers specified the modern outbreaks of the COVID-19 Delta variant and has prolonged the availability of COVID-19 Catastrophe Set-Apart (DSA) for installments thanks via Jan. 31, 2022. In addition, FSA will permit a 2nd DSA for COVID-19 and a second DSA for purely natural disasters for all those who had an original COVID-19 DSA. Requests for a COVID-19 DSA or a 2nd DSA will have to be been given no later on than May perhaps 1, 2022.

Past 12 months, FSA broadened the use of the DSA. Normally employed in the wake of purely natural disasters, the DSA can now let farmers with USDA farm loans who are afflicted by COVID-19 and determined to be suitable, to have their up coming payment set apart. The set-aside payment’s thanks day is moved to the closing maturity day of the bank loan or prolonged up to 12 months in the circumstance of an yearly operating loan. Any principal set-apart will proceed to accrue desire until it is repaid. This will improve the borrower’s cashflow in the present-day production cycle.

Producers can take a look at offered options on all FSA loan alternatives at fsa.usda.gov or by speaking to their regional USDA Company Heart. Service Heart workers keep on to work with agricultural producers through cell phone, e mail and other digital resources. Simply because of the pandemic, some USDA Assistance Centers are open to constrained visitors. Make contact with your Company Center to established up an in-man or woman or phone appointment. Also, extra facts connected to USDA’s reaction and aid for producers can be observed at farmers.gov/coronavirus.